Home loan balance transfer: move to a lower rate
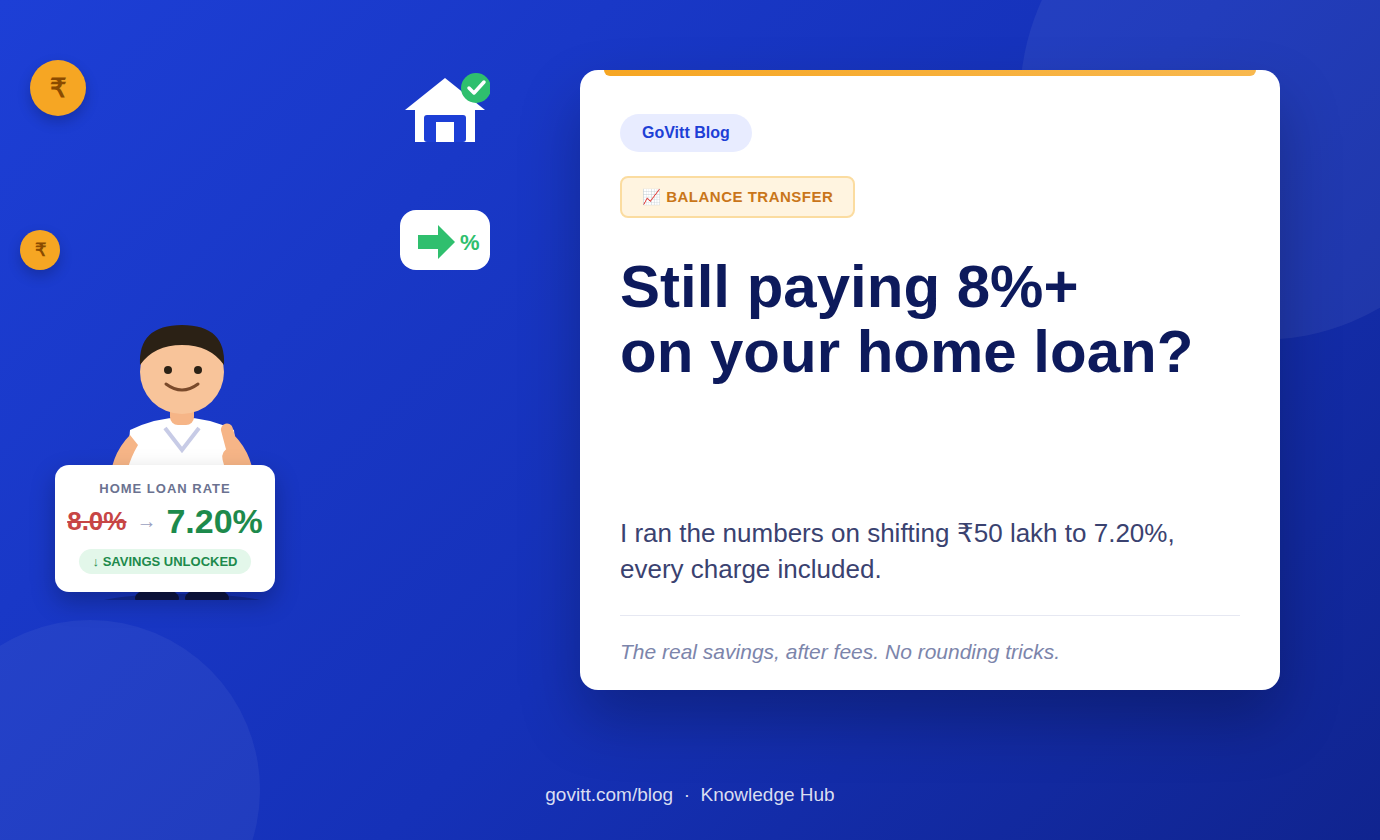
Still paying 8% or more? Rates for good credit profiles start around 7.10%*. We compare lenders for you, count every charge, and tell you honestly if a transfer is worth it.
as of October 1, 2026
*For borrowers with a good credit profile. Your rate depends on credit score, income and property.
What a balance transfer saves on ₹50 lakh
Example: ₹50 lakh outstanding, 20 years left, moving to 7.20%. Charges of about ₹80,000 already taken off.
| Rate you pay now | EMI lower by | Saved after charges (lower EMI) | Saved after charges (same EMI, finish early) |
|---|---|---|---|
| 8.00% | ₹2,455 | ₹5.09 lakh | ₹11.24 lakh |
| 8.50% | ₹4,024 | ₹8.86 lakh | ₹18.06 lakh |
| 9.00% | ₹5,619 | ₹12.69 lakh | ₹24.50 lakh |
What a balance transfer costs in Bengaluru
Most ads skip this part. On a ₹50 lakh loan, expect roughly ₹54,000 to ₹77,000.
| Charge | Approx. amount on ₹50 lakh |
|---|---|
| Processing fee (incl. 18% GST) | ₹17,700 to ₹29,500 |
| Legal and technical valuation | ₹5,000 to ₹15,000 |
| MODT stamp duty (0.5% of loan, Karnataka) | ₹25,000 |
| MODT registration (about 0.1%) | ₹5,000 |
| CERSAI, scanning, small charges | ₹1,000 to ₹2,000 |
| Foreclosure charge at old bank (floating rate) | ₹0 |
Fixed rate loans can carry a prepayment charge. Check your loan agreement before you apply.
When a transfer makes sense, and when it doesn't
Usually worth it
- You pay 8.5% or more
- The rate gap is 0.5% or more
- More than ₹20 lakh and 8+ years are left
- Your CIBIL score is 750 or above
Usually not worth it
- The rate gap is under 0.5%
- Your loan is small or almost finished
- You plan to sell the house in 2 to 3 years
- Property papers have an issue (khata not updated, no OC)
Not sure? Send us your rate, outstanding amount and years left. We'll tell you straight, even if the answer is "stay where you are".
Try this before you switch
Write to your current bank and ask for the rate they give new customers. Many banks allow this for a small fee, with no new MODT or legal charges. If they come close, take it. If they don't, you have your answer.
You'll probably like working with GoVitt if...
- You want your savings shown after every charge, not a headline number
- You'd rather hear "stay where you are" than get pushed into a transfer that doesn't pay off
- You want one person to compare 50+ lenders and chase both banks for you
- You want to know your real payoff date, not just the EMI count your bank shows
- You don't want to pay a commission for any of it
We're probably not the right fit if...
- You only want the lowest rate on a poster and won't look at the fees
- You want your file pushed through no matter what the paperwork says
- You need the transfer done in a few days. A proper one takes 2 to 4 weeks
Deepesh Jangid, CA · Founder, GoVitt
How a balance transfer works
Check your CIBIL score and keep your documents ready
Get a foreclosure letter and list of documents from your current lender
Apply with the new lender. Their lawyer and valuer check your property
Read the Key Fact Statement and sign the sanction
New lender pays your old lender directly. Your original papers are released
New MODT is registered and EMIs start with the new lender
In Bengaluru this usually takes 2 to 4 weeks. GoVitt handles the follow-ups with both lenders.
Documents you'll need
Find out what you'd actually save
Free. No commission. No impact on your credit score.
Home loan balance transfer: common questions
What is a home loan balance transfer?
How many EMIs should I pay before a balance transfer?
Will my current bank charge a foreclosure fee?
What are the charges for a balance transfer in Karnataka?
Does a balance transfer affect my CIBIL score?
Should I reduce my EMI or my tenure after switching?
Does GoVitt charge anything?
Deepesh is a Chartered Accountant who helps Bengaluru borrowers compare home loans and balance transfers across 50+ lenders.
About GoVitt →Related reading
Rates and charges are as of October 2026 and for illustration only. Your actual rate depends on your credit score, income and property. Charges vary by lender and state.