Let's start with an easy one.
You took a 20-year home loan in 2021. You've paid 60 EMIs. How many are left?
180, right? 240 minus 60. That's what most people would say. It's also what your sanction letter still says, because that document was made on day one and nobody ever updates it.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
For many people who borrowed in 2020 or 2021, the real answer can be closer to 220. Sometimes more.
Let me show you why with one example, and then how to check your own loan in about two minutes.
A very normal example
Say you took a ₹50 lakh home loan in August 2021. 20 years, repo-linked, at 6.75%. Your EMI was ₹38,018 and your last EMI was supposed to be in August 2041.
Then this happened:
- Between May 2022 and February 2023, RBI raised the repo rate by 2.5%. Your rate went from 6.75% to 9.25%.
- Your bank didn't raise the EMI straight away. It kept the EMI the same and stretched the tenure.
- By November 2022, the loan had hit the bank's 30-year maximum. Only then did it start increasing the EMI, and by March 2023 you were paying ₹40,421.
- In 2025, RBI cut the repo rate by 1.25%. Your rate came down to 8% by January 2026. The bank kept the EMI at ₹40,421, so the tenure came down again, but not back to 20 years.
Now it's August 2026 and 60 EMIs are done. Here's where you actually stand:
| What you think | What's real | |
|---|---|---|
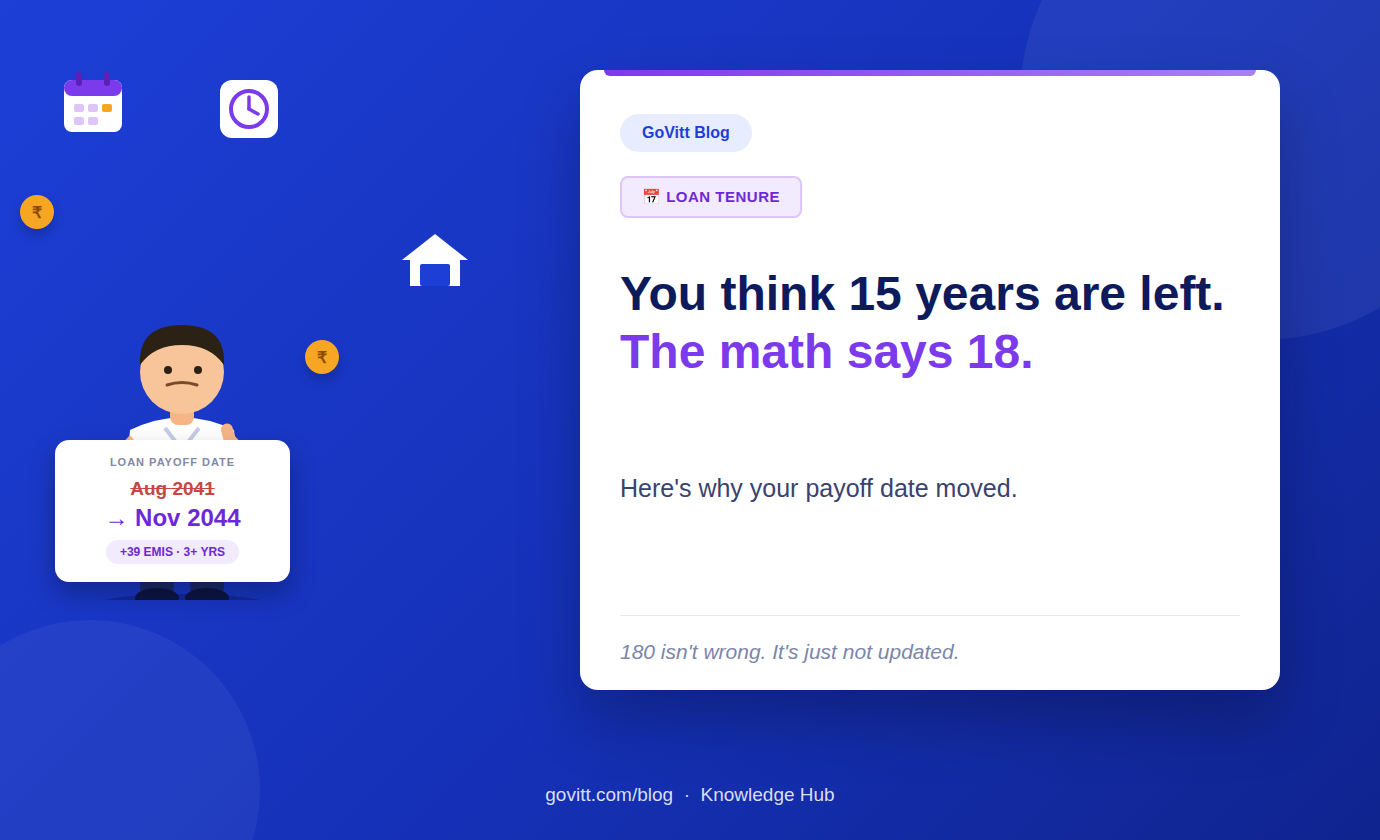
| EMIs left | 180 | 219 |
| Last EMI | August 2041 | November 2044 |
| Still to pay | ₹72.8 lakh | ₹88.5 lakh |
That's 39 more EMIs than you planned for. More than 3 years, and about ₹15.7 lakh more going out of your account.
And this is the part that stings. In these 5 years you've paid ₹23.86 lakh in EMIs. Only ₹3.53 lakh of that reduced your loan. The other ₹20.33 lakh was interest. If rates had not moved at all, you would have cleared ₹7.04 lakh of principal by now.
Why the bank's number and the real number don't match
There isn't one villain here. It's a few things adding up.
Your sanction letter is a one-time calculation. It was worked out at 6.75% on day one, and the end date on it doesn't change when your rate changes. Some bank apps and loan summaries also still show the original end date, or show "EMIs remaining" as simply 240 minus what you've paid.
Your rate is not fixed. A repo-linked loan moves when RBI changes the repo rate, from your next reset date. MCLR-linked loans usually reset once a year. If your loan is with a housing finance company, the rate moves when the company changes its own benchmark.
When rates went up, many lenders stretched the tenure instead of raising the EMI. A higher EMI is something you notice the same month. A longer tenure is something most people never notice at all. In August 2023, RBI said its reviews had found "unreasonable elongation of tenor of floating rate loans by lenders without proper consent and communication to the borrowers." That's the regulator's wording, not mine.
Rate cuts didn't undo it. When rates came down in 2025, tenures came down too. But if you borrowed in 2020 or 2021, today's rate is still higher than the one you started with, so the loan is still longer than the original plan.
Prepayments change it too, in the good direction. If you've made part-payments, your real payoff date could be earlier than what your app shows.
RBI rules that are on your side
After those findings, RBI put some rules in place for floating rate EMI loans, and home loans are covered. Lenders had to apply them to existing loans as well, by December 2023:
- If your EMI or tenure goes up because of a rate change, the lender has to tell you immediately.
- At a reset, you get to choose between a higher EMI, a longer tenure or a mix of both. You can also prepay, in part or in full, at any time.
- The tenure can't be stretched so far that your EMI stops covering the interest.
- Every quarter, the lender has to give you a statement showing the principal and interest paid so far, your EMI, the number of EMIs left and your rate.
So that quarterly statement is the first thing to look at. If it's not in your email, check the loan section of your bank app or netbanking, or ask the branch for it.
How to find your real payoff date in 2 minutes
Take your latest loan statement and note down three numbers:
- Principal outstanding (not "total outstanding", which can include interest due or charges)
- Your current rate of interest
- Your current EMI
Then do any one of these.
Use our calculator. Put those three numbers into GoVitt's free Payoff & Transfer Calculator. No documents needed.
Use Excel or Google Sheets. I'm a CA, so this is where I go first. Type =NPER(rate/12, -EMI, principal outstanding). For the example above, =NPER(8%/12, -40421, 4647377) gives 218.9, so 219 EMIs are left. Count that many months forward from your last EMI and you have your real payoff month.
Do a quick sanity check. Multiply your principal outstanding by your rate and divide by 12. That's roughly this month's interest. In our example it comes to ₹30,983, which is 77% of the ₹40,421 EMI. The closer this number is to your EMI, the more even a small rate hike will stretch your loan.
Then compare your answer with the "EMIs left" on the bank's quarterly statement. If the two don't match, write to the bank and ask for an updated repayment schedule.
One more thing. In the example, if rates go up by just 0.5% and the bank stretches the tenure again, that's about 20 more EMIs. And don't assume rates will only go down from here. The median one-year MCLR of banks went up from 8.60% in July to 8.70% in August 2026. RBI's draft rules for April 2027 also propose that, for most lenders, floating rates reset at least once every three months, so your payoff date could change more often. We explained that draft in our post on RBI's new loan pricing rules.
How to pull your payoff date back
Here's what each option does to the loan in our example (₹46.47 lakh outstanding at 8%, EMI ₹40,421):
| What you do | Loan ends | Interest saved |
|---|---|---|
| Nothing | Nov 2044 | ₹0 |
| Raise EMI by ₹3,992 | Aug 2041 | ₹8.54 lakh |
| Raise EMI by ₹5,000 | Jan 2041 | ₹10.14 lakh |
| Prepay ₹1 lakh every year | Aug 2039 | ₹13.64 lakh |
| Shift to 7.20%, same EMI | Dec 2042 | ₹9.38 lakh |
| Shift to 7.20% and add ₹5,000 to EMI | Dec 2039 | ₹16.23 lakh |
Raising the EMI is the cleanest fix if your budget allows it. Just ₹3,992 more a month puts you back on your original August 2041 end date. Make it ₹5,000 and you finish even before that. Write to your lender asking for the higher EMI and a revised repayment schedule. At your next reset, RBI rules give you this choice anyway.
Prepaying works well if you get a yearly bonus. There are no prepayment charges on floating rate home loans taken by individuals. When you prepay, tell the bank in writing that you want the tenure reduced, not the EMI.
Shifting to a lower rate fixes the actual cause. Moving to 7.20% alone brings the end date back to December 2042. But a balance transfer comes with charges, roughly ₹54,000 to ₹77,000 on a ₹50 lakh loan in Bengaluru. I did the full math on that, charges included, in this post. Even after ₹80,000 of charges, the transfer saves ₹8.58 lakh in this example. Before you apply anywhere, ask your own bank to match the rate first.
Or combine them. Shift to 7.20% and add ₹5,000 to the EMI, and the loan ends in December 2039. That's almost 5 years earlier than where it's heading right now.
When you don't need to worry much
Not everyone's loan got longer. This matters less if:
- You borrowed when rates were higher, around 2018 or 2019, and your rate today is lower than your starting rate. Your real payoff date may actually be earlier than planned. Still worth checking.
- You're on a fixed rate. Your tenure only changes if you prepay.
- You have just a few years left. The stretch is smaller in rupee terms. Checking still only takes two minutes.
If your bank never told you
If your EMI or tenure went up after December 2023 and nobody from the bank informed you, raise it. Write to the bank's grievance cell first and keep the complaint number. If they don't reply within 30 days, or you're not happy with the reply, you can file a complaint with the RBI Ombudsman at cms.rbi.org.in.
Check yours today
Your numbers will be different from this example. The only way to know is to check.
Put your principal outstanding, rate and EMI into our free Payoff & Transfer Calculator and it'll show you your real payoff date. Or WhatsApp those three numbers to us on +91 70194 17854, and we'll send you your real payoff date and what it would take to bring it back. GoVitt works with 50+ banks and housing finance companies, and we don't charge you any commission.
The example assumes a repo-linked loan priced at repo plus 2.75%, every rate change passed on from the month after RBI's decision, and a 30-year maximum tenure. It's for illustration only. Your lender's reset dates and policies decide your actual numbers.
Questions people usually ask
Why is my home loan tenure longer than what I signed for? Most likely your interest rate went up after you took the loan, and your lender kept the EMI the same and extended the tenure. This happened to many borrowers during the 2022-23 rate hikes. If your rate is still higher than your starting rate, the tenure stays longer than the original plan.
How do I calculate how many EMIs are left on my home loan? You need three numbers from your loan statement: principal outstanding, current interest rate and current EMI. Put them in GoVitt's Payoff & Transfer Calculator, or use =NPER(rate/12, -EMI, principal outstanding) in Excel or Google Sheets.
Can my bank increase my loan tenure without telling me? RBI's rules require lenders to inform you immediately if your EMI or tenure goes up because of a rate change, and to give you the choice of a higher EMI, a longer tenure or a mix at reset. If that didn't happen, complain to the bank first and then to the RBI Ombudsman if needed.
Is it better to increase the EMI or the tenure when rates go up? If you can afford it, increase the EMI. A longer tenure means you pay interest for more years, so the total cost goes up a lot more.
Should I reduce EMI or tenure when I prepay? Reduce the tenure if your current EMI is comfortable. That saves more interest. Tell your lender in writing, because not every lender does the same thing by default.
Why didn't my tenure come down after RBI cut rates? A few possible reasons. Your lender may have reduced your EMI instead of the tenure, your reset date may not have come yet, or your loan may be linked to MCLR or a housing finance company's benchmark, where cuts reach borrowers more slowly. Check your latest statement or ask your lender.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.