
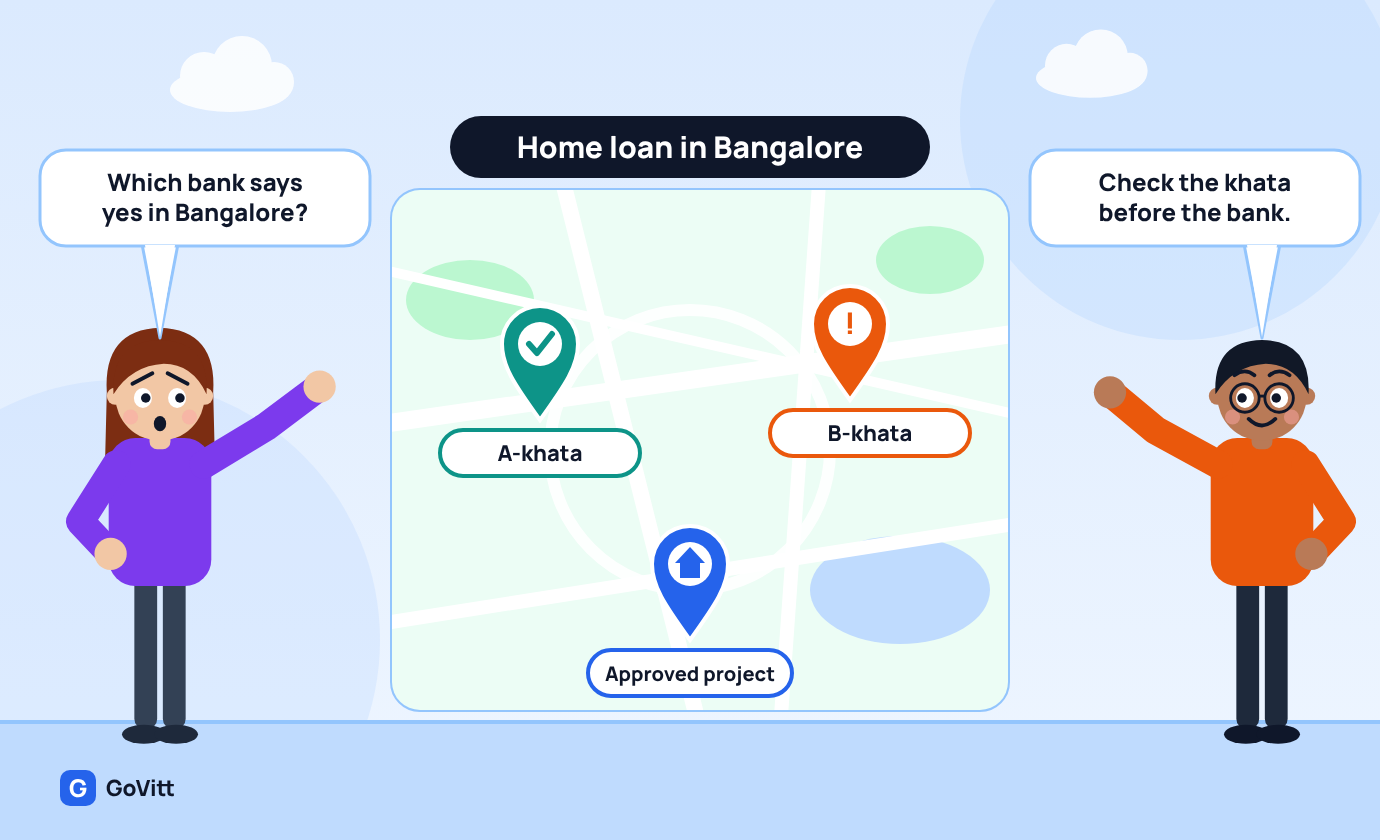
A home loan in Bangalore rarely goes wrong at the bank. It goes wrong at the property: a B-khata, a draft e-khata, an old mortgage still showing on the encumbrance certificate. If the paper is clean, no lender is "easiest", because the real differences are price and fees. On ₹50 lakh over 20 years, the lowest rates published by eight lenders sit ₹4,970 a month apart, and processing fees run from ₹0 to ₹59,000.
Below: what I can and can't tell you about which bank lends easiest, what the lenders publish, which one to start with for your situation, the Bengaluru paperwork that stalls files, and what to do this week.
First, the honest part
I can't tell you which bank is "easiest" for Bangalore, and nobody who says so with a straight face has data to back it. Banks don't publish approval rates or turnaround times. What I can compare is what they do publish: rate, fee and rules. Four more limits:
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
- The lowest rate is for the strongest profile. Yours will be higher. The rate posts linked below show each lender's slabs.
- Some floors are quoted for smaller loans. LIC Housing Finance and Canara quote their lowest rates for loans up to ₹50 lakh, so I use ₹50 lakh below. It is under what many Bengaluru flats need, but it is the size at which every floor applies.
- No lender I found publishes its B-khata policy. So I name none for B-khata. It is case by case.
- Canara Bank is headquartered in Bengaluru. I found nothing saying that changes how it treats a Bengaluru file, so I read nothing into it.
Rates are as dated in each lender's post, 15 to 29 October 2026. RBI raised the repo rate to 5.50% on 7 October, and the next decision is on 4 December, so every number below can move.
The best bank for a home loan in Bangalore: what lenders publish
| Lender | Lowest rate | Published range | Processing fee | Rates checked |
|---|---|---|---|---|
| LIC Housing Finance | 7.15% (score 825 and above, up to ₹50 lakh) | 7.15% to 11.00% on loans signed July to September 2026 | 0.25%, capped at ₹15,000, plus GST | 22 October |
| Bank of Baroda | 7.40% | 7.40% to 9.15% | Takeover: flat ₹8,500 plus GST. Fresh loan: not in the table I read | 29 October |
| Union Bank | 7.40% (score 825 and above) | 7.40% to 9.60% | 0.50%, capped at ₹15,000, plus GST | 28 October |
| SBI | 7.50% | About 7.50% to 8.80% (my estimate; SBI doesn't publish slabs) | 0.35%, capped at ₹15,000, plus GST | 15 October |
| Canara Bank | 7.55% (up to ₹50 lakh) | 7.55% to 10.25% | 0.50%, ₹1,500 to ₹10,000, plus GST. Waived to 31 December | 24 October |
| HDFC Bank | 8.00% | 8.00% to 13.45% | Up to 0.50% or ₹4,000, whichever is higher, plus taxes | 20 October |
| Axis Bank | 8.00% | 8.00% to 9.10% | Up to 1% or ₹10,000, whichever is higher, plus GST | 26 October |
| ICICI Bank | 8.75% | 8.75% to 10.05% | 0.50% plus an admin fee of 0.25% or ₹5,000, whichever is lower, plus taxes | 21 October |
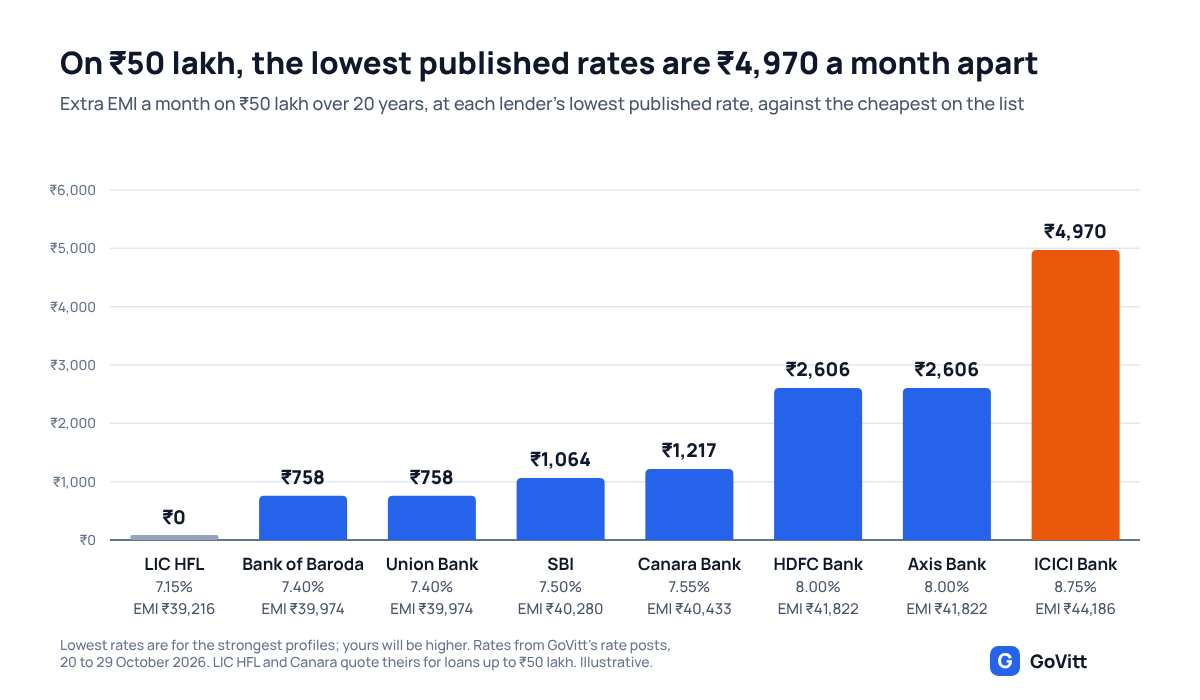
Read it as a price list, not an approval list. On ₹50 lakh the EMI at ICICI's 8.75% is ₹44,186 and at LIC's 7.15% it is ₹39,216. That is ₹4,970 a month, ₹59,640 a year. But the floor is for the best profile. The gap between you and the floor depends on your score, and the minimum CIBIL post shows what a slab costs. For the live comparison across 50+ banks, use the rates page.
Best home loan rates in Bangalore: the fee is the other half
| Lender | Fee on ₹50 lakh, with GST | Capped? |
|---|---|---|
| Canara Bank | ₹0 (₹11,800 without the waiver) | Waived to 31 December |
| LIC Housing Finance | ₹14,750 | Yes, at ₹15,000 |
| SBI | ₹17,700 | Yes, at ₹15,000 |
| Union Bank | ₹17,700 | Yes, at ₹15,000 |
| HDFC Bank | Up to ₹29,500 | No |
| ICICI Bank | ₹35,400 with admin fee | No |
| Axis Bank | Up to ₹59,000 | No |
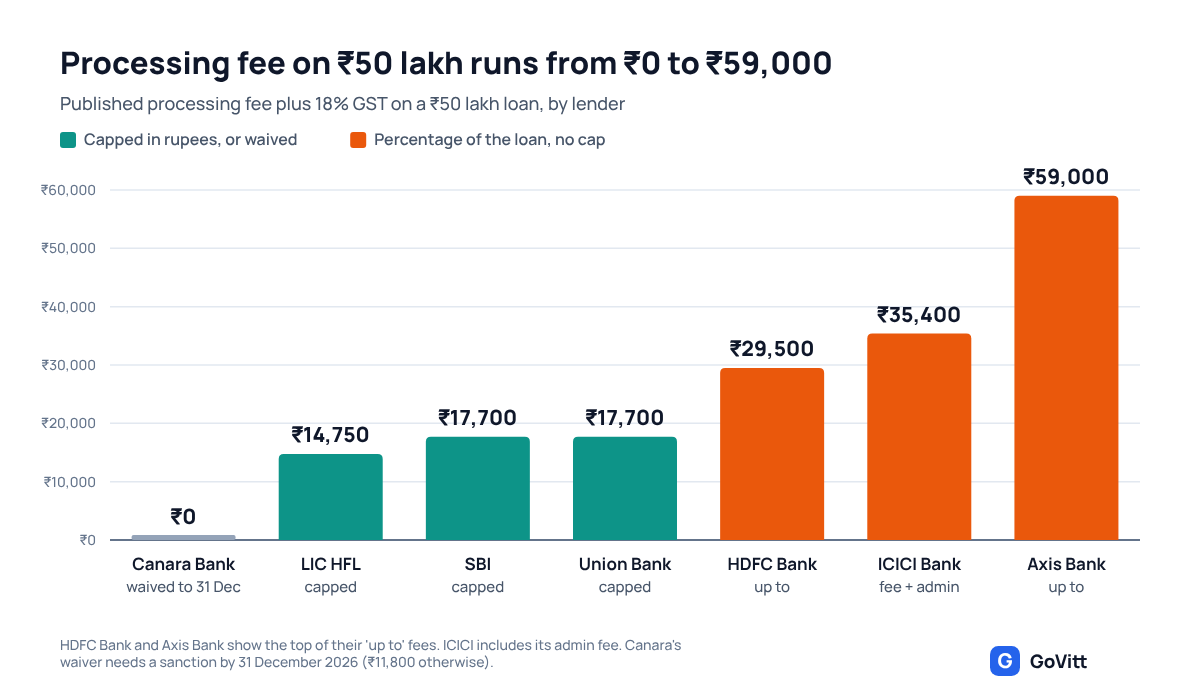
A percentage fee grows with the loan. A capped one does not. On a ₹1 crore loan, the capped lenders charge what they charge on ₹50 lakh, and the uncapped ones charge double. Two more points:
- Fees are negotiable at some lenders, and "up to" means up to. HDFC Bank's fee is up to 0.50%, and what you pay depends on your file. Ask for the fee in writing before you pay a token amount.
- Rate beats fee over a long hold, and fee beats rate over a short one. If you expect to prepay or transfer within two or three years, give the fee more weight.
Which lender to start with for your situation
| Your situation | Start with | Why | Ask first |
|---|---|---|---|
| Salaried, score 750 and above, A-khata flat in a bank-approved project | The lowest published floors above, then HDFC Bank and Axis Bank | This is the file every lender is built for, so price and fees decide | The rate at your score and the fee, both in writing |
| Salaried, score below 750 | Each lender's slab table in its rate post | Rates can move by 1% or more across slabs, and the order of lenders can change | Which slab you fall in, and whether a higher rate is offered at once |
| Resale flat on a B-khata | Not a bank yet. Fix or convert the khata first, or ask housing finance companies and NBFCs | Most banks, and almost all public sector banks, won't lend on it. Others may, at higher rates and lower loan to value | The written rate, the loan to value, and what happens if you convert |
| Flat under construction | Lenders that have already approved the project | The legal check on the title is done, so it moves faster. A single unknown lender is a reason to dig | The builder's list of approving banks |
| Already have a loan in Bengaluru | Your own lender first, then a transfer | A repricing is cheaper than a transfer. See the BT page | The new rate and the fee, in writing |
I wrote "start with", not "go to". The only way to know a lender's appetite for your file is to ask it, and asking five at once leaves five enquiries on your report.
The Bengaluru paperwork that trips people up
| Paper | Where you get it | What goes wrong |
|---|---|---|
| Khata certificate and extract | The Greater Bengaluru Authority. Check the e-khata on the e-Aasthi portal | A B-khata, an e-khata that is still a draft, or one in the seller's old name. Getting an e-khata does not turn a B into an A |
| Encumbrance certificate (EC) | Kaveri 2.0, the registration department's portal | An old mortgage still showing because the release deed was never registered |
| Approved plan and occupancy certificate | The builder, or the authority | A flat built outside the sanctioned plan, or no occupancy certificate at possession. Without it, khata, utility connections, resale and final loan payments can be affected |
| RERA registration | rera.karnataka.gov.in | An unregistered project, or a completion date that has already passed |
| Sale deed and property tax receipts | The seller | Names or areas that don't match the khata |
| MODT | The sub-registrar, registered by your lender | About 0.6% of the loan, paid by you: ₹30,000 on ₹50 lakh |
The khata is the one that decides most files. My resale flat post covers A against B, the conversion rules and what to check before you pay a token. For a builder flat, the builder checklist covers RERA, approvals and the occupancy certificate. I covered both in earlier posts, and I have not re-checked the authority's rules for this one.
What a home loan in Bengaluru costs beyond the rate
- Processing fee: ₹0 to ₹59,000 on ₹50 lakh, from the table above.
- Legal and valuation charges: at actuals, and not published as a number by the lenders I read.
- MODT: 0.5% stamp duty plus about 0.1% registration on the loan, so ₹30,000 on ₹50 lakh. The SBI post has the Bengaluru example.
- Stamp duty and registration on the purchase: in my ₹90 lakh builder example it came to about 7.6% of the agreement value, ₹7.45 lakh. GST of 5% applies on under-construction flats above ₹45 lakh.
- Pre-EMI, if the flat is under construction: interest on what has been paid out so far, before the full EMI starts. The festive season post shows the upfront cash for a ₹1 crore flat.
For the EMI itself, use the EMI calculator, and for how much a bank will lend on your income, see the eligibility post.
Already have a loan in Bengaluru?
If your rate is 0.75% or more above what the table shows for your profile, a switch can pay back within two years. Check the best banks for a balance transfer and the BT charges, because in Karnataka a switch carries its own MODT.
What I'd do this week
- Check the khata first. Ask the seller for the final e-khata, check whether it is A or B, and compare names and areas with the sale deed.
- Pull the EC. It shows any old mortgage still on the property.
- Find your score. The slab, not the floor, sets your rate.
- Ask the builder for the list of banks that have approved the project.
- Get two or three written quotes with the rate, the fee, and the MODT line.
- Make the token refundable if the bank declines the loan on legal or technical grounds.
- Pick on the total, not on the headline rate.
FAQ
Which is the best bank for a home loan in Bangalore? There isn't one for everybody. For a clean A-khata flat, the lowest published rates in my October posts were LIC Housing Finance at 7.15%, Bank of Baroda and Union Bank at 7.40%, SBI at 7.50% and Canara Bank at 7.55%, for the strongest profiles. Your own rate depends on your score and your property. Get two or three written quotes.
Where can I find a home loan near me in Bangalore? Every major lender has branches across the city. One Karnataka property-services guide says banks keep your original papers at a central processing centre, not at the branch. The branch matters for visits and questions. The decision rests on your profile and your property. You can also apply online or through an advisor.
What does a home loan advisor in Bangalore do, and what does it cost? An advisor compares lenders for your profile and property, and files and follows the application. GoVitt works with 50+ lenders and charges you 0% commission. I run GoVitt, so weigh what I say accordingly, and check any advisor's quote against the lender's own page.
Can I get a home loan on a B-khata property in Bangalore? Most banks, and almost all public sector banks, won't. Some housing finance companies and NBFCs may, at higher rates and lower loan to value. If the B-khata is eligible for conversion, that is usually the cleaner route. My resale flat post has the details.
What does a home loan in Karnataka cost beyond the interest rate? A processing fee (₹0 to ₹59,000 on ₹50 lakh in my table), legal and valuation charges at actuals, and MODT of about 0.6% of the loan, which is ₹30,000 on ₹50 lakh. On the purchase itself there is stamp duty and registration, and GST on an under-construction flat.
Not sure which lender fits your flat? Talk to an advisor on WhatsApp with the area, the khata type, your income and your score. GoVitt compares 50+ banks and charges you 0% commission.
Rates and fees are as published on each lender's page on the dates in the table, via GoVitt's rate posts. Lowest rates apply to the strongest profiles, and LIC Housing Finance and Canara quote theirs for loans up to ₹50 lakh. Fees include 18% GST; HDFC Bank and Axis Bank show the top of their "up to" fees. EMIs use the standard method and are rounded to the nearest rupee, on ₹50 lakh over 20 years. MODT is 0.5% stamp duty plus about 0.1% registration on the loan, as reported in Karnataka guides. Khata, conversion and approval rules are as reported in GoVitt's earlier posts and may have changed. This is not legal advice. Check your sanction letter and ask for every figure in writing.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.