
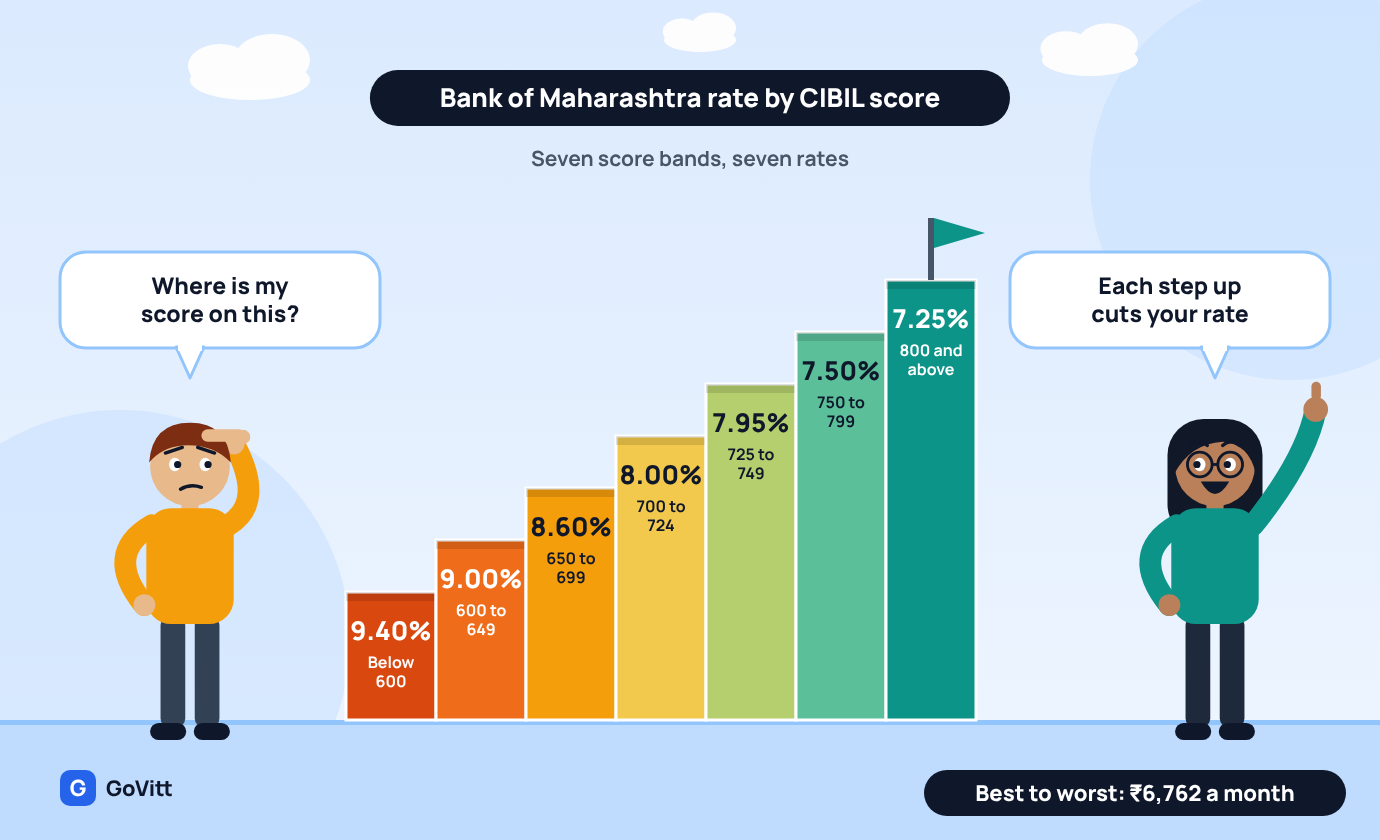
The Bank of Maharashtra home loan interest rate runs from 7.25% to 9.40% for salaried borrowers and 7.35% to 9.90% for everyone else. That is the bank's RLLR of 8.30% plus a spread that depends on your CIBIL score, as printed on its own retail interest rates page. On ₹50 lakh over 20 years the EMI goes from ₹39,519 at the bottom to ₹46,281 at the top, a gap of ₹6,762 a month.
One warning before the numbers. That page shows no effective date. A September copy of the same grid showed RLLR 8.05% and a floor of 7.00%, and every slab today is exactly 0.25% higher. That is the size of RBI's 7 October hike, which took the repo rate to 5.50%. But one aggregator says it still read the old 7.00% floor on 29 October, so the change may be more recent than 7 October. The bank states no date. Ask for your rate in your sanction letter.
Below: your rate by CIBIL score, the concessions and where the bank's pages disagree, every fee, how a transfer into Bank of Maharashtra works out, and whether to move out.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
Bank of Maharashtra home loan rates at a glance (checked 31 October 2026)
| Item | What I found | |
|---|---|---|
| Benchmark | RLLR 8.30% (retail interest rates page, no effective date printed) | Salaried rate range |
| 7.25% (score 800 and above) to 9.40% (below 600) | Non-salaried rate range | 7.35% to 9.90% |
| Headline rate on the home loan page | 7.25% | Government salaried (gross salary ₹50,000 or more, score 700 or more, not through a DSA) |
| RLLR minus 0.90%, which is 7.40% | Maha Super Flexi Housing Loan | 0.25% above the Super Housing rate |
| Processing fee | 0.25% plus GST, which is ₹14,750 on ₹50 lakh | Prepayment, pre-closure or part payment |
| None | Tenure | Up to 30 years, or until age 75, whichever is earlier |
Your rate by CIBIL score
Bank of Maharashtra prices a floating rate as RLLR plus a spread, and the spread comes from your credit score and whether you're salaried. This is the grid from its own page. EMIs are for ₹50 lakh over 20 years.
| CIBIL score | Spread over RLLR (salaried) | Salaried rate | Salaried EMI | More than the 800+ EMI | Non-salaried rate | Non-salaried EMI |
|---|---|---|---|---|---|---|
| 800 and above | Minus 1.05% | 7.25% | ₹39,519 | Nothing | 7.35% | ₹39,822 |
| 750 to 799 | Minus 0.80% | 7.50% | ₹40,280 | ₹761 | 7.60% | ₹40,586 |
| 725 to 749 | Minus 0.35% | 7.95% | ₹41,667 | ₹2,148 | 8.05% | ₹41,978 |
| 700 to 724 | Minus 0.30% | 8.00% | ₹41,822 | ₹2,303 | 8.20% | ₹42,446 |
| 650 to 699 | Plus 0.30% | 8.60% | ₹43,708 | ₹4,189 | 8.80% | ₹44,345 |
| 600 to 649 | Plus 0.70% | 9.00% | ₹44,986 | ₹5,467 | 9.20% | ₹45,631 |
| Below 600 | Plus 1.10% | 9.40% | ₹46,281 | ₹6,762 | 9.90% | ₹47,920 |
For no credit history (a score of -1 to 5), the page shows 7.95% for salaried borrowers (₹41,667) and 8.15% for the rest (₹42,290). That is ₹2,148 a month more than the best band.
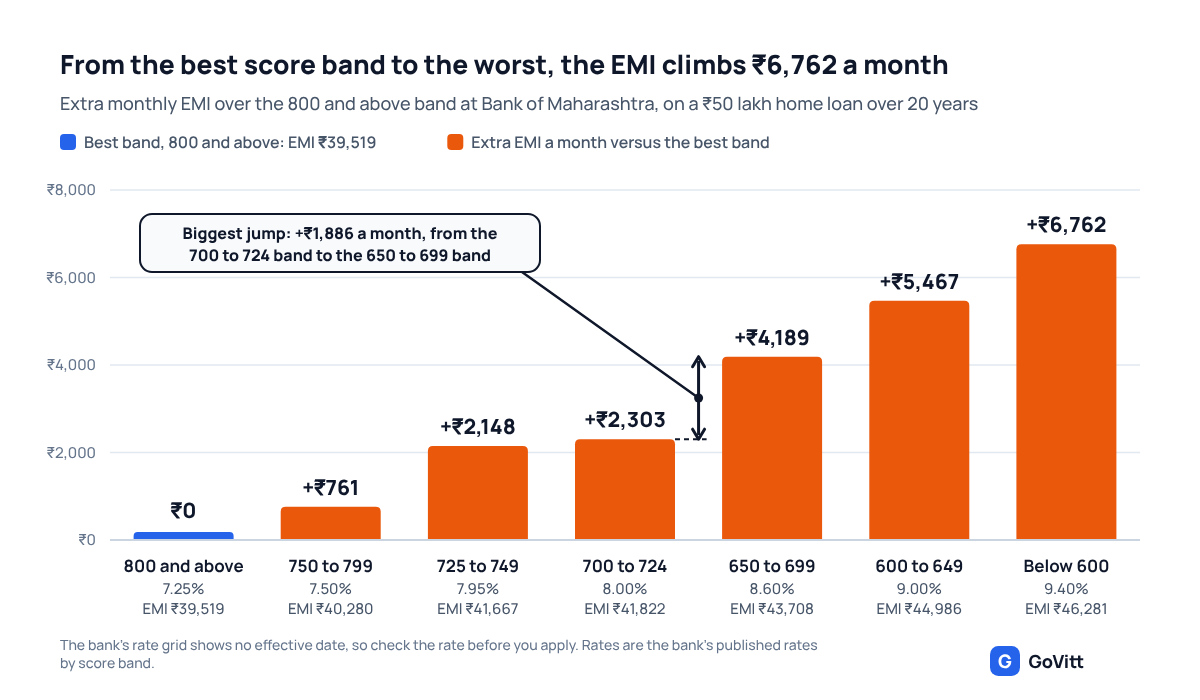
Two things stand out:
- The cliff is at 700. From the 700 to 724 band to the 650 to 699 band the rate jumps 0.60% and the EMI rises ₹1,886 a month. The step between 725 to 749 and 700 to 724 is only 0.05%, which is ₹155.
- Best to worst is ₹6,762 a month. From 800 and above to below 600 the EMI rises by that much, or ₹16.23 lakh over 20 years. How much a score band moves your rate across lenders is in RBI moved your home loan rate by 0.25%. Your CIBIL score can move it by 1.80%, and why two borrowers at the same bank pay different rates is in why your home loan rate is higher than what the bank advertises.
As a cross-check, the home loan page's own example is ₹50 lakh at 7.25% over 15 years, which it puts at about ₹45,643. My EMI formula gives the same ₹45,643.
Why you'll see other numbers on other sites
Other sites carry other numbers. Here is what I found and how I sorted it.
- 7.00% as the starting rate. MoneyKarma's page shows 7.00% to 9.65% and says it read the bank's rate page on 29 October. The September copy shows the same floor. That is RLLR 8.05% minus 1.05%. Today's page has RLLR 8.30% minus the same 1.05%, which is 7.25%. The difference is ₹754 a month on ₹50 lakh. If MoneyKarma's read was accurate, the bank's page changed after 29 October, not on 7 October.
- A slab table from 8.10% to 10.15%. Urban Money's page, dated 29 October, headlines "7.25% onwards" but lists 8.10% for a score of 800 and above. It also gives two RLLR values, 9.05% as of March 2025 and 8.05% with no date, and it contradicts itself on the women's concession. I don't use it.
- A processing fee of "up to 1%". That is Urban Money's figure. The bank's own pages say 0.25%.
I use only the bank's own pages and flag where they disagree with each other.
Concessions and special schemes: what the pages say
| Scheme | What Bank of Maharashtra's pages say | What it's worth on ₹50 lakh |
|---|---|---|
| Women borrowers | Rate page: 0.05% extra concession, only in slabs below a score of 725, floor 7.25%. Home loan page: 0.05% concession for women and defence personnel, no score limit mentioned | ₹158 a month, or ₹0.38 lakh over 20 years |
| Government salaried | RLLR minus 0.90% (7.40%) for gross salary of ₹50,000 or more, score 700 or more, not through a DSA | ₹1,848 a month less than the 700 to 724 rate, ₹1,693 less than 725 to 749, ₹306 less than 750 to 799. Dearer than the 800+ rate |
| Maha Super Flexi Housing Loan | 0.25% above the Super Housing rate | ₹761 a month more |
| Green building | 0.10% concession, floor of 7.25% | ₹306 to ₹311 a month |
Two cautions. First, the women's wording differs between the two pages, and the rate page also says the grid is shown "including 0.05% concession for women borrower". I can't tell whether the grid above already includes it, so ask whether your rate does. The rate page lists no defence concession for housing loans at all. Second, the same rate page says no rate concession is allowed for scores of 725 and above, so I can't tell whether the green building discount reaches a strong score. Get both in writing.
If you're a government employee with a score of 750 or more, the 7.40% rate is a small step down from 7.50%, not a big one. It helps most if your score sits between 700 and 749.
Top-up loans: two pages, two answers
For existing home loan customers, the rate page prices a top-up (Maha Bank Top Up Loan) as a premium over your housing rate:
| CIBIL score | Premium over the Super Housing rate |
|---|---|
| 800 and above | 0.50% |
| 750 to 799 | 0.75% |
| 681 to 749, or no history | 1.00% |
| 680 and below | 3.00% |
The home loan page says something different: a top-up at 0.20% above the home loan rate, "currently". On a ₹10 lakh top-up over 10 years, a borrower at 800 and above would pay ₹12,001 a month at 7.75% (rate page) or ₹11,844 at 7.45% (home loan page). A 750 to 799 borrower on the rate page's premium pays 8.25% and ₹12,265. That is a ₹157 a month question for a strong borrower and more for a weak one, so ask which page the bank follows. I found no top-up processing fee. The rules on top-ups, including the tax treatment, are in home loan top-up: interest rate, eligibility and the tax rule most people get wrong.
How Bank of Maharashtra compares at your score
EMI on ₹50 lakh over 20 years, salaried, at the same score. PNB's rates are festive campaign rates for loans above ₹30 lakh up to 80% of the property value, running to 31 December 2026. LIC Housing Finance's are for loans up to ₹50 lakh, as read on 22 October.
| CIBIL score | Bank of Maharashtra | PNB | LIC Housing Finance |
|---|---|---|---|
| 800 and above | 7.25% (₹39,519) | 7.45% | 7.25% (800 to 824), 7.15% (825 and above) |
| 750 to 799 | 7.50% (₹40,280) | 7.50% | 7.45% (750 to 774), 7.35% (775 to 799) |
| 725 to 749 | 7.95% (₹41,667) | 8.05% (700 to 749) | 7.65% |
| 700 to 724 | 8.00% (₹41,822) | 8.05% (700 to 749) | 7.95% |
| 650 to 699 | 8.60% (₹43,708) | 9.25% (600 to 699) | 8.75% (600 to 699) |
| 600 to 649 | 9.00% (₹44,986) | 9.25% (600 to 699) | 8.75% (600 to 699) |
| Below 600 | 9.40% (₹46,281) | Not in the grid I read | 9.55% |
What the grid says:
- At 800 and above, Bank of Maharashtra beats PNB by ₹608 a month and ties LIC's 800 to 824 band. LIC's 825 and above rate of 7.15% is ₹303 a month lower.
- At 750 to 799, it ties PNB. LIC is slightly cheaper in this range.
- At 725 to 749, LIC wins at 7.65%, ₹928 a month below Bank of Maharashtra.
- At 650 to 699, Bank of Maharashtra wins. PNB's 600 to 699 rate costs ₹2,085 a month more, and LIC's costs ₹478 more.
- At 600 to 649, LIC wins at 8.75%, ₹800 a month below Bank of Maharashtra's 9.00%, while PNB is ₹807 above it.
- Below 600, Bank of Maharashtra is ₹489 a month below LIC.
LIC Housing Finance had announced no change after RBI's October hike when I last checked on 22 October, so its numbers may have moved since.
Against the lowest rates other lenders publish, Bank of Maharashtra's 7.25% is ₹455 a month below Union Bank's and Bank of Baroda's 7.40%, ₹608 below PNB's 7.45%, ₹761 below SBI's 7.50% and ₹2,303 below HDFC Bank's 8.00%, which is ₹5.53 lakh over 20 years. Those are best cases for strong profiles. The detail is in Bank of Baroda home loan interest rate (October 2026), Union Bank home loan interest rate (October 2026), LIC Housing Finance home loan interest rate, SBI home loan interest rate (October 2026), HDFC home loan rates at a glance, Axis Bank home loan interest rate (October 2026) and Canara Bank home loan interest rate (October 2026). See today's rates across 50+ lenders on our rate comparison page.
Bank of Maharashtra home loan fees and charges
From the bank's own pages. Neither fee page carries an up to date waiver, so I assume the standard fee applies.
| Fee | Amount | On ₹50 lakh |
|---|---|---|
| Processing fee, Maha Super Housing Loan | 0.25% of the loan plus GST (no cap shown on the page) | ₹14,750 with GST |
| Processing fee, Maha Super Flexi Housing Loan | 0.25%, subject to a maximum of ₹25,000 | ₹14,750 with GST |
| Processing fee, Green Housing Loan | An aggregator's copy of the rate page (BankCreds, 16 September) says nil. I couldn't find it on today's pages | Ask for the number |
| Prepayment, pre-closure, part payment | None, according to the FAQ on the home loan page | ₹0 |
| Other charges | "As per bank terms", no figures given | Ask for the number |
The waivers are stale. The Super Housing page shows a processing fee waiver "upto 31.12.2025", and the Flexi page shows one "currently waived up to 30.09.2024". Both dates have passed, and neither page says whether a newer waiver exists. Ask before you pay.
The fee scales with the loan, plus GST:
| Loan | Processing fee at 0.25% plus GST |
|---|---|
| ₹30 lakh | ₹8,850 |
| ₹50 lakh | ₹14,750 |
| ₹75 lakh | ₹22,125 |
| ₹1 crore | ₹29,500 |
The ₹25,000 cap on the Flexi page only bites above ₹1 crore, because 0.25% of ₹1 crore is exactly ₹25,000. On ₹50 lakh the fee is ₹14,750. At SBI the fee on the same loan is ₹17,700 and at HDFC Bank it can run to ₹29,500. Everything else you pay on a transfer is the same whichever lender you pick: legal and valuation, MODT stamp duty (0.5% in Karnataka), registration and small charges, which come to ₹36,000 to ₹47,000 on ₹50 lakh. Every line is in home loan balance transfer charges.
Balance transfer to Bank of Maharashtra
The home loan page lists a takeover (refinance) route. What it publishes:
- Documents: the outstanding loan statement, the last 12 months of loan account statements and a document acknowledgement receipt.
- Rate: no separate takeover rate. Expect the grid above, so your score band decides it.
- Fee: none listed separately. Expect the 0.25% plus GST above.
- Prepayment: none, so leaving Bank of Maharashtra later costs you nothing in fees.
- Tenure: up to 30 years or age 75, whichever is earlier.
- Eligibility: salaried borrowers with a permanent job and at least one year of continuous service, self-employed professionals and businessmen. NRIs need a regular job abroad with a valid contract or work permit for at least two years.
- What the page doesn't give: a minimum income, a maximum loan or the loan to value ratio.
The steps, and where they stall, are in home loan transfer process, step by step. Where Bank of Maharashtra sits against the rest on a transfer is in best banks for home loan balance transfer in 2026.
Moving a loan into Bank of Maharashtra: the numbers
A worked example. Say you have:
- ₹50 lakh outstanding
- 20 years left
- A current rate of 8.75%, so an EMI of ₹44,186
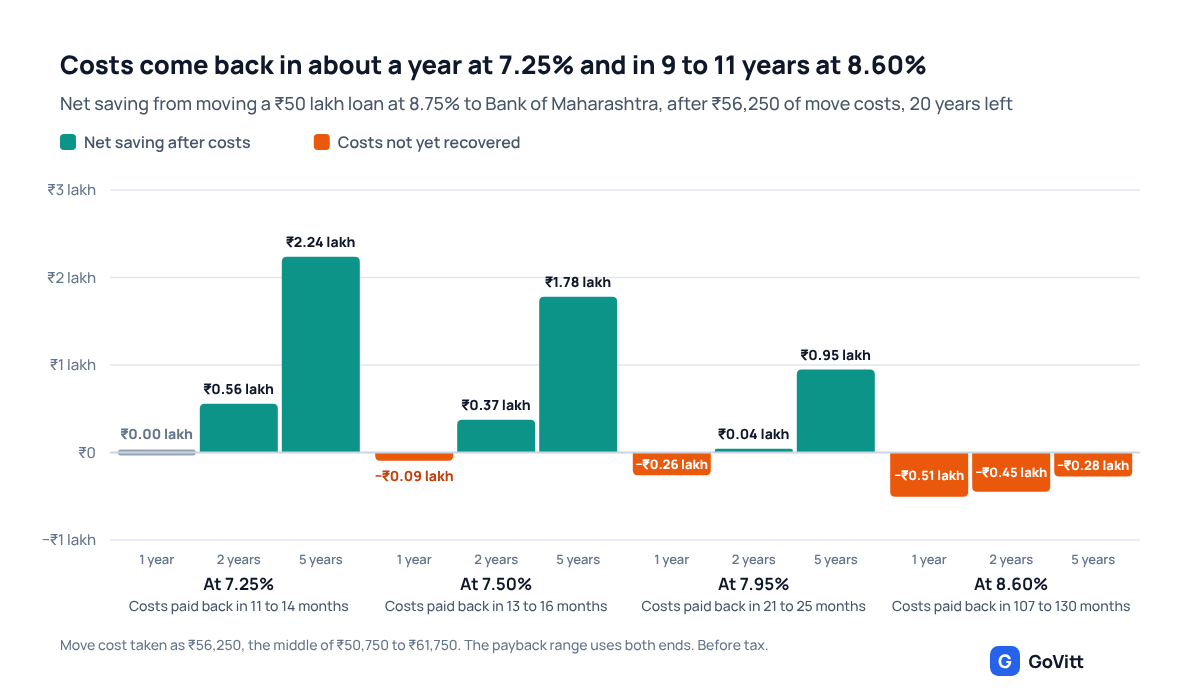
The fee of ₹14,750 plus the shared Bengaluru charges of ₹36,000 to ₹47,000 makes the move cost ₹50,750 to ₹61,750. Here is what you save, by the rate you land at:
| Where you land | New EMI | Saving a month | Costs paid back in | Net saving over 5 years | Net saving over 20 years |
|---|---|---|---|---|---|
| 7.25% | ₹39,519 | ₹4,667 | 11 to 14 months | ₹2.18 to ₹2.29 lakh | ₹10.58 to ₹10.69 lakh |
| 7.50% | ₹40,280 | ₹3,906 | 13 to 16 months | ₹1.73 to ₹1.84 lakh | ₹8.76 to ₹8.87 lakh |
| 7.95% | ₹41,667 | ₹2,519 | 21 to 25 months | ₹0.89 to ₹1.00 lakh | ₹5.43 to ₹5.54 lakh |
| 8.60% | ₹43,708 | ₹478 | 107 to 130 months | A loss of ₹0.22 to ₹0.33 lakh | ₹0.53 to ₹0.64 lakh |
What this tells you:
- Your score band decides everything. At 7.25% the move pays for itself in 11 to 14 months. At 8.60%, the rate for a score of 650 to 699, it takes 107 to 130 months and loses money over five years.
- The fee isn't the problem. Bank of Maharashtra's ₹14,750 is lower than SBI's ₹17,700 here. The shared ₹36,000 to ₹47,000 is the same wherever you go.
- If your slab's rate is close to what you pay now, skip it. Moving from 8.75% to 8.60% saves ₹478 a month. That doesn't cover the costs inside five years.
The full process is on our home loan balance transfer page.
Already with Bank of Maharashtra? Whether to switch
If your loan follows the RLLR, a rise in the RLLR reaches you at your next reset: 0.25% is ₹767 a month on ₹50 lakh at 7.50%. Your spread is yours. Under RBI's rules for repo-linked loans, it stays put unless your credit assessment changes substantially. If you took the loan at a weak score and your score is much better now, ask the bank for a lower spread. Going from the 650 to 699 band to the 750 to 799 band is worth ₹3,428 a month, or ₹8.23 lakh over 20 years. I couldn't find a published fee for repricing, so get the number in writing.
If the bank says no, here is what moving out is worth for ₹50 lakh with 20 years left, to a lender at 7.50% with costs of ₹53,700 to ₹76,500 (SBI's fee of ₹17,700 plus ₹36,000 at the low end, HDFC Bank's ₹29,500 plus ₹47,000 at the high end):
| Your Bank of Maharashtra rate | Saving a month | Costs paid back in | Net saving over 20 years |
|---|---|---|---|
| 9.40% | ₹6,001 | 9 to 13 months | ₹13.64 to ₹13.87 lakh |
| 9.00% | ₹4,706 | 12 to 17 months | ₹10.53 to ₹10.76 lakh |
| 8.60% | ₹3,428 | 16 to 23 months | ₹7.46 to ₹7.69 lakh |
| 8.00% | ₹1,542 | 35 to 50 months | ₹2.94 to ₹3.16 lakh |
If you're at 9.40% or 9.00%, a switch pays back inside a year and a half even at the high end. At 8.00% the wait is 35 to 50 months. The logic is in rates just went up: does switching your home loan still make sense?
Who Bank of Maharashtra suits, and who should look elsewhere
It can make sense if you:
- Have a score of 750 or more, where 7.25% to 7.50% matches or beats PNB and Union Bank and equals SBI's lowest published rate
- Are a government employee with a gross salary of ₹50,000 or more and a score of 700 to 749, where the 7.40% rate helps most
- Have a score of 650 to 699, where it was cheaper than both PNB and LIC in the grid above
- Expect to prepay, because there's no prepayment charge
Look elsewhere first if you:
- Score 725 to 749 or 600 to 649. LIC's published rates were lower in both bands, by ₹928 and ₹800 a month
- Are self-employed or a business owner. Your rate is 0.10% to 0.50% higher than a salaried borrower's in the same band
- Want a firm number before you apply. The grid is public, but the bank prints no date on it
Compare before you sign
Your rate depends on a score band, and every enquiry leaves a mark on your credit report. So don't apply to five banks to find out. Compare rates from 50+ banks and see what your profile qualifies for. GoVitt charges you 0% commission.
FAQ
What is the Bank of Maharashtra home loan interest rate today? As of 31 October 2026, 7.25% to 9.40% for salaried borrowers and 7.35% to 9.90% for non-salaried borrowers, according to the bank's retail interest rates page. That is RLLR at 8.30% plus a spread by CIBIL score. The page prints no effective date, so confirm your rate in your sanction letter.
What is the BOM home loan interest rate for a CIBIL score of 750? 7.50% for a salaried borrower with a score of 750 to 799, and 7.60% for a non-salaried one. On ₹50 lakh over 20 years the EMI is ₹40,280 for the salaried rate.
Why do other websites show 7.00% for Bank of Maharashtra? That was the floor when the RLLR was 8.05%. The bank's own page now shows RLLR 8.30%, and every slab is 0.25% higher, so the floor is 7.25%. Some aggregators haven't updated.
What is the processing fee on a Bank of Maharashtra home loan? 0.25% of the loan plus GST, which is ₹14,750 on ₹50 lakh. The home loan page shows a waiver that ended on 31 December 2025, and the Flexi page shows a ₹25,000 cap and a waiver that ended on 30 September 2024. Ask whether a current waiver applies.
Is there a prepayment charge on a Bank of Maharashtra home loan? No. The bank's FAQ lists no prepayment, pre-closure or part-payment charges.
Can I transfer my home loan to Bank of Maharashtra? Yes. The home loan page lists a takeover route with its documents. It gives no separate takeover rate, so expect the same grid as a new loan and a fee of 0.25% plus GST.
Not sure Bank of Maharashtra is your best rate? Compare rates from 50+ banks and see what your profile qualifies for. GoVitt charges you 0% commission.
Rates and fees as of 31 October 2026, from Bank of Maharashtra's retail interest rates page and home loan pages, which print no effective date. PNB's rates are as of 25 October 2026 (page date) and LIC Housing Finance's as of 22 October 2026. The September grid and the 7.00% floor come from an aggregator's copy of the bank's page. EMIs use the standard monthly reducing balance method and are rounded to the nearest rupee. The transfer examples assume a property in Bengaluru and a current rate of 8.75%. Rates change after every RBI policy decision; we will update this page after 4 December 2026.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.