
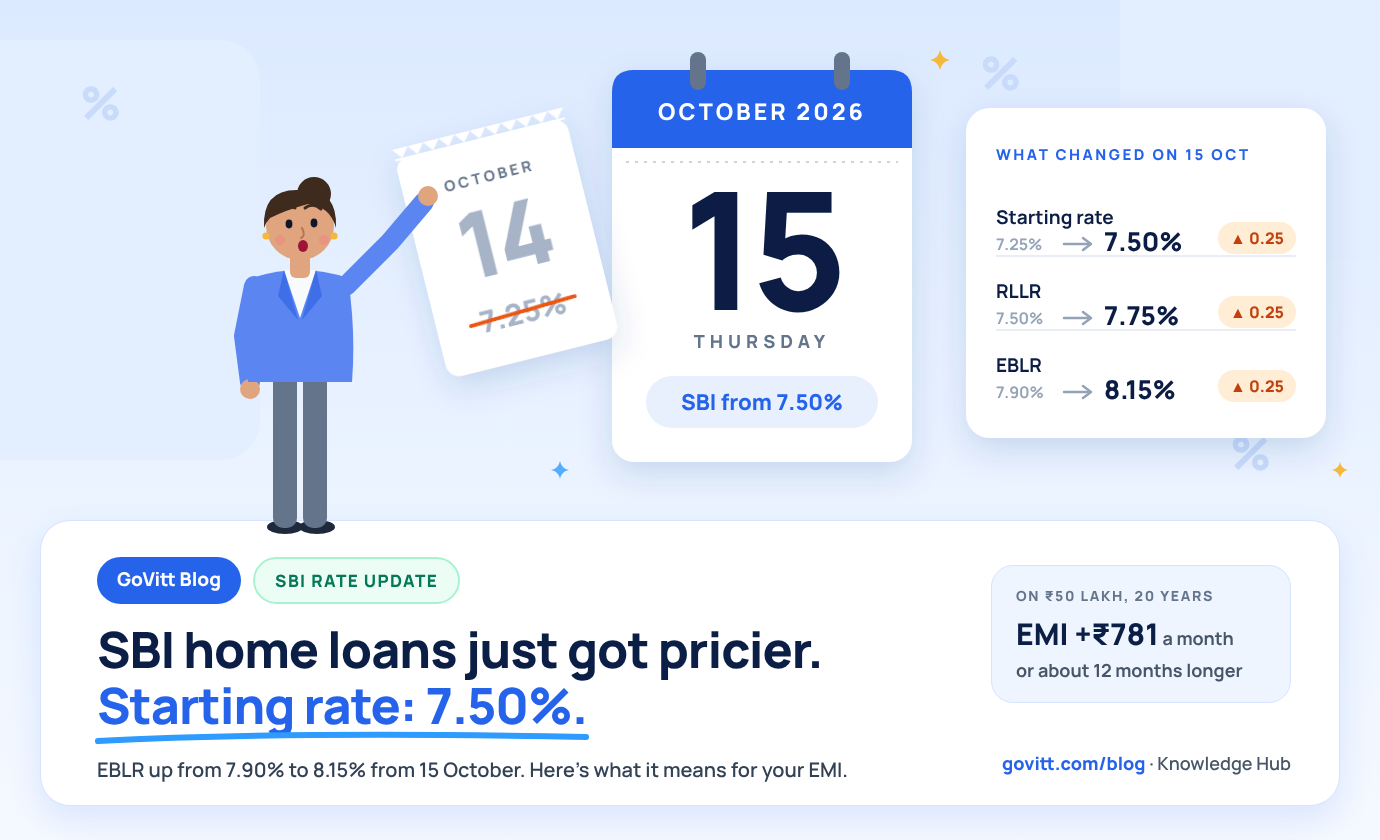
Quick answer: SBI home loan rates start at 7.50% a year from 15 October 2026, up from 7.25%. SBI raised its external benchmark lending rate (EBLR) from 7.90% to 8.15% after RBI's repo rate hike on 7 October. What you actually pay depends mostly on your credit score.
SBI's rates right now
| Rate | Before | From 15 October 2026 |
|---|---|---|
| Home loan starting rate | 7.25% | 7.50% |
| EBLR | 7.90% + CRP + BSP | 8.15% + CRP + BSP |
| RLLR | 7.50% + CRP | 7.75% + CRP |
| Likely range by credit score (our estimate) | 7.25% to 8.55% | 7.50% to 8.80% |
CRP is the credit risk premium, which SBI adds mostly based on your CIBIL score. BSP is the business strategy premium. Together they're your spread. Once your loan is sanctioned, the spread stays the same, so whenever SBI's EBLR moves, your rate moves by exactly that much.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
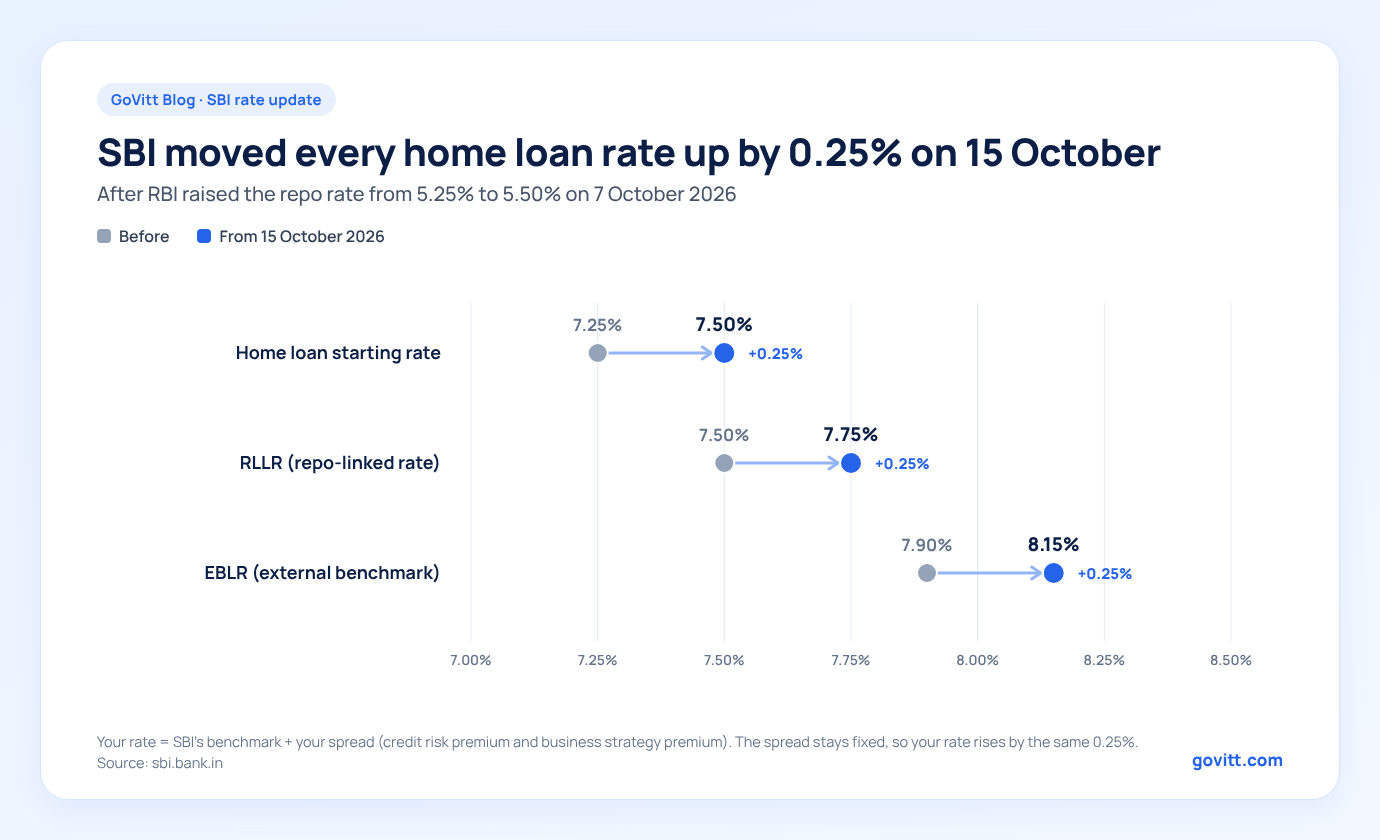
Every SBI benchmark moved by the same 0.25% as RBI's repo hike.
What you'll pay, by credit score
SBI doesn't publish its full credit score grid. Here's how it usually plays out:
- Strongest profiles: at or close to the 7.50% starting rate
- Weaker scores: up towards 8.80%
- Non-salaried borrowers with a CIBIL score below 825: 0.10% more than a salaried borrower with the same score
The only way to know your exact rate is to apply and see it on the sanction letter. Check your score before you go, so the number doesn't surprise you. If you want to see how much a credit score moves rates across lenders, this post breaks down the slabs.
EMI at SBI's current rates
On ₹50 lakh for 20 years:
| Rate | EMI | Total interest |
|---|---|---|
| 7.50% | ₹40,280 | ₹46.67 lakh |
| 7.75% | ₹41,047 | ₹48.51 lakh |
| 8.00% | ₹41,822 | ₹50.37 lakh |
| 8.25% | ₹42,603 | ₹52.25 lakh |
| 8.50% | ₹43,391 | ₹54.14 lakh |
| 8.80% | ₹44,345 | ₹56.43 lakh |
EMI per ₹1 lakh at 7.50%: ₹806 for 20 years, ₹699 for 30 years. Multiply by your loan amount in lakhs. For any other amount or tenure, use our EMI calculator.
Already have an SBI home loan?
If your loan is linked to the EBLR, your rate goes up by 0.25% at your next reset after 15 October.
Say you have ₹50 lakh left over 20 years at 8.00%. You'll now pay 8.25%. Either your EMI goes up by ₹781 a month, or SBI keeps the EMI the same and stretches your loan by about 12 months.
Stretching sounds painless. It isn't. Keeping the same EMI and extending the tenure costs about ₹4.96 lakh more in interest over the loan. Paying ₹781 more each month costs about ₹1.88 lakh.
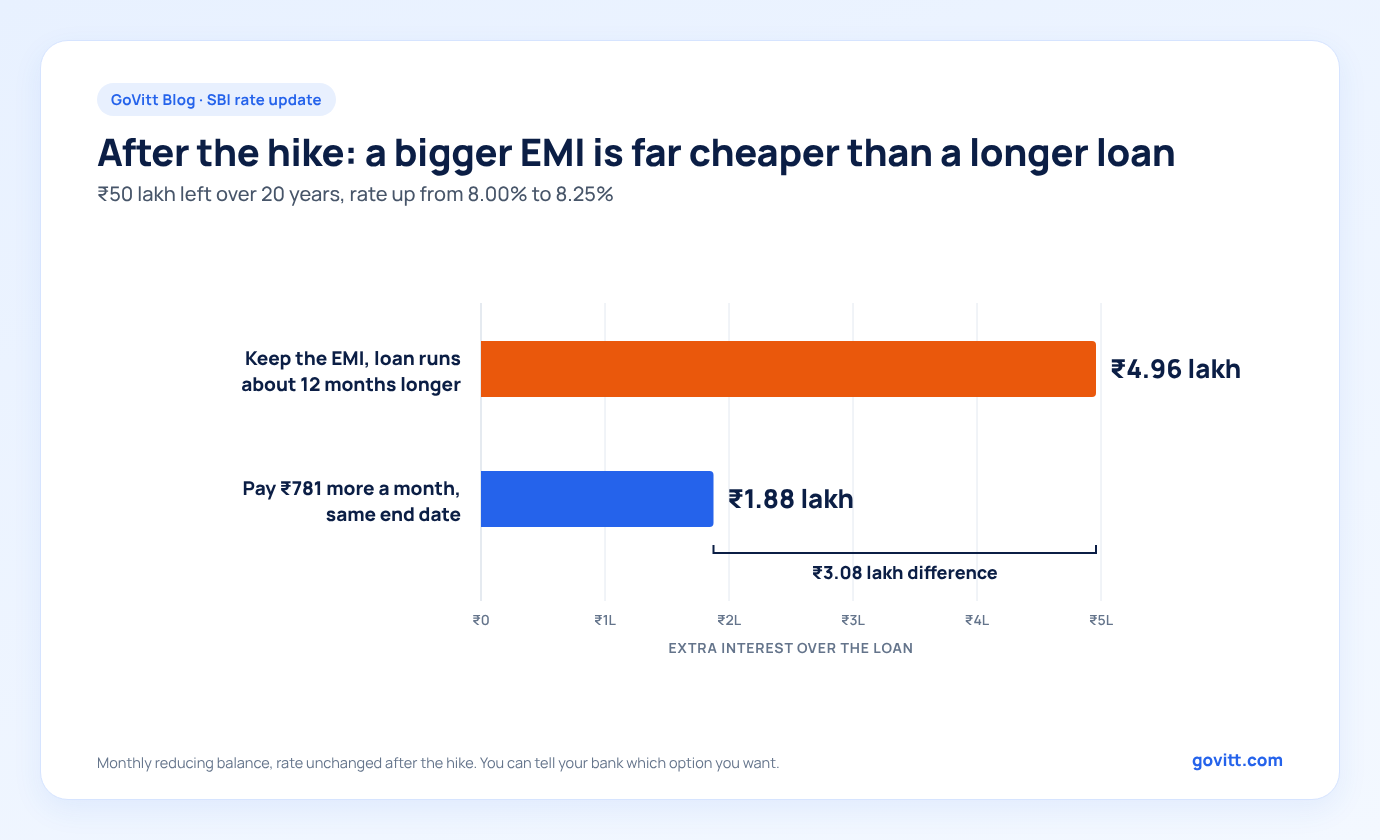
Same hike, ₹3.08 lakh apart, depending on one choice.
You're allowed to tell SBI which one you want. Here's the exact message to send.
If you're still on MCLR or the old base rate, ask SBI about moving to the repo-linked rate. SBI charges ₹5,000 plus GST for the conversion. If your current rate is well above 8%, that's usually money well spent.
SBI home loan fees and charges
| Charge | Amount |
|---|---|
| Processing fee | 0.35% for salaried, capped at ₹15,000 plus GST (₹17,700 at most) |
| Legal and valuation | Charged at actuals |
| MODT stamp duty (Karnataka) | 0.5% of the loan amount, plus about 0.1% registration |
| Prepayment or foreclosure on a floating rate loan | Nil |
| Moving from MCLR or base rate to the EBLR | ₹5,000 plus GST |
This festive season, SBI's concessions were reported on personal, car and gold loans. Home loans weren't named. Ask your branch anyway, because home loan fee waivers do come up.
SBI home loan variants
- Regular home loan: the standard one most people take
- Top-up loan: extra money on top of your existing SBI home loan
- MaxGain: an overdraft style home loan, where spare money you park in the account cuts your interest. Our take on home loan overdrafts
- Privilege: for government employees
- Shaurya: for defence personnel
- Flexipay: lower EMIs in the early years for young salaried borrowers aged 21 to 45, higher later
SBI also has its own balance transfer calculator for loans moving in from other banks.
Is SBI the right lender for you?
SBI tends to work well if you:
- Are salaried with a CIBIL score of 750 or more
- Want a large public sector bank and don't mind visiting a branch
- Will actually use MaxGain to park surplus cash
It may not be your best option if:
- Your credit score is below 700. You'll likely be at the top of SBI's range, and a lender that publishes its full grid may price you better
- You need a sanction on a tight timeline. Ask the branch upfront how long they're taking right now
How SBI compares on starting rates
| Lender | Starting rate | Who gets it |
|---|---|---|
| LIC Housing Finance | 7.15% | CIBIL 825 and above, salaried |
| Bank of Maharashtra | 7.25% | CIBIL 800 and above, salaried |
| Punjab National Bank | 7.45% | CIBIL 800 and above |
| SBI | 7.50% | Strongest profiles |
| HDFC Bank | 8.00% | Repo rate + 2.50%, strongest profiles |
| ICICI Bank | 8.75% | Standard rate, CIBIL 750 and above (7.55% on pre-approved digital loans) |
These are starting rates for the best profiles. See all 50+ lenders on our rate comparison page.
Switching to SBI from another bank
Say you're paying 8.75% on ₹50 lakh with 20 years left, and SBI sanctions you at 7.50%:
- Your EMI drops by ₹3,906 a month
- Total interest over the loan falls by about ₹9.37 lakh
- Charges for a Bengaluru property come to roughly ₹53,700 to ₹64,700 with SBI's capped processing fee (that's the fee, legal and valuation, MODT, registration and small charges)
- You earn those charges back in about 14 to 17 months
The catch: 7.50% is only for strong profiles. Get SBI's sanction letter with your actual rate before you ask your current bank for a foreclosure letter. Every charge is explained in our post on balance transfer charges, and here's the step by step transfer process.
Switching away from SBI
If SBI has you at 8.50% or more and your credit score has improved since you took the loan, ask SBI first whether it will bring your rate down. If it won't, a lender pricing you at 7.50% to 7.75% would cut your EMI by about ₹2,300 to ₹3,100 a month on ₹50 lakh with 20 years left. Run your own numbers on our Payoff & Transfer Calculator.
Want us to check your SBI loan?
WhatsApp your outstanding amount, current rate and years left to +91 70194 17854. We'll tell you what the 15 October change means for your EMI or tenure, and whether a better rate is available to you. GoVitt compares offers from 50+ banks and housing finance companies, and we don't charge you any commission.
Rates are as published by SBI on 15 October 2026. The full range by credit score is GoVitt's estimate, since SBI doesn't publish its bands. Other lenders' starting rates are as published on their websites around 12 October 2026. Your actual rate depends on your credit score, income, loan amount and property. EMI figures assume monthly reducing balance and an unchanged rate for the full tenure. Please confirm with SBI before you apply.
Questions people usually ask
What is the SBI home loan interest rate today? SBI home loan rates start at 7.50% a year from 15 October 2026. The rate you get depends mainly on your credit score, and borrowers with weaker scores can pay up to around 8.80%.
Has SBI increased its home loan interest rate after the RBI hike? Yes. SBI raised its external benchmark lending rate (EBLR) from 7.90% to 8.15%, effective 15 October 2026, after RBI raised the repo rate to 5.50% on 7 October. Existing EBLR-linked loans go up by 0.25% at their next reset.
What CIBIL score do I need for SBI's lowest home loan rate? SBI doesn't publish its credit score bands. The 7.50% starting rate goes to the strongest profiles, generally borrowers with very high scores. Non-salaried borrowers with a score below 825 pay 0.10% more than salaried borrowers.
What is SBI's home loan processing fee? 0.35% of the loan amount for salaried borrowers, capped at ₹15,000 plus GST. That's ₹17,700 at most, even on a large loan.
Can I transfer my home loan to SBI? Yes. If you're paying 8.75% on ₹50 lakh with 20 years left and SBI sanctions you at 7.50%, your EMI drops by about ₹3,906 a month. Charges for a Bengaluru property come to roughly ₹53,700 to ₹64,700, which you recover in about 14 to 17 months.
Does SBI charge for prepaying a home loan? Not on floating rate home loans taken by individuals. You can prepay part or all of the loan without a penalty.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.