
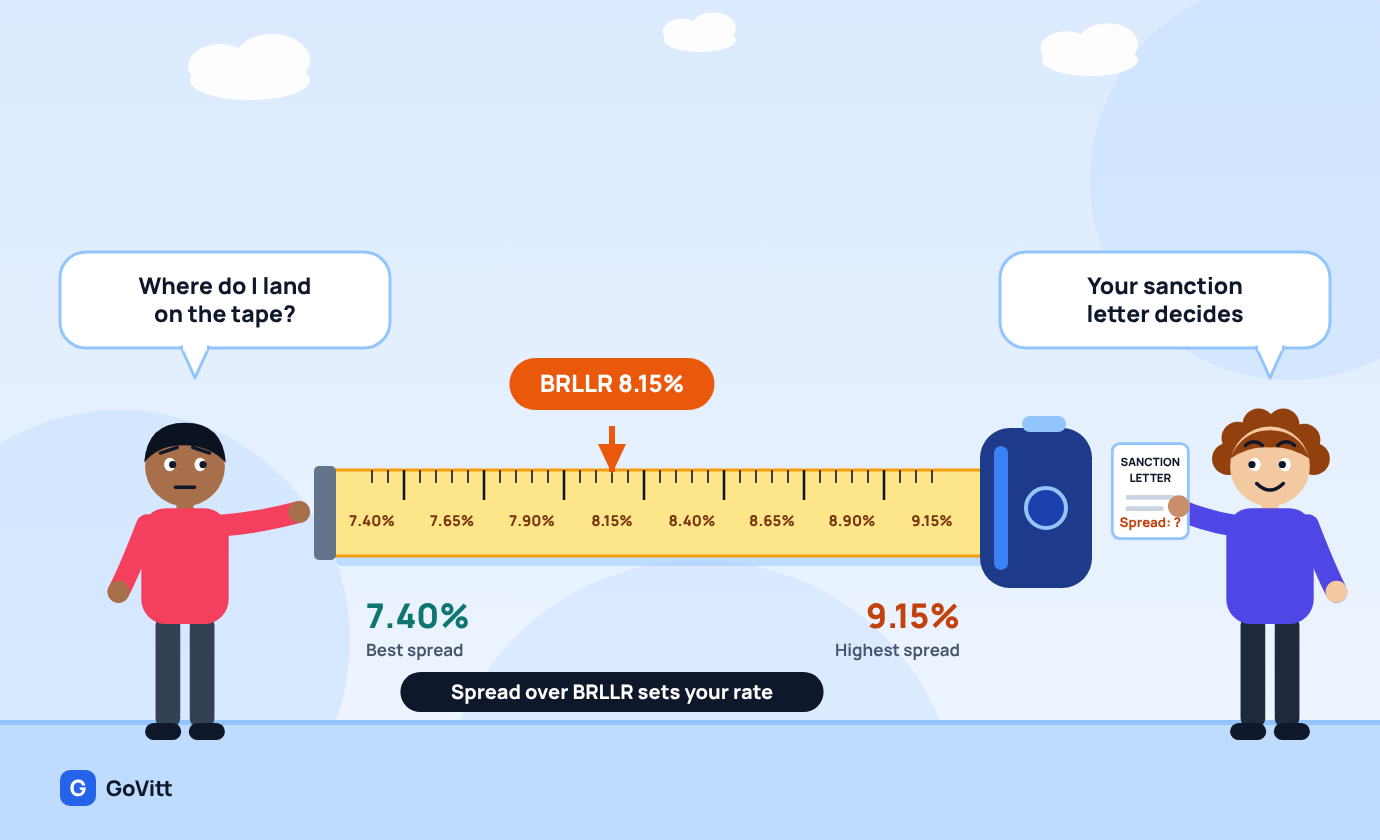
The Bank of Baroda home loan interest rate runs from about 7.40% to 9.15%. That is the bank's lending rate, the BRLLR, at 8.15%, plus a spread of minus 0.75% to plus 1.00%, as reported by MoneyKarma on 23 October 2026. On ₹50 lakh over 20 years it works out to an EMI of ₹39,974 at the bottom and ₹45,470 at the top, a gap of ₹5,496 a month.
BoB raised the BRLLR from 7.90% to 8.15% on 8 October, the day after RBI took the repo rate to 5.50%. The BRLLR is repo plus a markup of 2.65%, and the bank kept the markup. So the 0.25% rise reached every borrower whose loan follows it, which is ₹779 a month on ₹50 lakh over 20 years.
One warning before you read on. I couldn't read Bank of Baroda's own rate sheet. Its site blocks the tools I use, and the pages I could open carry no rate grid. That means no table of rates by CIBIL score here, and I won't invent one. The range comes from the BRLLR and the spread range an aggregator reports. The fees and prepayment terms come from BoB's own pages.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
Below: what the spread does to your EMI, every fee BoB lists, how a transfer into BoB works, and whether to move.
Bank of Baroda home loan at a glance (checked 29 October 2026)
| Item | What I found |
|---|---|
| BRLLR | 8.15% from 8 October 2026 (7.90% before), which is repo at 5.50% plus a markup of 2.65% |
| Spread over BRLLR | Minus 0.75% to plus 1.00% (MoneyKarma, verified 23 October 2026) |
| Rate range | 7.40% to 9.15%, my arithmetic from the two lines above |
| If you don't take credit insurance | 0.05% more (MoneyKarma) |
| Rate type | Floating, follows the BRLLR |
| Processing fee, takeover of a loan from another lender | Flat ₹8,500 plus GST, which is ₹10,030 (BoB's fee page, effective from 20 June 2019 as printed) |
| Processing fee, top-up | 0.35%, minimum ₹5,000, maximum ₹12,500, plus GST (BoB's top-up page, effective 1 April 2025) |
| Prepayment on a home loan | None. BoB's own FAQ says there are no pre-payment charges on a home loan |
Why you'll see other "lowest rates"
In October I found four different "starts at" figures for BoB: 7.15%, 7.20%, 7.40% and 7.95%. Here is how I sorted them.
- 7.15% is the BRLLR before the hike, 7.90%, minus 0.75%. That sum is out of date.
- 7.40% is the same sum after the hike. A second aggregator also shows about 7.40%. I use it.
- 7.20% appeared on a news site on 16 October. I can't explain it.
- 7.95% appeared on an aggregator's page without saying which product it covers. I can't explain that either.
Treat 7.40% as the floor and ask the bank to confirm it in writing.
What your spread does to your EMI
Your sanction letter carries one number that matters most: your spread over the BRLLR. I can't tell you which score earns which spread. I can show you what each step costs.
| Spread over BRLLR | Your rate | EMI on ₹50 lakh, 20 years | More than the best case |
|---|---|---|---|
| Minus 0.75% | 7.40% | ₹39,974 | Nothing |
| Minus 0.50% | 7.65% | ₹40,739 | ₹765 |
| Minus 0.25% | 7.90% | ₹41,511 | ₹1,537 |
| Zero | 8.15% | ₹42,290 | ₹2,316 |
| Plus 0.25% | 8.40% | ₹43,075 | ₹3,101 |
| Plus 0.50% | 8.65% | ₹43,867 | ₹3,893 |
| Plus 1.00% | 9.15% | ₹45,470 | ₹5,496 |
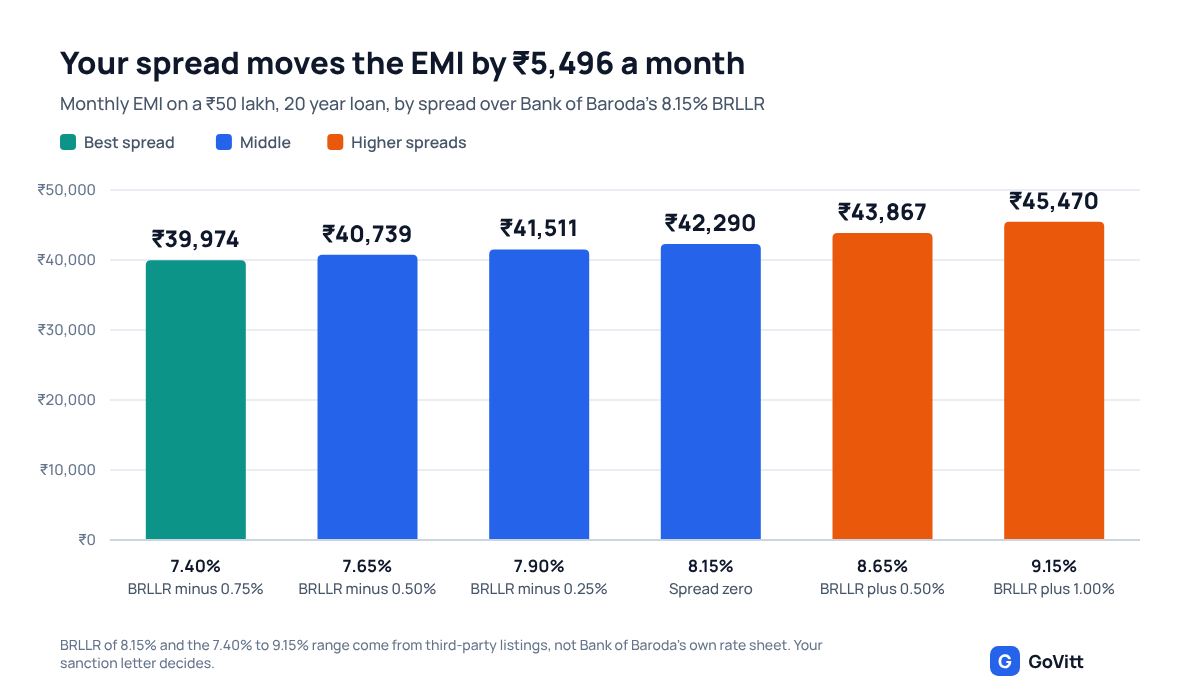
Each 0.25% step costs ₹765 to about ₹800 a month. From the best spread to the worst is ₹5,496 a month, or ₹13.19 lakh over 20 years. That is a big number to leave to chance, and it comes from your credit profile alone.
Under RBI's rules for repo-linked loans, the spread you sign for stays put unless your credit assessment changes substantially. So the day you're sanctioned is the day to ask for the lowest spread in your band, in writing. How much a score band can move your rate is in RBI moved your home loan rate by 0.25%. Your CIBIL score can move it by 1.80%, and why two borrowers at the same bank pay different rates is in why your home loan rate is higher than what the bank advertises.
How BoB compares
BoB's floor of 7.40% matches Union Bank's 7.40%. It is 0.05% below PNB's 7.45% and 0.10% below SBI's 7.50%, which is ₹306 a month on ₹50 lakh over 20 years, or ₹0.73 lakh in all. It is 0.60% below HDFC Bank's and Axis Bank's 8.00%, which is ₹1,848 a month.
Those are best cases. The 9.15% end is for weaker profiles, and it sits ₹5,496 a month above the best case. Compare at your own score. The detail on the others is in Union Bank home loan interest rate (October 2026), SBI home loan interest rate (October 2026), HDFC home loan rates at a glance, Axis Bank home loan interest rate (October 2026) and Canara Bank home loan interest rate (October 2026). See today's rates across 50+ lenders on our rate comparison page.
Bank of Baroda home loan fees and charges
From BoB's own pages. The fee page prints an effective date of 20 June 2019 and quotes charges without GST, so confirm each figure in writing.
| Fee | Amount | On ₹50 lakh |
|---|---|---|
| Processing fee, takeover | Flat ₹8,500 plus GST | ₹10,030 with GST |
| Processing fee, top-up | 0.35%, minimum ₹5,000, maximum ₹12,500, plus GST | On a ₹10 lakh top-up, ₹5,900 with GST |
| Prepayment, home loan | None | ₹0 |
| Processing fee, a fresh home loan | BoB's own table shows no figure. An aggregator says 0.50% | Ask for the number |
| Valuation, legal, stamp duty | As applicable | Ask for the number |
The takeover fee is the part to notice. It is flat, so it stays ₹10,030 whether you move ₹30 lakh or ₹3 crore. At SBI the fee for the same ₹50 lakh is ₹17,700, which is ₹7,670 more. Everything else you pay on a transfer is the same whichever lender you pick: legal and valuation, MODT stamp duty (0.5% in Karnataka), registration and small charges, which come to ₹36,000 to ₹47,000 on ₹50 lakh. Every line is in home loan balance transfer charges.
Balance transfer to Bank of Baroda
BoB runs a takeover scheme for loans from other lenders, up to ₹20 crore and up to 30 years, according to its home loan page. What it publishes:
- Rate: I couldn't find a separate takeover rate. Expect the same BRLLR plus spread as a new loan, so your score and the spread in your sanction letter decide it.
- Fee: the flat ₹8,500 plus GST above.
- Prepayment: none on a BoB home loan, so leaving BoB later costs you nothing in fees.
- Top-up: BoB's top-up is for existing home loan borrowers, from ₹1 lakh up to ₹10 crore, with age plus tenure capped at 70 (65 for NRIs). Its page builds the rate from your home loan rate plus a premium and gives no final number, so get the figure in writing before you count on it. More on top-ups in home loan top-up: interest rate, eligibility and the tax rule most people get wrong.
- Speed and paperwork: the steps, and where they stall, are in home loan transfer process, step by step.
Where BoB sits against the rest on a transfer is in best banks for home loan balance transfer in 2026.
Who BoB suits, and who should look elsewhere
BoB can make sense if you:
- Have a strong score and can land at the low end of the spread, near 7.40% to 7.90%
- Are moving a large loan in and want a flat fee of ₹10,030 instead of a percentage
- Expect to prepay. There's no prepayment charge
Look elsewhere first if you:
- Are quoted a spread above plus 0.50%, which is 8.65% or more. A lender at 7.50% beats it by ₹3,587 a month on ₹50 lakh
- Want to know your rate before you apply. BoB's grid isn't something I could read, so you'll learn your spread only from the bank
- Are only chasing a small gap. Under 1%, the transfer costs take years to earn back
Moving a loan into BoB: the numbers
Here's a worked example. Say you have:
- ₹50 lakh outstanding
- 20 years left
- A current rate of 8.75%, so an EMI of ₹44,186
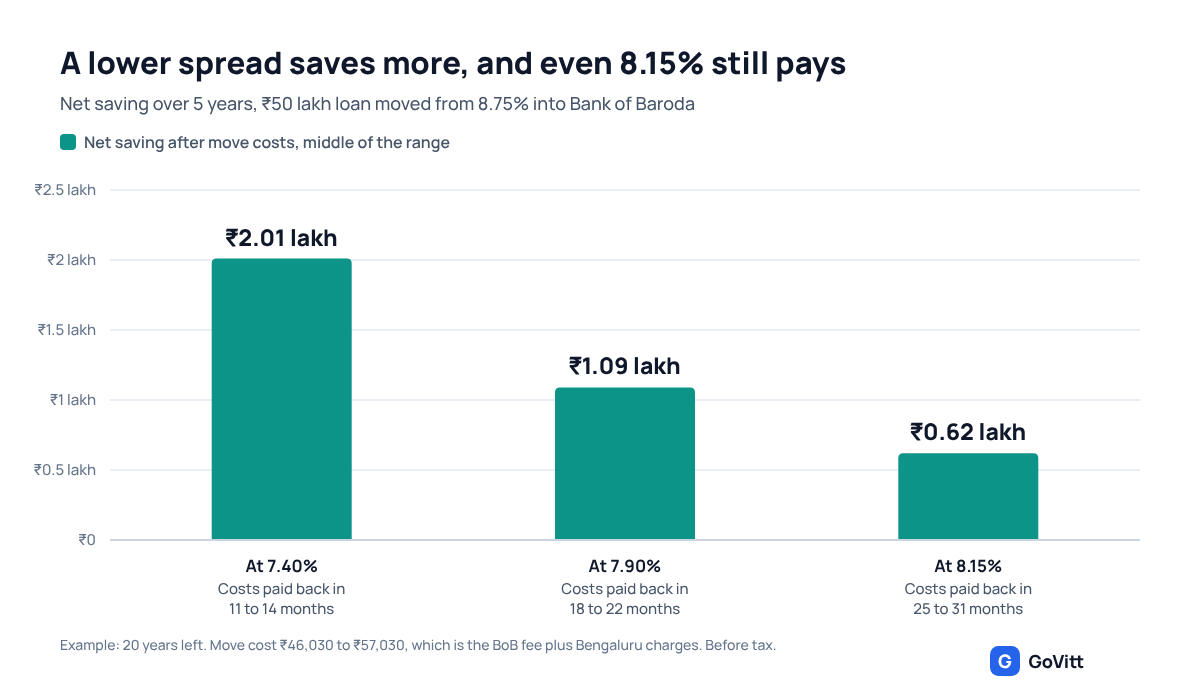
BoB's flat fee of ₹10,030 plus the shared Bengaluru charges of ₹36,000 to ₹47,000 makes the move cost ₹46,030 to ₹57,030.
| Where you land | New EMI | Saving a month | Costs paid back in | Net saving over 5 years | Net saving over 20 years |
|---|---|---|---|---|---|
| 7.40% (best spread) | ₹39,974 | ₹4,212 | 11 to 14 months | ₹1.96 to ₹2.07 lakh | ₹9.54 to ₹9.65 lakh |
| 7.90% | ₹41,511 | ₹2,675 | 18 to 22 months | ₹1.03 to ₹1.14 lakh | ₹5.85 to ₹5.96 lakh |
| 8.15% (spread zero) | ₹42,290 | ₹1,896 | 25 to 31 months | ₹0.57 to ₹0.68 lakh | ₹3.98 to ₹4.09 lakh |
What this tells you:
- Get the spread before you pay for anything. From 8.75%, moving to BoB wins at every spread in the table, but it wins by at least ₹1.96 lakh over five years at 7.40% and by at least ₹0.57 lakh at 8.15%.
- The flat fee helps most against lenders that charge a percentage. SBI's fee is ₹7,670 higher on ₹50 lakh. HDFC Bank's can run to ₹29,500 on the same loan.
- If your rate is 8.15% or lower today, skip it. At a zero spread BoB charges 8.15%, so there's nothing to gain.
The full process is on our home loan balance transfer page.
Already with BoB? Whether to switch
Your loan follows the BRLLR, so your rate moved by 0.25% on 8 October and will move again. Your spread is yours, and it stays unless your credit assessment changes. If you took the loan at a weak score and your score is better now, ask for a lower spread. I couldn't find a published fee for repricing a BoB loan that already follows the BRLLR, so get the number in writing.
Here's what it's worth, for ₹50 lakh with 20 years left, moving out to a lender at 7.50% with costs of ₹53,700 to ₹76,500:
| Your BoB rate | Saving a month | Costs paid back in | Net saving over 20 years |
|---|---|---|---|
| 9.15% (spread plus 1.00%) | ₹5,190 | 11 to 15 months | ₹11.69 to ₹11.92 lakh |
| 8.65% (spread plus 0.50%) | ₹3,587 | 15 to 22 months | ₹7.84 to ₹8.07 lakh |
| 8.15% (spread zero) | ₹2,010 | 27 to 39 months | ₹4.06 to ₹4.29 lakh |
If you're at 9.15%, asking BoB to take your spread to zero would save ₹3,180 a month, before you pay any transfer cost. Ask first. If BoB refuses, the table above is your alternative. If you're at 8.15% or lower, the saving is small and the wait is long. The logic is in rates just went up: does switching your home loan still make sense?
Compare before you sign
BoB's rate depends on a spread you only learn at sanction. Before you accept any offer, compare rates from 50+ banksand see what your profile qualifies for. GoVitt charges you 0% commission.
FAQ
What is the Bank of Baroda home loan interest rate today? As of 29 October 2026, about 7.40% to 9.15%. That is BoB's BRLLR of 8.15% plus a spread of minus 0.75% to plus 1.00%, as reported by MoneyKarma on 23 October. I couldn't read BoB's own rate sheet, so confirm your rate in your sanction letter.
What is Bank of Baroda's BRLLR? It's the Baroda Repo Based Lending Rate, the benchmark for BoB's floating rate loans. It is 8.15% from 8 October 2026, up from 7.90%. It is repo at 5.50% plus a markup of 2.65%.
What is Bank of Baroda's processing fee for a home loan takeover? A flat ₹8,500 plus GST, which is ₹10,030, according to BoB's fee page. The page prints an effective date of 20 June 2019, so confirm the figure before you rely on it.
Is there a prepayment charge on a Bank of Baroda home loan? No. BoB's own FAQ says there are no pre-payment charges on a home loan.
Can I transfer my home loan to Bank of Baroda? Yes. BoB offers a takeover scheme for home loans from other lenders, up to ₹20 crore and up to 30 years. I couldn't find a separate takeover rate, so expect the same BRLLR plus spread as a new loan.
Does Bank of Baroda give a top-up on a home loan? Yes, to existing home loan borrowers, from ₹1 lakh up to ₹10 crore. The fee is 0.35%, with a minimum of ₹5,000 and a maximum of ₹12,500, plus GST. BoB's page gives no final rate, so ask for it in writing.
Not sure BoB is your best rate? Compare rates from 50+ banks and see what your profile qualifies for. GoVitt charges you 0% commission.
Rates and fees as of 29 October 2026. The rate range and spread come from MoneyKarma (verified 23 October 2026), an aggregator, and the BRLLR from news reports of 8 October 2026; Bank of Baroda's own rate sheet could not be read. Fees come from Bank of Baroda's own pages, one of which prints an effective date of 20 June 2019. EMIs use the standard monthly reducing balance method and are rounded to the nearest rupee. The switching examples assume a property in Bengaluru. Rates change after every RBI policy decision; we will update this page after 4 December 2026.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.