
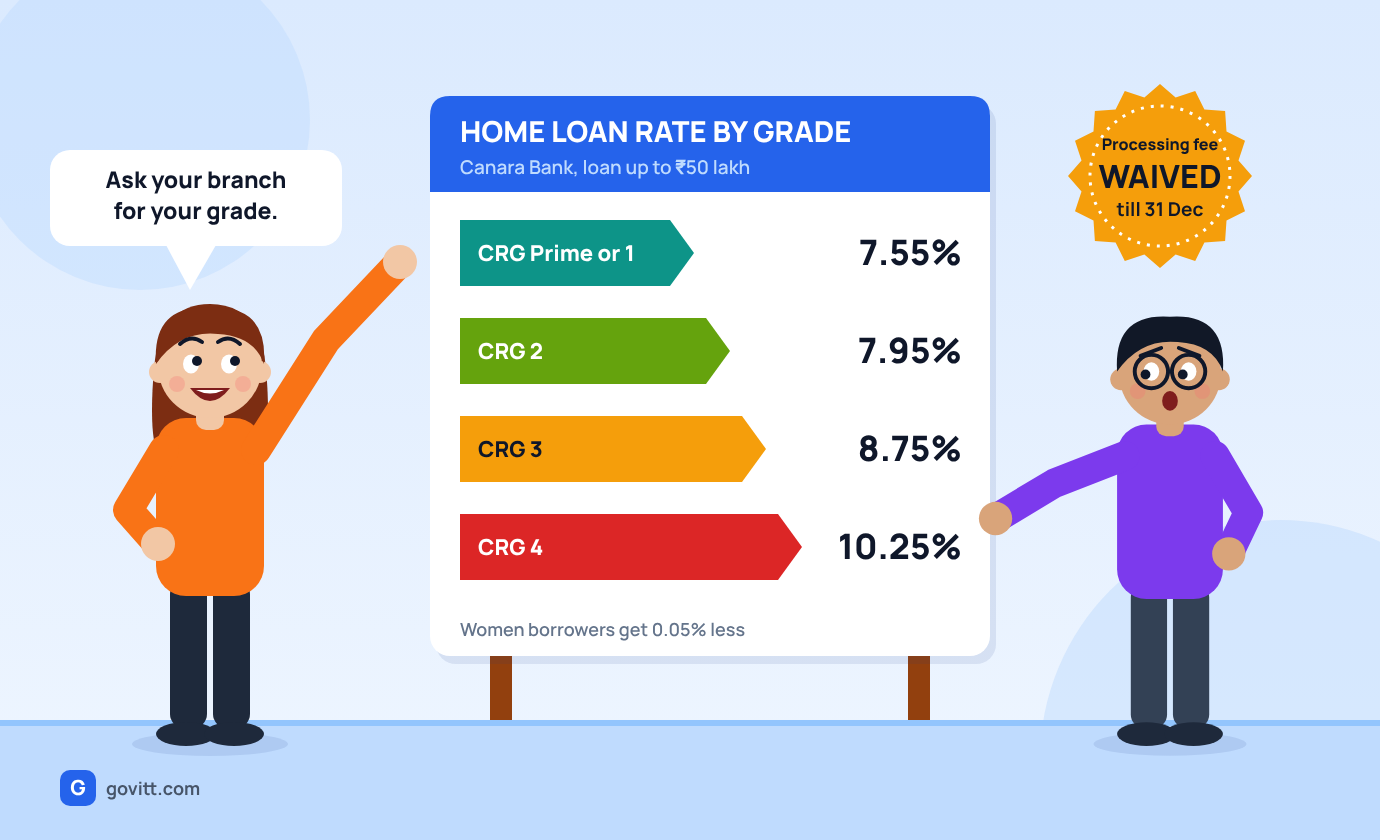
The Canara Bank home loan interest rate is 7.55% to 10.25% for loans up to ₹50 lakh, and 7.50% to 10.25% for women borrowers. Where you land depends on your credit risk grade (CRG), which is Canara's internal rating of you. A top-grade borrower pays 7.55%. A weaker one pays 10.25%.
Canara's home loans are linked to its RLLR (repo linked lending rate), which is 8.25% from 9 October 2026, after RBI raised the repo rate by 0.25% to 5.50%. Canara also has a 100% processing fee waiver on retail loans from 1 October to 31 December 2026.
Canara is headquartered in Bengaluru, and Karnataka is where this question is searched the most. Below: your rate by grade and loan size, every fee, and whether switching to Canara makes sense.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
Canara home loan rates at a glance (checked 24 October 2026)
| Item | What Canara Bank shows |
|---|---|
| Rate range, loan up to ₹50 lakh | 7.55% to 10.25% (women: 7.50% to 10.20%) |
| Benchmark | RLLR 8.25%, effective 9 October 2026 |
| Rate type | Floating, reducing balance |
| Processing fee | 0.50% (minimum ₹1,500, maximum ₹10,000), plus GST. Waived 100% from 1 October to 31 December 2026. |
| Prepayment charge | Nil |
| Maximum tenure | 30 years, or up to age 75, whichever comes first |
| Loan size for salaried borrowers | Up to 72 times gross monthly salary (up to 96 times selectively) |
Your Canara rate by credit grade and loan size
Canara sets your rate as RLLR plus a credit risk premium, minus a concession that grows with loan size. The table shows the rate for other borrowers. Women borrowers get 0.05% less in every row.
| Credit grade | Up to ₹50 lakh | ₹50 lakh to ₹1 crore | ₹1 crore to ₹2.5 crore | Above ₹2.5 crore |
|---|---|---|---|---|
| CRG Prime or CRG 1 | 7.55% | 7.50% | 7.45% | 7.45% |
| CRG 2 | 7.95% | 7.90% | 7.85% | 7.85% |
| CRG 3 | 8.75% | 8.75% | 8.75% | 8.65% |
| CRG 4 | 10.25% | 10.15% | 10.05% | 9.95% |
Canara's note adds up to 0.05% more off for takeover (balance transfer) and ready-to-move home loans, and another 0.05% for salaried employees of government bodies, PSUs, MNCs and blue chip companies who meet its salary account conditions. These apply to the top three grades. Ask what you qualify for.
Canara does not publish a chart that converts your CIBIL score into a grade. In practice a score of 750 or above, steady salaried income and a clean repayment record is what you need to be in the top grades. Ask the branch which grade you've been given, then compare it to this table. I showed how much a score band can move your rate in RBI moved your home loan rate by 0.25%. Your CIBIL score can move it by 1.80%.
What each grade costs you: ₹50 lakh over 20 years
| Your rate | EMI on ₹50 lakh, 20 years |
|---|---|
| 7.50% (women, CRG Prime or 1) | ₹40,280 |
| 7.55% (CRG Prime or 1) | ₹40,433 |
| 7.95% (CRG 2) | ₹41,667 |
| 8.75% (CRG 3) | ₹44,186 |
| 10.25% (CRG 4) | ₹49,082 |
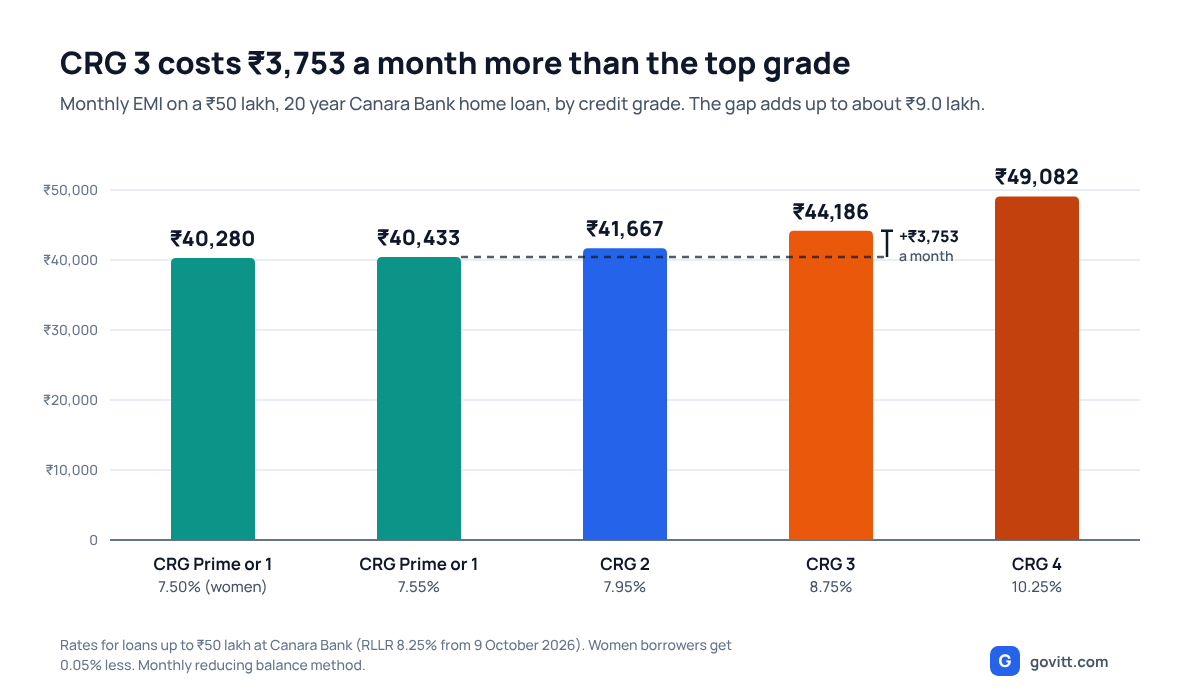
The gap between the top grade and CRG 3 is ₹3,753 a month, or about ₹9.0 lakh over 20 years. That is the price of a weaker profile. Fixing your score, closing small loans and clearing late payments before you apply is the cheapest way to save money.
How Canara compares
At 7.55%, Canara's best rate for a loan up to ₹50 lakh is only 0.05% above the lowest published rate we showed for SBI (7.50%), which is ₹153 a month on ₹50 lakh over 20 years. For loans above ₹50 lakh, Canara's top-grade rate drops to 7.50% or lower.
The comparison that matters is the rest of the table. Canara's CRG 3 rate of 8.75% is the same as ICICI's table rate, so if your profile is not top grade, look at a few lenders. See today's rates across 50+ lenders on our rate comparison page. SBI's side of the story is in SBI home loan interest rate (October 2026).
Canara home loan fees and charges
| Fee | Amount | On ₹50 lakh |
|---|---|---|
| Processing fee | 0.50%, minimum ₹1,500, maximum ₹10,000, plus GST | ₹10,000 plus GST, but ₹0 till 31 December 2026 |
| Processing fee on a takeover for Canara SB Premium Payroll customers | Waived till 31 December 2026 | ₹0 |
| Prepayment or foreclosure, floating rate | Nil | ₹0 |
| Valuation, legal and other third party charges | As actuals | Ask for the number |
| Stamp duty and registration, Karnataka | Per state rules | Ask your lawyer. See the Bengaluru khata note below. |
The fee waiver is a time limit, not a standing offer. If you plan to switch or buy, the processing fee saving is up to ₹11,800 with GST, but only if the loan is sanctioned by 31 December. Confirm with the branch what "sanctioned" means for the waiver.
Two points on the rules:
- Margin: Canara asks you to put in 10% for a new or up to 10 year old property up to ₹30 lakh, 20% between ₹30 lakh and ₹75 lakh, and 25% above ₹75 lakh. For a property over 10 years old, it is 25%.
- Loan size: 72 times your gross monthly salary is the cap for salaried borrowers. On ₹1 lakh gross, that is ₹72 lakh. Income, existing EMIs and your grade can lower this.
Buying in Bengaluru? Get the property's papers right before the loan. I wrote about that in buying a resale flat in Bengaluru: check the khata before you check the EMI.
Balance transfer to Canara
Canara takes over home loans from other banks and lenders.
- Rate: the same rate table as a new loan, so your grade and the loan size decide it. The extra 0.05% takeover concession can apply for the top three grades.
- Processing fee: waived to 31 December 2026.
- Costs that remain: legal and valuation, and in Karnataka the mortgage paperwork for the new loan. Every transfer charge is broken down in home loan balance transfer charges.
- Top-up: ask whether Canara will give a top-up at the same time. Check its rate separately. A top-up stretched over a long tenure can cost more than it looks.
Should you switch to Canara?
Say you have:
- ₹50 lakh outstanding
- 18 years (216 EMIs) left
- A current rate of 9.25%, so an EMI of ₹47,606
| Your current rate | Canara rate | New EMI | Monthly saving | Saving over 18 years | Cost paid back in (₹40,000 / ₹75,000 of costs) |
|---|---|---|---|---|---|
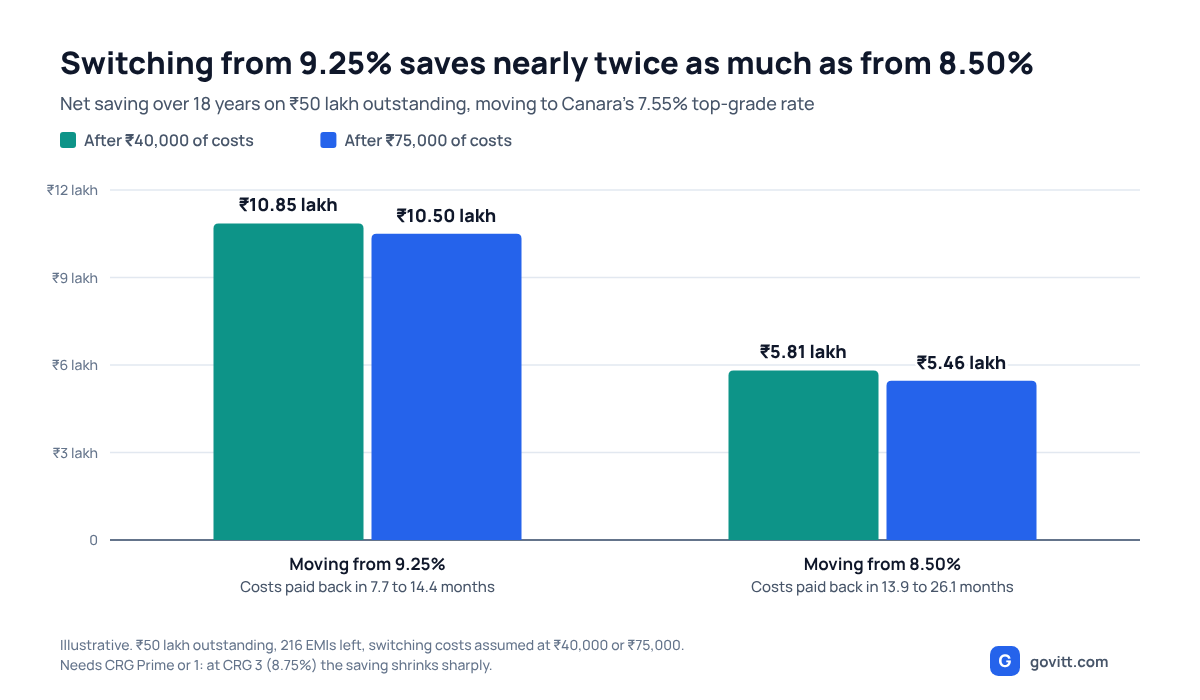
| 9.25% | 7.55% | ₹42,397 | ₹5,208 | ₹11.25 lakh | 7.7 months / 14.4 months |
| 8.50% | 7.55% | ₹42,397 | ₹2,875 | ₹6.21 lakh | 13.9 months / 26.1 months |
The costs are illustrative. With Canara's fee waived, your real costs are mostly legal, valuation and mortgage paperwork. Your own figure may be lower or higher.
What this tells you:
- Ask your own bank first. Many lenders will reprice you to a lower floating rate for a small conversion fee. Put the request in writing with the Canara rate you've seen.
- If you are at 9% or more, a transfer to a top-grade 7.55% pays back fast. About 8 to 14 months on these costs.
- If you are at 8.50% or lower, it takes longer. Switching on a small gap with few years left can cost more than it saves.
- This only works if you get the top grade. At CRG 3 (8.75%), the saving shrinks sharply. Get the rate in writing before you pay for a valuation.
The full process is on our home loan balance transfer page.
Who Canara suits, and who should look elsewhere
Canara can make sense if you:
- Have a strong credit profile and want a rate near the lowest in the market
- Are a salaried employee of a government body, PSU, MNC or blue chip company with the right salary account
- Want a no prepayment charge floating loan with up to 30 years of tenure
- Are moving a loan from a higher rate lender while the processing fee is waived
Look elsewhere first if you:
- Have a CIBIL score below 700. Canara's lower grades are expensive. The same profile may be priced differently elsewhere
- Need a sanction after 31 December and were counting on the fee waiver
- Want a long list of digital extras. Compare the service as well as the rate
Compare before you sign
Canara's best rate is for the best grade. Before you accept any offer, compare rates from 50+ banks and see what your profile qualifies for. GoVitt charges you 0% commission.
FAQ
What is the Canara Bank home loan interest rate today? As of 24 October 2026, Canara's floating home loan rate for loans up to ₹50 lakh is 7.55% to 10.25% for other borrowers and 7.50% to 10.20% for women, based on credit risk grade. The RLLR is 8.25% from 9 October 2026.
What is Canara's home loan rate for a CIBIL score of 750 or above? Canara prices by its internal credit risk grade, not directly by CIBIL. A strong profile with a score of 750 or more is aimed at the top grades (CRG Prime or 1), which carry 7.55% for loans up to ₹50 lakh. Ask the branch for your grade.
Does Canara charge a processing fee? The normal fee is 0.50%, minimum ₹1,500 and maximum ₹10,000, plus GST. Canara is waiving 100% of the fee on retail loans from 1 October to 31 December 2026.
Is there a prepayment charge on a Canara home loan? No. Canara lists no prepayment penalty on its floating rate home loans.
How much home loan can I get from Canara? For salaried borrowers, up to 72 times gross monthly salary, and selectively up to 96 times. For others, up to 6 times annual gross income, and selectively 8 times. Your income, EMIs and the property's value can lower it.
Can I transfer my home loan to Canara Bank? Yes. Canara takes over loans from other banks and lenders. The rate is the same table as a new loan, and its processing fee is waived till 31 December 2026. Third party costs remain.
Rates and fees as of 24 October 2026, from Canara Bank's retail rates linked to RLLR page and home loan page. EMIs use the standard monthly reducing balance method. Rates change after every RBI policy decision; we will update this page after 4 December 2026.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.