
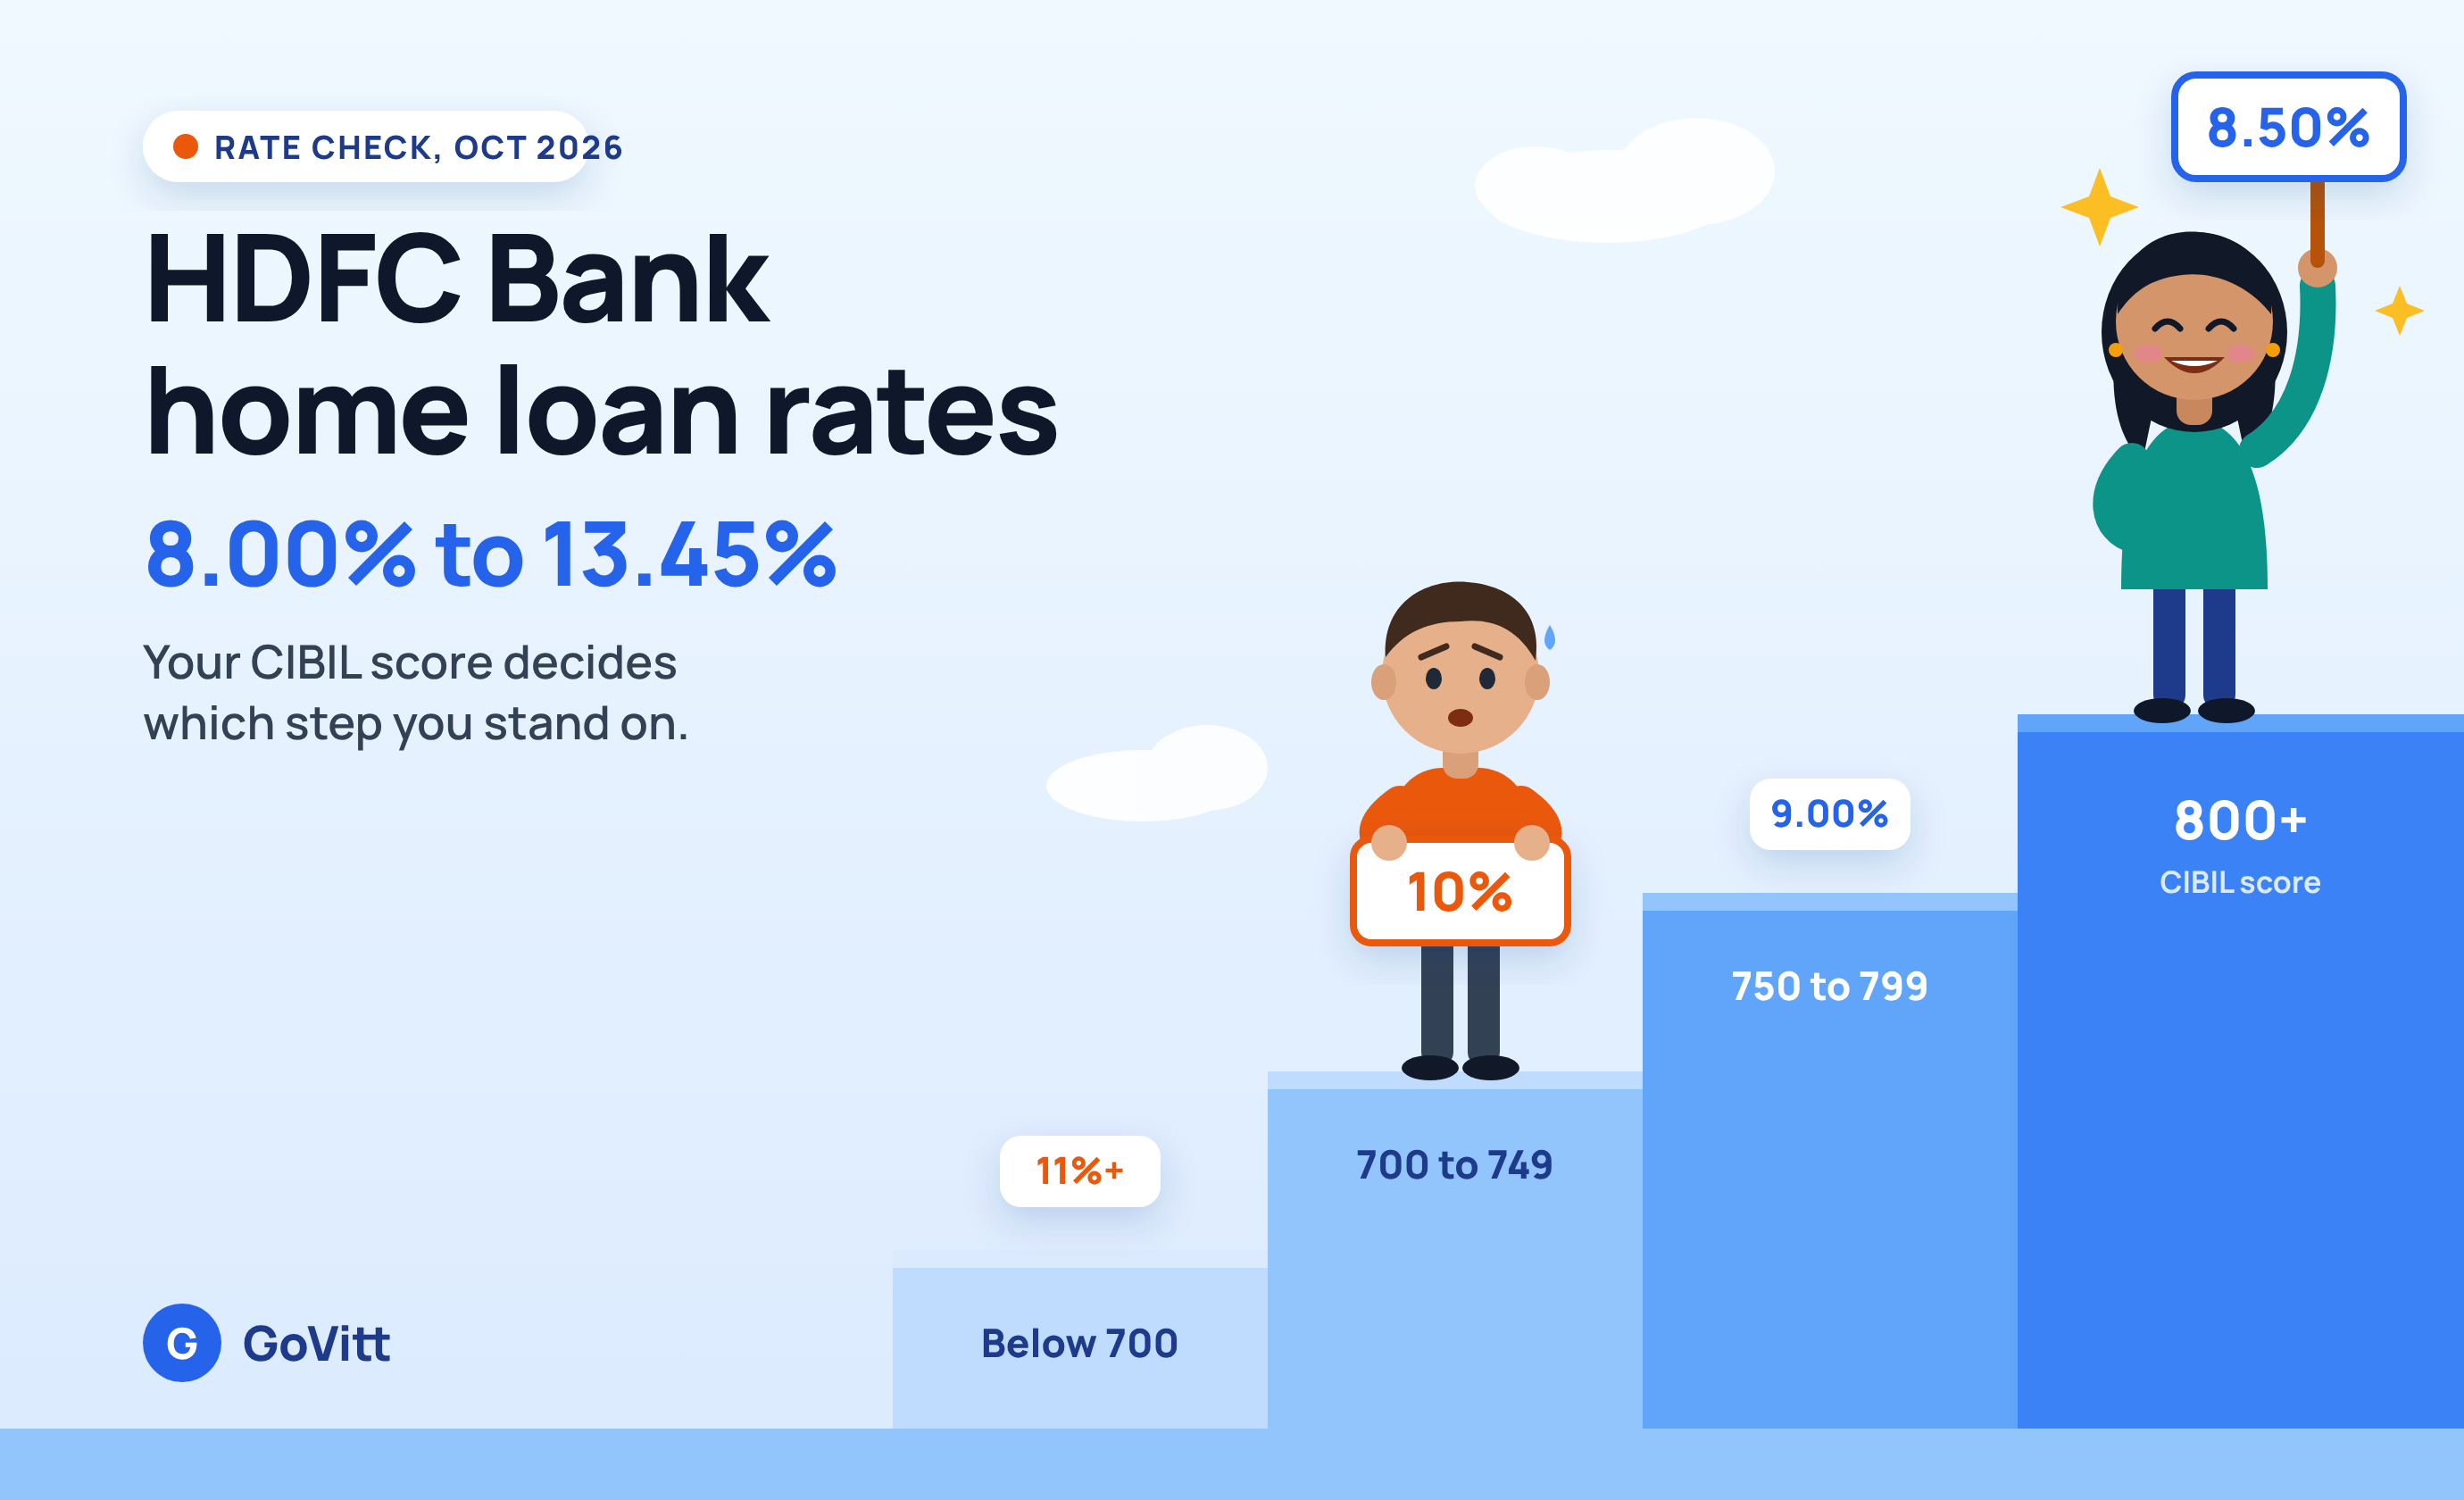
HDFC home loan interest rate today is 8.00% to 13.45% a year on floating rate loans. That's HDFC Bank's published spread of 2.50% to 7.95% over RBI's repo rate, which went up to 5.50% on 7 October.
Before the hike, the same range was 7.75% to 13.20%. So every HDFC floating rate borrower just got 0.25% more expensive, whether or not they noticed the SMS.
For context, SBI now starts at 7.50%. On a ₹50 lakh loan over 20 years, HDFC's lowest published rate costs you ₹1,542 a month more than SBI's lowest. That's ₹3.70 lakh over the loan.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
Here's what HDFC will actually charge you, every fee you'll pay, and when it makes sense to switch to or away from it.
| Item | What HDFC Bank shows |
|---|---|
| Floating rate (salaried and self-employed, all loan amounts) | Repo + 2.50% to 7.95% = 8.00% to 13.45% |
| Repo rate used | 5.50% (after RBI's 7 October 2026 hike) |
| Best card rate shown | 8.50% for 15, 20 and 30 year tenures, credit score 800 and above |
| Top-up taken along with a balance transfer | Repo + 2.75% to 8.45% = 8.25% to 13.95% |
| Rate range before the hike (29 Sept 2026) | 7.75% to 13.20% |
| Max tenure | 30 years, or until retirement if earlier |
| Max loan to value | 90% up to ₹30 lakh, 80% from ₹30 lakh to ₹75 lakh, 75% above ₹75 lakh |
Two oddities on HDFC's own rate page: its title still says rates start at 7.20%, while the body says 8%. The formula can't produce 7.20% at today's repo rate. Go by the formula.
How HDFC sets your rate
Your rate has two parts:
- Repo rate (5.50%). Same for everyone. Moves when RBI moves. The next decision is on 4 December.
- Spread (2.50% to 7.95%). Set for you at sanction. This is where your credit score, income, job type, loan amount and how much you borrow against the property's value come in.
Under RBI rules for repo linked loans, the spread can't be changed later unless your credit assessment changes substantially. So the spread you sign for is the one you live with, unless you pay to reset it. That makes the day of sanction the day to negotiate.
Your HDFC rate by CIBIL slab
HDFC Bank doesn't publish a full credit score grid. It shows one data point: 8.50% for scores of 800 and above. The table below fills in the rest with our estimate, based on HDFC's published floor and that card rate. Treat it as a guide. Your sanction letter is the only number that counts.
| CIBIL score | What HDFC shows | GoVitt estimate | EMI on ₹50 lakh, 20 years |
|---|---|---|---|
| 800 and above | 8.50% card rate | 8.00% to 8.50% | ₹41,822 to ₹43,391 |
| 750 to 799 | Not published | 8.50% to 9.00% | ₹43,391 to ₹44,986 |
| 700 to 749 | Not published | 9.00% to 10.00% | ₹44,986 to ₹48,251 |
| Below 700 | Not published | 10.00% and up, if approved | ₹48,251 and up |
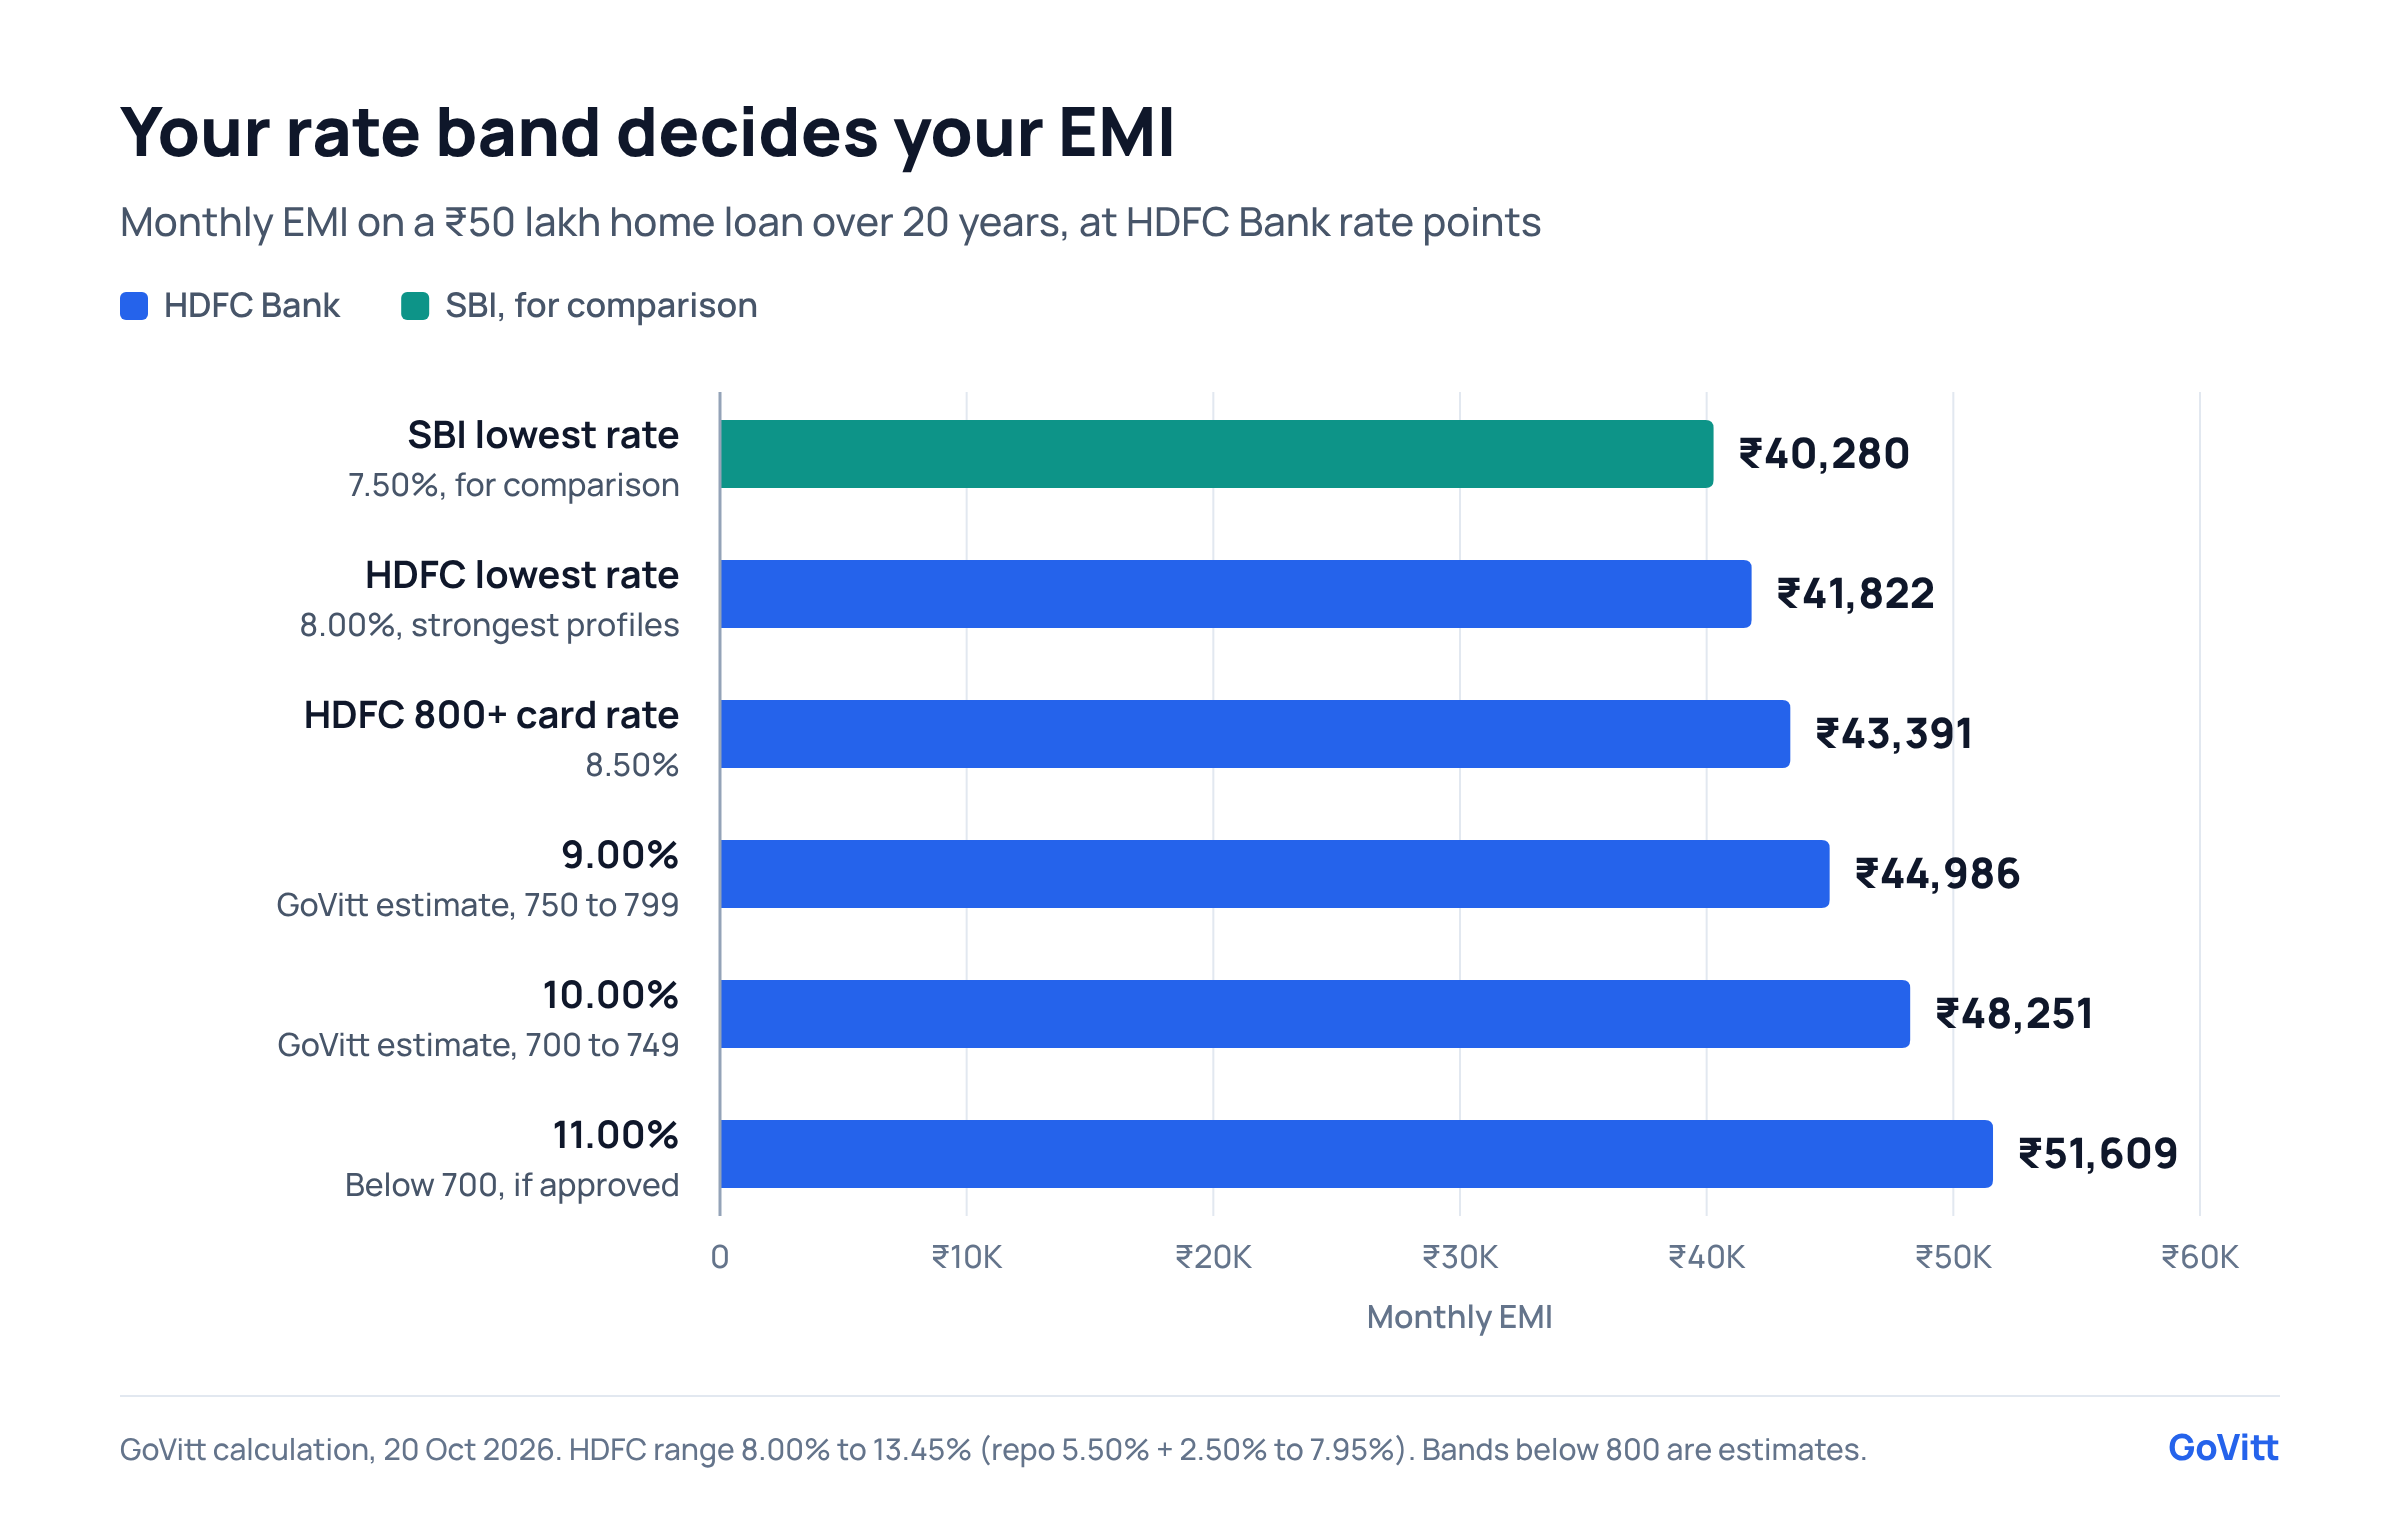
Bar chart of monthly EMI on a ₹50 lakh, 20 year home loan at HDFC Bank rate points: ₹41,822 at 8.00%, ₹43,391 at 8.50%, ₹44,986 at 9.00%, ₹48,251 at 10.00% and ₹51,609 at 11.00%, with SBI's lowest rate of 7.50% at ₹40,280 shown for comparison.
Caption: Moving from HDFC's best rate to 10% adds ₹6,429 a month on ₹50 lakh.
One more data point worth knowing. HDFC's own disclosure of rates it actually gave housing loan customers in April to June 2026 shows a range of 7.1% to 12%, with an average of 7.35%. That's below its published card floor at the time. So the card rate is a starting point, not a final answer. A strong profile with a competing offer in hand can push it down.
If your score is below 750, fix that before you apply. I've shown how much a score band moves your rate in RBI moved your rate by 0.25%. Your CIBIL score can move it by 1.80%.
HDFC home loan fees and charges
| Fee | Amount | On ₹50 lakh |
|---|---|---|
| Processing fee, salaried and self-employed professionals | Up to 0.50% of the loan or ₹4,000, whichever is higher, plus taxes | Up to ₹29,500 with GST |
| Processing fee, self-employed non-professionals | Up to 1.50% of the loan or ₹5,000, whichever is higher, plus taxes | Up to ₹88,500 with GST |
| Conversion to a lower rate (existing borrowers) | 0.25% of principal outstanding or ₹5,000, whichever is lower, plus taxes | ₹5,900 with GST |
| Fixed (TruFixed) to floating | 1.75% of principal outstanding, plus taxes | ₹1,03,250 with GST |
| Prepayment on a floating rate loan | Nil for individual borrowers | ₹0 |
The processing fee says "up to". It's negotiable, especially during festive offers. Ask for a waiver in writing before you sign.
Balance transfer to HDFC, and top-up
- Rate: the same 8.00% to 13.45% range as a new loan.
- Eligibility: at least 12 months of regular repayment on your current loan.
- Top-up along with the transfer: 8.25% to 13.95%. HDFC's page gives two different caps (₹50 lakh in one place, ₹1 crore in another), so confirm the limit in writing. Total borrowing stays within 75% to 80% of the property's value, as HDFC assesses it.
- Top-up tenure: up to 15 years.
- Documents: a list of property papers from your current lender, a balance outstanding letter on its letterhead, property document copies, KYC, and income proof (3 months' salary slips, 6 months' bank statements, latest Form 16 and ITR for salaried borrowers).
Who HDFC suits, and who should look elsewhere
HDFC can make sense if you:
- Have a strong profile and a competing offer to negotiate with
- Need a large loan or a 30 year tenure
- Want a top-up and a transfer done together
- Are self-employed or have an uneven income. HDFC's range runs up to 13.45%, so it prices profiles that stricter lenders may simply turn down
Look elsewhere first if you:
- Have a CIBIL score of 750 or more and a clean salaried profile. Public sector banks start lower right now. SBI's range is 7.50% to 8.80%. See today's rates across 50+ lenders on our rate comparison page.
- Care mostly about the lowest rate and not about servicing
Already with HDFC? Whether to switch
Here's a worked example. Say you have:
- ₹50 lakh outstanding
- 18 years (216 EMIs) left
- A current rate of 9.00%, so an EMI of ₹46,822
| Option | Cost | Monthly saving | Net saving over 18 years | Cost paid back in |
|---|---|---|---|---|
| Ask HDFC to cut you to its 8.50% card rate | ₹5,900 | ₹1,549 | ₹3.29 lakh | About 4 months |
| Transfer to a lender at 7.50% | ₹53,700 to ₹76,500 | ₹4,574 | ₹9.11 lakh to ₹9.34 lakh | 12 to 17 months |
| Transfer after HDFC has already cut you to 8.50% | ₹65,100 (midpoint) | ₹3,025 | ₹5.88 lakh | About 22 months |
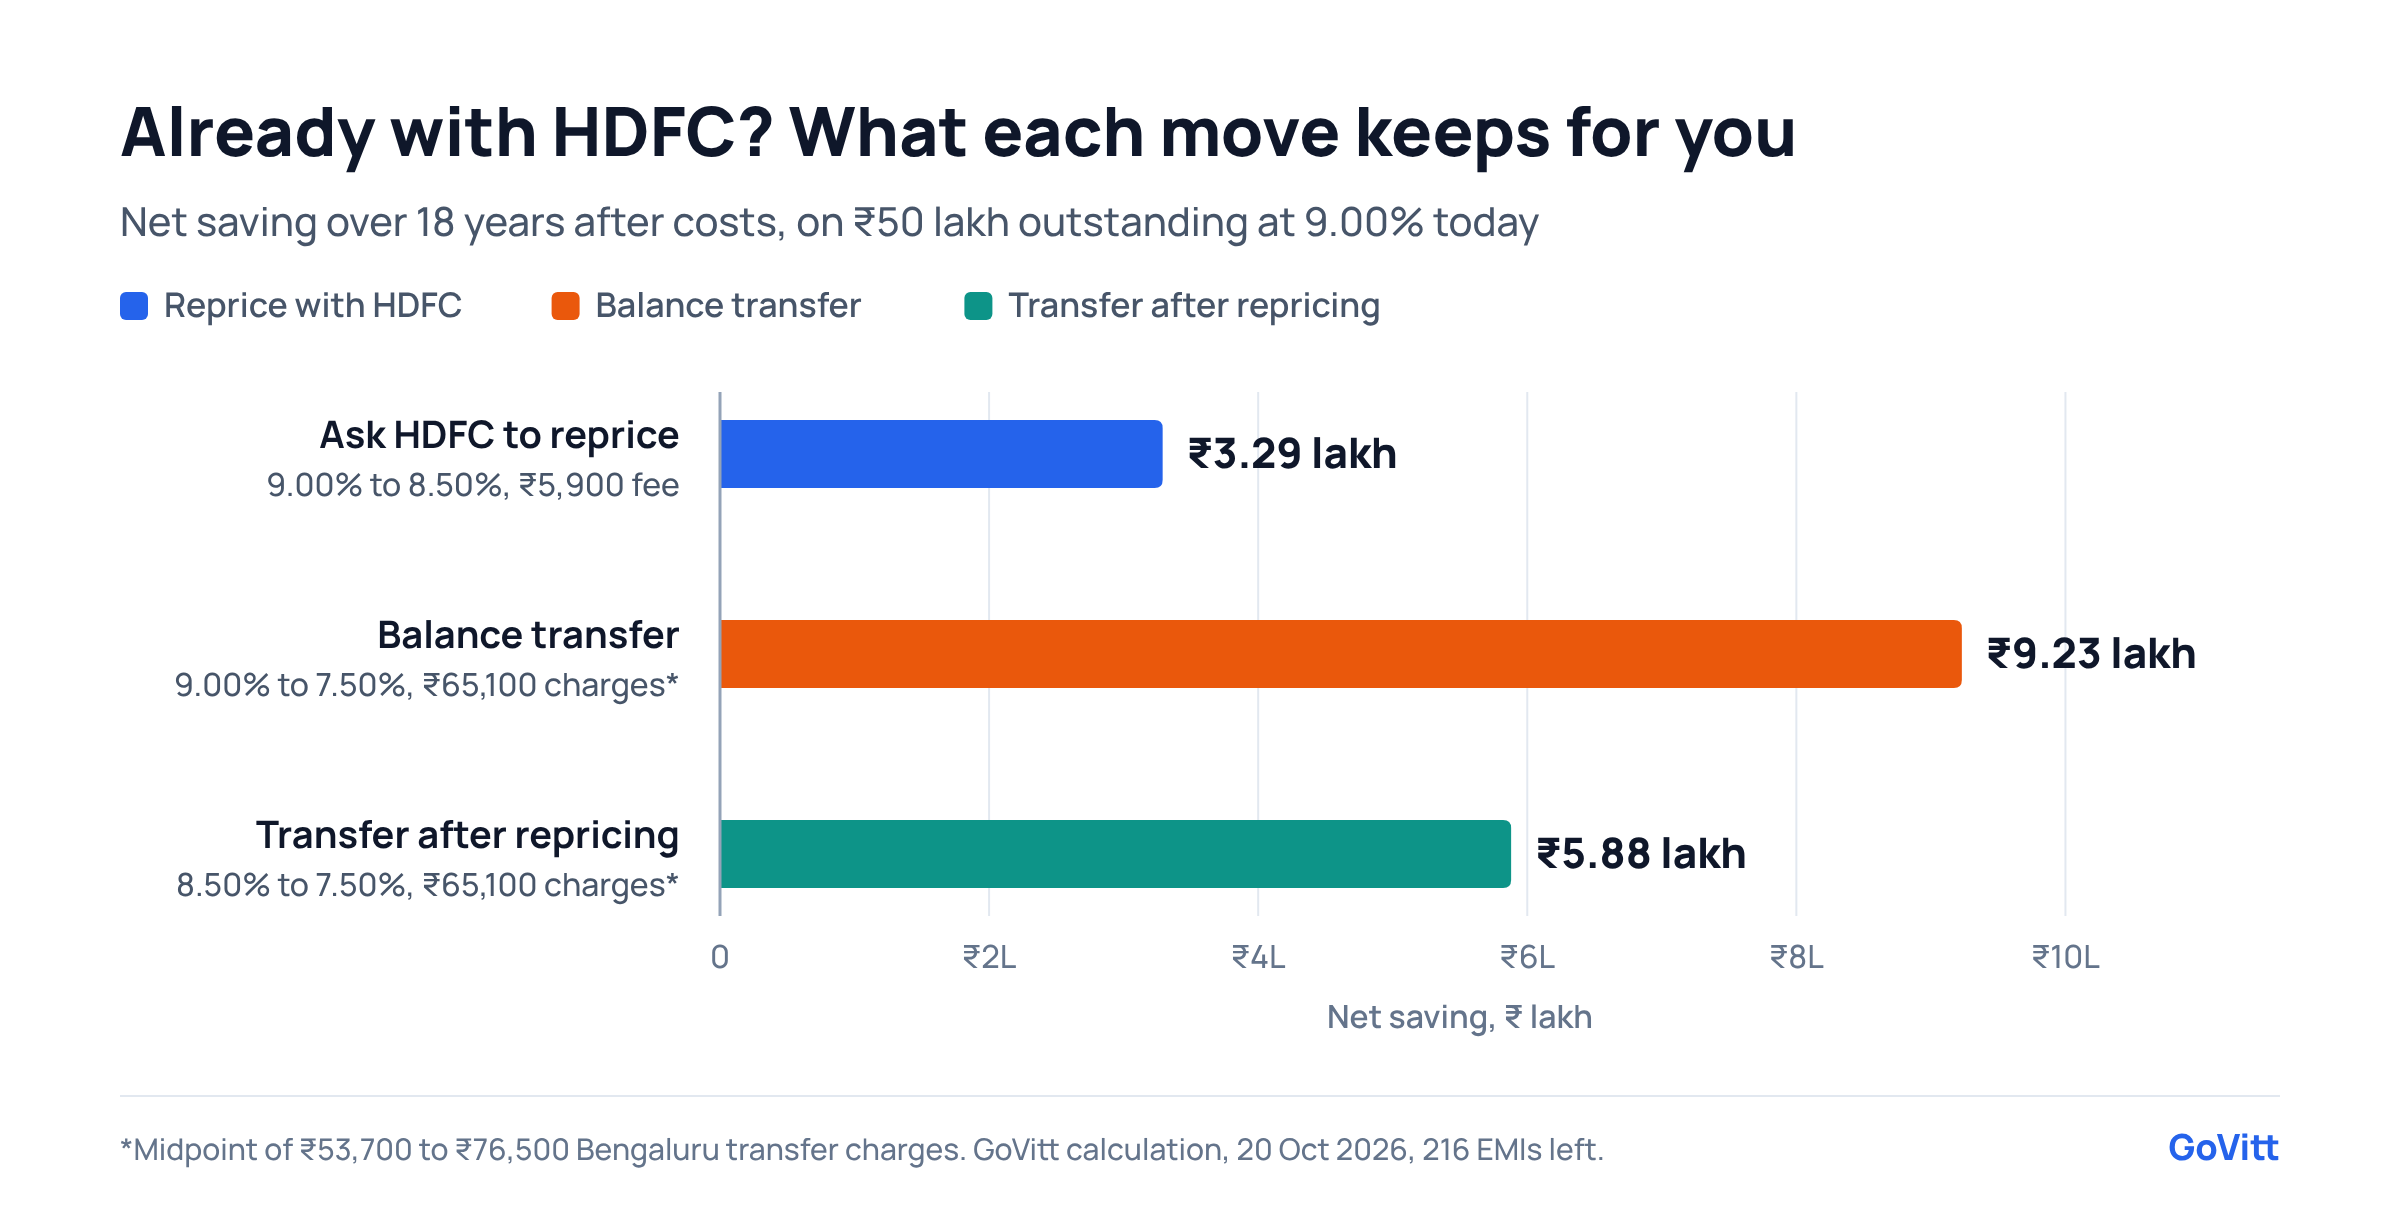
Bar chart of net savings over 18 years for an HDFC Bank borrower with ₹50 lakh outstanding at 9.00%: ₹3.29 lakh by repricing with HDFC to 8.50%, ₹9.23 lakh by transferring to 7.50%, and ₹5.88 lakh by transferring to 7.50% after HDFC has already cut the rate to 8.50%.
Caption: For HDFC borrowers, the gap to the cheapest lenders is wide enough that a transfer can still win, even after HDFC cuts your rate.
What this tells you:
- Ask HDFC first anyway. It's a ₹5,900 fee and pays back in about 4 months. The exact email to send is in how to reduce your home loan interest rate with the same bank.
- Then compare. HDFC's floor is 0.50% above SBI's. If you can get 7.50% elsewhere and have many years left, the transfer pays even after a repricing. Every transfer charge is broken down in home loan balance transfer charges.
- Don't transfer for less than about 0.50% unless you have 15 years or more left. The charges eat a small gap.
Our home loan balance transfer page walks through the full process.
FAQ
What is the HDFC home loan interest rate today? As of 20 October 2026, HDFC Bank's floating home loan rate is 8.00% to 13.45% a year. That's the repo rate of 5.50% plus a spread of 2.50% to 7.95%. The best card rate it shows is 8.50% for borrowers with a credit score of 800 and above.
Did HDFC raise home loan rates after RBI's October hike? Yes. HDFC's range moved from 7.75% to 13.20% in late September to 8.00% to 13.45% now, a 0.25% increase in line with RBI's repo hike on 7 October. Existing borrowers see it at their next reset date.
What CIBIL score do I need for HDFC's lowest home loan rate? HDFC shows its 8.50% card rate for scores of 800 and above. The lowest published rate, 8.00%, will typically go to the strongest profiles: high scores, stable income and a lower loan to value.
What is HDFC's home loan processing fee? Up to 0.50% of the loan amount or ₹4,000, whichever is higher, plus taxes, for salaried and self-employed professionals. Self-employed non-professionals pay up to 1.50% or ₹5,000, whichever is higher.
Can I lower my HDFC home loan rate without switching banks? Yes. HDFC lets existing borrowers convert to a lower rate for 0.25% of the outstanding amount or ₹5,000, whichever is lower, plus taxes. You can request it through HDFC's customer portal under Requests and then Conversion Enquiry.
Not sure HDFC is your best rate? Compare rates from 50+ banks and see what your profile qualifies for. GoVitt charges you 0% commission.
Rates and fees as of 20 October 2026, from HDFC Bank's own rate, balance transfer, top-up and conversion pages. CIBIL slab estimates are GoVitt's, not HDFC's. EMIs use the standard reducing balance method. Rates change after every RBI policy decision; we'll update this page after 4 December 2026.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.