
The LIC home loan interest rate starts at 7.15% for salaried borrowers with a CIBIL score of 825 or more, going by LIC Housing Finance's published rate grid. That's below the lowest published rates at SBI (7.50%) and HDFC Bank (8.00%) today.
There's one thing to know before you read on. RBI raised the repo rate on 7 October. Most banks passed it on the next day. As of 22 October, we couldn't find any announcement of LIC Housing Finance changing its home loan rates since. LIC Housing Finance is a housing finance company. Its rates follow its own prime lending rate, not repo directly, so it moves when it decides to. That can work in your favour now, and against you later.
Below: your LIC rate by credit score, every fee, how LIC sets your rate, and whether to stay, reprice or switch.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
LIC Housing Finance rates at a glance (checked 22 October 2026)
| Item | What LIC Housing Finance shows |
|---|---|
| Floating rate, salaried | From 7.15% (CIBIL 825+) |
| Floating rate, self-employed | From 7.25% (CIBIL 825+) |
| Fixed rate | From 8.50%, for CIBIL 750+ |
| Rates on home loans it signed, July to September 2026 | 7.15% to 11.00% |
| Benchmark | LIC Housing Finance's own prime lending rate (LHPLR) |
| Processing fee | 0.25% of the loan up to ₹1 crore, capped at ₹15,000, plus GST |
Your LIC rate by CIBIL score
For loans up to ₹50 lakh. Loans from ₹50 lakh to ₹2 crore cost about 0.10% more in most bands.
| CIBIL score | Salaried | Self-employed | EMI on ₹50 lakh, 20 years (salaried) |
|---|---|---|---|
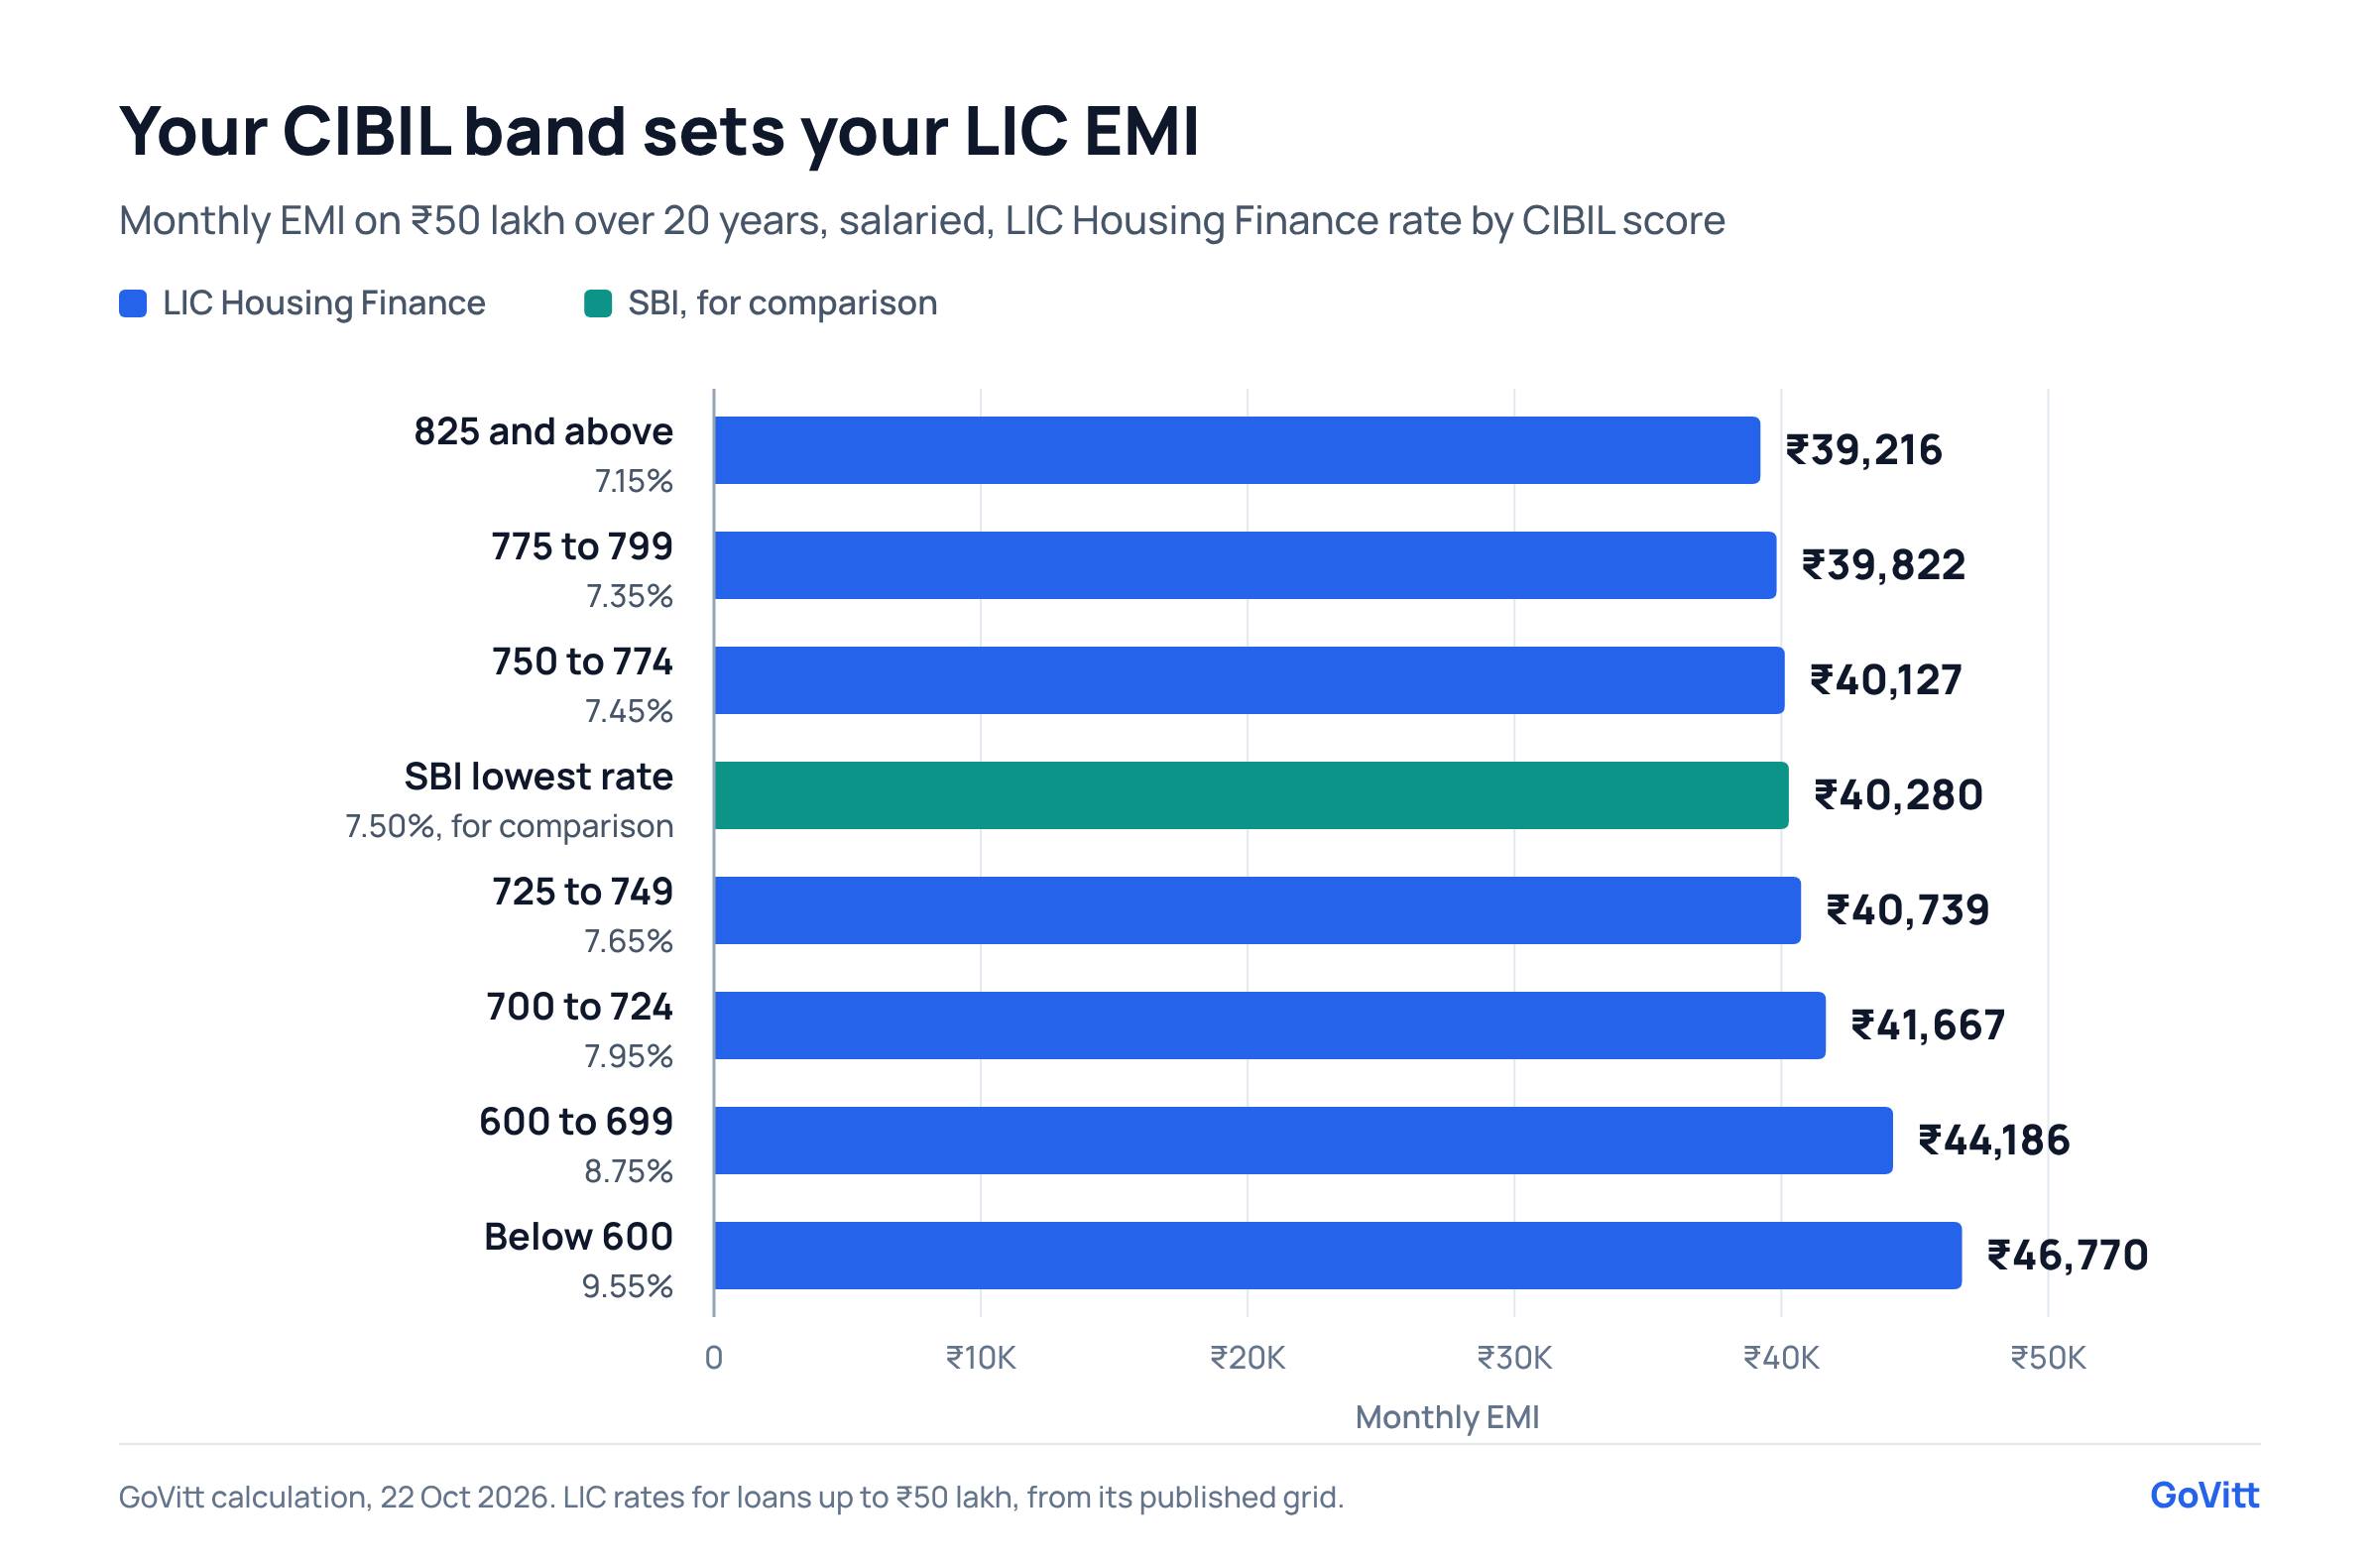
| 825 and above | 7.15% | 7.25% | ₹39,216 |
| 800 to 824 | 7.25% | 7.35% | ₹39,519 |
| 775 to 799 | 7.35% | 7.45% | ₹39,822 |
| 750 to 774 | 7.45% | 7.55% | ₹40,127 |
| 725 to 749 | 7.65% | 7.75% | ₹40,739 |
| 700 to 724 | 7.95% | 8.15% | ₹41,667 |
| 600 to 699 | 8.75% | 8.95% | ₹44,186 |
| Below 600 | 9.55% | 9.65% | ₹46,770 |
Two things stand out:
- The grid is fine-grained. LIC moves you in steps of 0.10% to 0.30% as your score rises, all the way up to 825. Most banks lump everyone above 750 or 800 together. So a few extra points on your score are worth more at LIC than at most banks.
- The drop below 700 is steep. Going from the 700 to 724 band to the 600 to 699 band adds 0.80%, about ₹2,500 a month on ₹50 lakh.
How much a score band moves your EMI is covered in RBI moved your home loan rate by 0.25%. Your CIBIL score can move it by 1.80%.
What LIC actually charged in the last quarter
Every lender publishes the range of rates it actually gave borrowers. LIC Housing Finance's disclosure for July to September 2026 shows:
- Individual home loans: 7.15% to 11.00%. Average rates by scheme start at 7.53%.
- Top-up loans (Griha Vikas Top Up): from 7.65%, with an average of 8.27%.
So 7.15% is real, but it's the floor. Plan with the rate for your own credit band, not the headline.
How LIC Housing Finance sets your rate
Banks link home loans to the repo rate, and must reset them at least every three months. LIC Housing Finance links your loan to its own LIC Housing Prime Lending Rate (LHPLR), and decides when to move it.
What that means for you:
- Hikes may come later, or not at all. That's why LIC's published rates look unchanged after the October repo hike.
- Cuts can come later too. When RBI eventually cuts, an HFC doesn't have to pass it on quickly.
- Old borrowers often pay more than new ones. Your spread over LHPLR was set when you took the loan. New borrowers today may get a much lower rate than you.
RBI's August 2026 draft on loan pricing would bring housing finance companies closer to bank rules, with resets at least every quarter. It's still a draft. I've explained why it matters in RBI's new loan pricing draft.
LIC Housing Finance fees and charges
| Fee | Amount | On ₹50 lakh |
|---|---|---|
| Processing fee | 0.25% of the loan up to ₹1 crore, capped at ₹15,000, plus GST | ₹14,750 with GST |
| Processing fee, ₹1 crore to ₹2 crore | ₹20,000, plus GST | Not applicable |
| Prepayment, floating rate, individual borrower | Nil | ₹0 |
| Prepayment, fixed rate | Nil from your own funds; 2% if repaid with money from another lender | Depends on the amount |
| Conversion to a lower rate (existing borrowers) | Not published online | Ask for it in writing |
Published fee details for LIC Housing Finance vary between sources. Get the exact fee in your sanction letter before you sign.
Balance transfer to LIC Housing Finance
- Rate: LIC Housing Finance doesn't publish a separate balance transfer rate. Expect the same CIBIL-based grid as a new loan.
- Prepayment: no prepayment charges on its home loan balance transfer product.
- Documents: KYC, income proof and property papers. The full list is in documents required for home loan balance transfer.
Moving from a bank to LIC Housing Finance only makes sense if the rate gap is wide and you're comfortable with a rate that isn't tied to repo. Price every charge first using home loan balance transfer charges.
Who LIC Housing Finance suits, and who should look elsewhere
LIC can make sense if you:
- Have a CIBIL score of 775 or more. LIC's grid rewards high scores more finely than most banks
- Are self-employed. LIC charges only 0.10% more than for salaried borrowers in most bands
- Need a large loan. The grid goes up to ₹15 crore
Look elsewhere first if you:
- Want your rate to follow repo, so future cuts reach you within three months
- Have a score below 700. The jump to 8.75% and above is steep
Already with LIC Housing Finance? Whether to switch
Here's a worked example. Say you have:
- ₹50 lakh outstanding
- 18 years (216 EMIs) left
- A rate of 9.00% from an older loan, so an EMI of ₹46,822
| Option | Cost | Monthly saving | Net saving over 18 years |
|---|---|---|---|
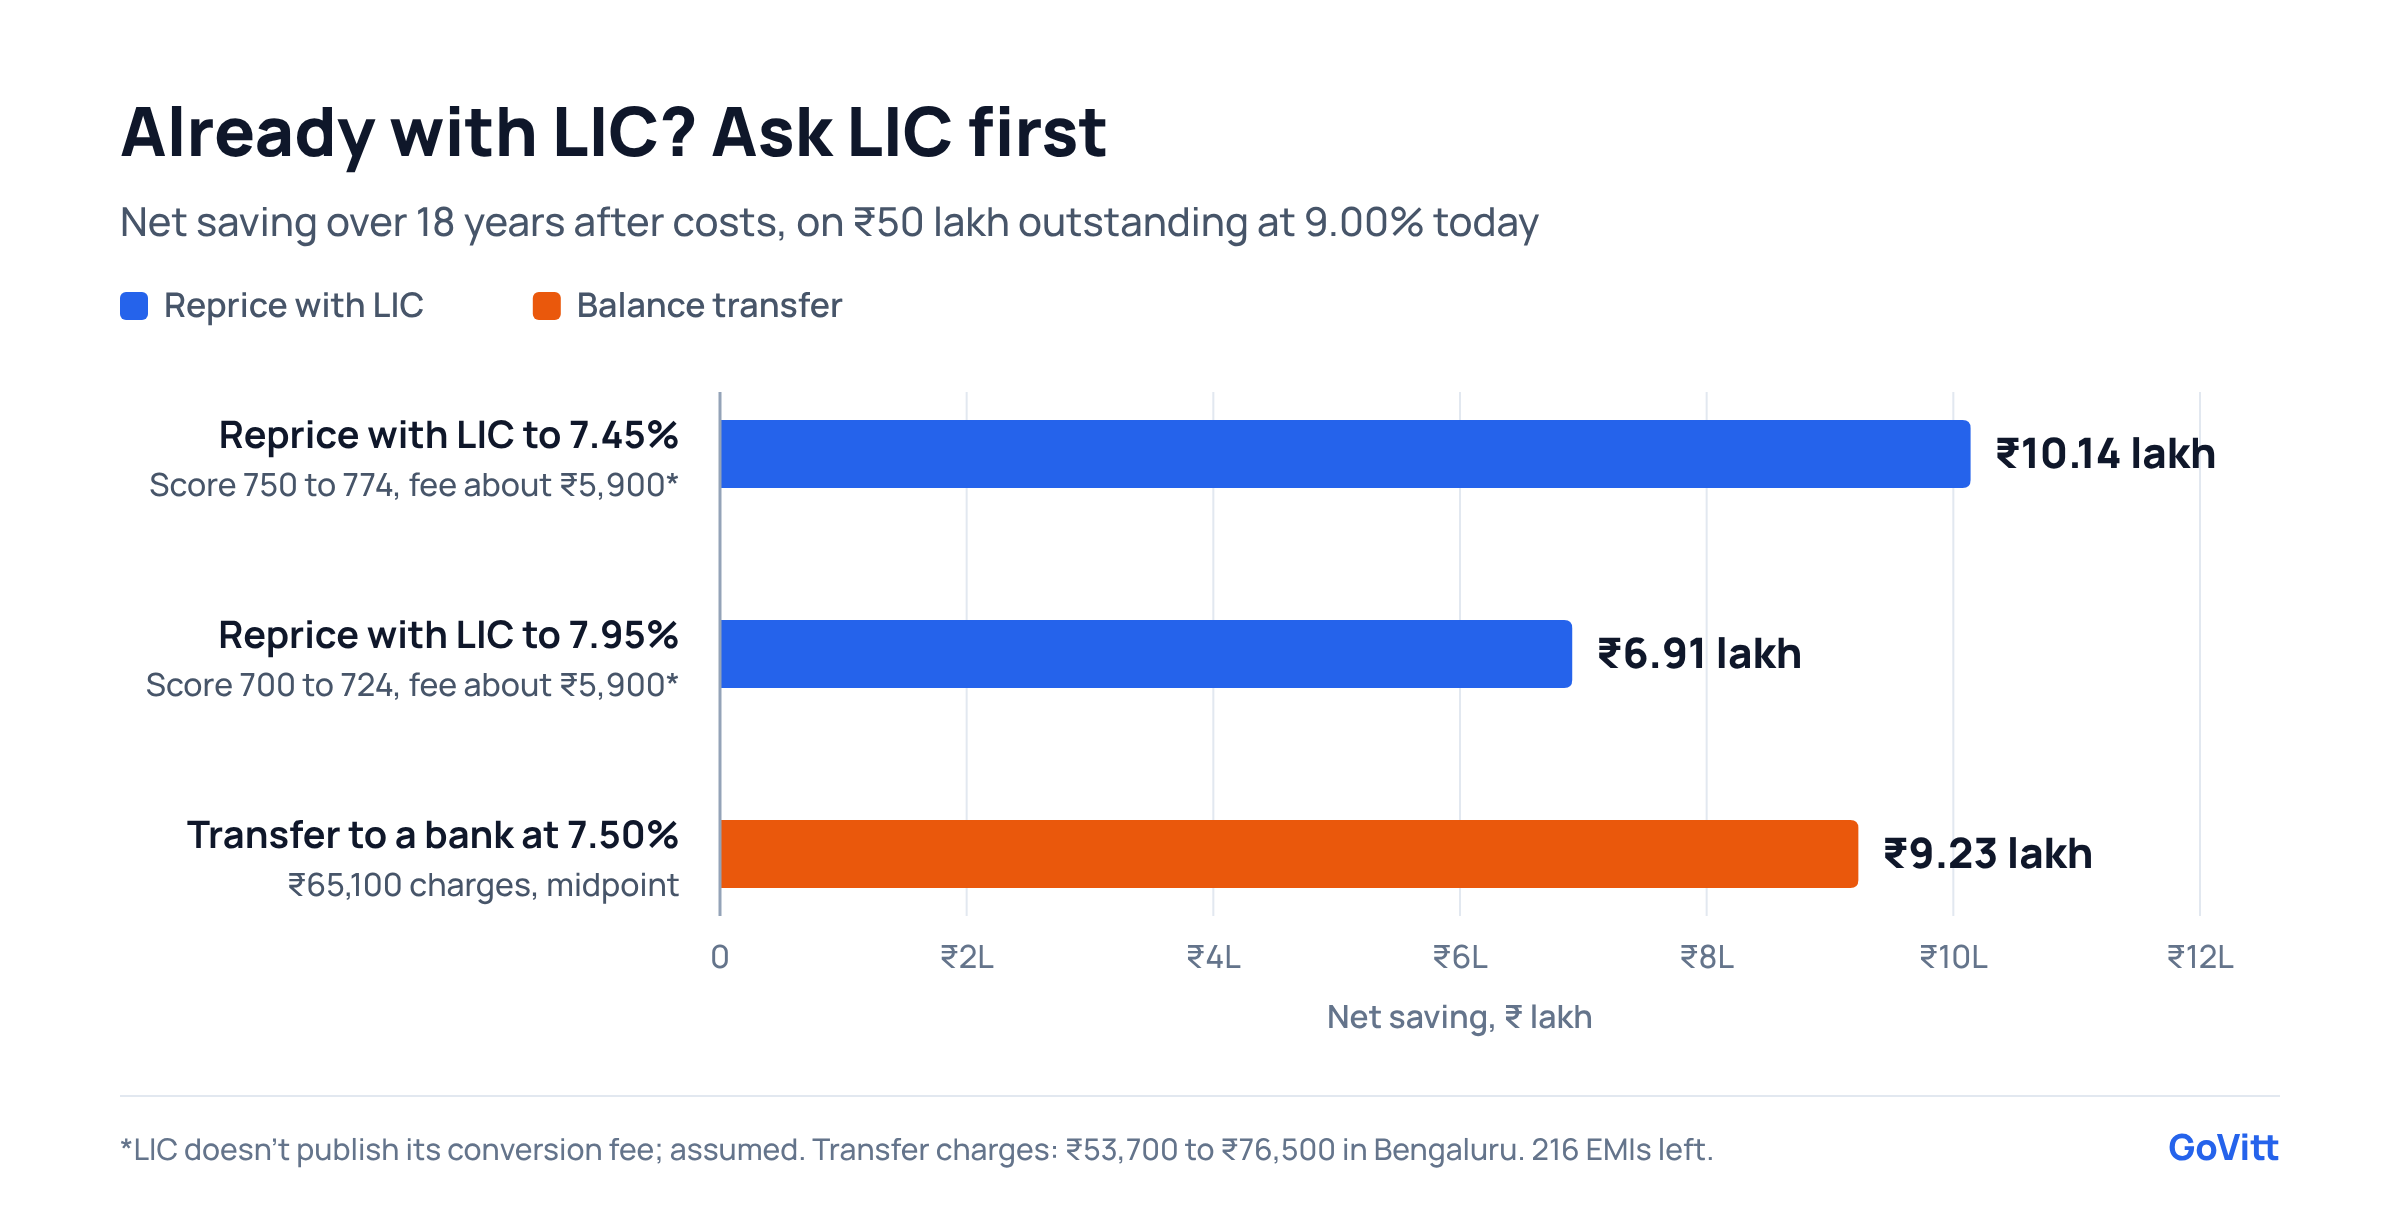
| Ask LIC to move you to 7.45% (score 750 to 774) | About ₹5,900, assumed | ₹4,722 | ₹10.14 lakh |
| Ask LIC to move you to 7.95% (score 700 to 724) | About ₹5,900, assumed | ₹3,225 | ₹6.91 lakh |
| Transfer to a bank at 7.50% | ₹53,700 to ₹76,500 | ₹4,574 | ₹9.11 lakh to ₹9.34 lakh |
What this tells you:
- Ask LIC first. LIC's own rates for new borrowers are as low as the banks'. If you have a score of 750 or more, repricing inside LIC saves you more than a transfer, at a fraction of the cost.
- Get the conversion fee in writing. LIC doesn't publish it online. The table assumes about ₹5,900, similar to other big lenders.
- If LIC won't reprice, transfer. A bank at 7.50% still saves you over ₹9 lakh, even after paying every transfer charge. You'd also get a repo-linked rate. The full process is on our home loan balance transfer page.
Compare before you sign
LIC's rate depends heavily on your credit score. Before you accept any offer, compare rates from 50+ banks and see what your profile qualifies for. GoVitt charges you 0% commission.
FAQ
What is the LIC home loan interest rate today? LIC Housing Finance's published floating rates start at 7.15% for salaried borrowers and 7.25% for self-employed borrowers with a CIBIL score of 825 or more. They rise to 9.55% to 9.65% for scores below 600. On home loans it signed from July to September 2026, rates ranged from 7.15% to 11.00%.
Has LIC Housing Finance raised its home loan rate after RBI's October 2026 hike? As of 22 October 2026, we couldn't find any announcement of a change. LIC Housing Finance's rates follow its own prime lending rate, not repo directly, so it decides when to move. Check your sanction letter for the rate you'll actually get.
What CIBIL score do I need for LIC Housing Finance's lowest rate? 825 or more. Between 750 and 824, the rate rises in small steps, from 7.25% to 7.45% for salaried borrowers on loans up to ₹50 lakh.
What is LIC Housing Finance's processing fee? As listed, 0.25% of the loan for loans up to ₹1 crore, capped at ₹15,000, plus GST. Larger loans carry flat fees. Confirm the exact amount in your sanction letter.
Should I move my LIC Housing Finance home loan to a bank? Ask LIC to reprice you first. Its new-customer rates are as low as many banks', so repricing can save more than a transfer for less money. If LIC refuses and you pay 1% or more above the best bank rates, a transfer usually pays for itself within about 1 to 2 years.
Rates as of 22 October 2026, from LIC Housing Finance's published rate grid and its disclosure of rates on loans contracted in July to September 2026. EMIs use the standard monthly reducing balance method. The conversion fee in the switch example is an assumption.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.