
Every year, somewhere between Navratri and Diwali, my WhatsApp fills up with the same kind of screenshot. A bank banner, lots of gold and orange, and one big line on it. "Zero processing fee." "Rates starting 7.2%." "Limited period festive offer."
And the same question under it: is this a good deal?
Sometimes, yes. Quite often though, the banner is selling you the cheapest part of the loan.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
This year there's one more twist. RBI raised the repo rate on 7 October, from 5.25% to 5.50%, the first hike since February 2023. Banks passed it on within days. SBI moved its external benchmark lending rate from 7.90% to 8.15% from 15 October, and its home loan starting rate went from 7.25% to 7.50%. So this festive season, the offers are sitting on top of rates that just went up.
Here's how I'd read them.
The one number that matters more than any festive offer
Let's take a ₹50 lakh home loan for 20 years.
A full processing fee waiver on that loan saves you somewhere between ₹17,700 and ₹29,500. SBI's fee is 0.35% capped at ₹15,000, which comes to ₹17,700 with GST. A lender charging 0.50% plus GST, like HDFC Bank or ICICI Bank, would take ₹29,500.
Now see what a small difference in the interest rate does on the same loan.
| Rate higher by | EMI higher by | Extra interest over 20 years |
|---|---|---|
| 0.05% | ₹153 | ₹36,655 |
| 0.10% | ₹306 | ₹73,508 |
| 0.25% | ₹768 | ₹1.84 lakh |
| 0.50% | ₹1,542 | ₹3.70 lakh |
So picture two offers:
- Bank A: 7.50%, normal processing fee of ₹17,700
- Bank B: 7.75%, zero processing fee, "festive special"
Bank B looks better on the poster. Over 20 years it costs you about ₹1.67 lakh more. Even if you sell or switch after 5 years, you'd have paid around ₹62,000 more in interest by then. That's more than three times the fee you "saved".
The fee is paid once. The rate is paid every month for 20 years. Always compare the rate first.
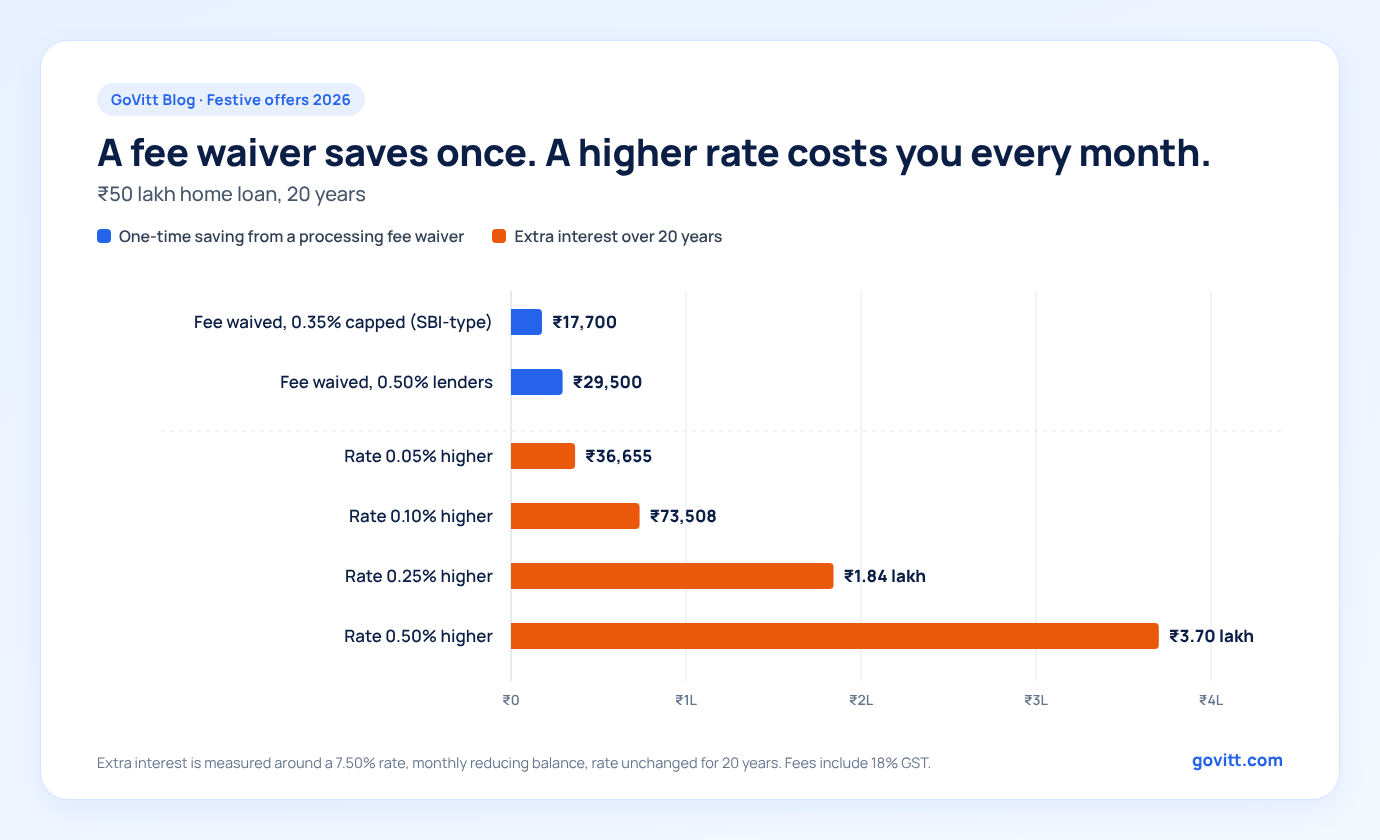
Even a 0.05% difference in rate costs more than the biggest fee waiver.
What's actually on offer this season
Here's what banks had announced for home loans as of 16 October, going by reports in Business Standard and Upstox, and the banks' own rate pages.
| Lender | What they're offering | Valid till |
|---|---|---|
| Punjab National Bank (PNB Utsav Festivities 2026) | Processing, upfront and documentation charges fully waived on home loans, plus a 0.05% rate concession. Existing PNB home loan customers get 0.10% off on mortgage loans, including top-ups. On home loan takeovers of ₹25 lakh and above, PNB bears legal, valuation and NEC charges up to ₹15,000 (plus GST). | 31 December |
| Kotak Mahindra Bank | 50% off the processing fee, home loans included | Not stated |
| Yes Bank | 50% off the processing fee (reports don't say which loans) | Till Diwali |
| HDFC Bank (Festive Treats 2026) | Reported on 6 October as home loans "from 7.2%" | Campaign from 10 October |
| ICICI Bank | "Special" rates valid till 31 October: 8.75% for a credit score of 750 and above. Pre-approved digital home loans from 7.55% | 31 October |
| SBI | Festive concessions reported on personal, car and gold loans. Home loans not named. Starting home loan rate is 7.50% from 15 October | Not stated |
Two things about this table.
The HDFC number needs a second look. The 7.2% figure was reported a day before RBI's hike. HDFC Bank's own rate page today says repo rate plus 2.50% to 7.95%, which works out to 8.00% to 13.45% at the current repo rate. I'm not saying anyone is misleading you. I'm saying a banner, a news report and a rate page can show three different numbers in the same week, and only one number goes into your sanction letter.
And if you already have a home loan with some other bank, the PNB offer is the one I'd look at closely. More on that below.
Five ways a festive offer looks better than it is
1. "Rates from X%" is for the best profile, not necessarily for you.
The starting rate on every banner is for borrowers with the best credit score, usually 800 or 825 and above. Most lenders don't publish their full grid. LIC Housing Finance does, so let's use theirs. For a salaried borrower with a loan up to ₹1 crore:
| CIBIL score | Rate |
|---|---|
| 825 and above | 7.15% |
| 800 to 824 | 7.35% |
| 775 to 799 | 7.50% |
| 750 to 774 | 7.60% |
| 725 to 749 | 7.80% |
| 700 to 724 | 8.10% |
On ₹50 lakh for 20 years, someone with a 750 score pays about ₹3.29 lakh more interest than the person the banner is talking about. At 700, it's about ₹7 lakh more. Same lender, same festive season.
Check your score before you walk in, and ask for the rate for your score, not the starting rate. If your score is the problem, this post on how your CIBIL score moves your rate explains the slabs.
2. The concession might not last.
"0.10% off" sounds nice. Ask one question: is this concession built into my spread for the full tenure, or is it for a limited period?
On a repo-linked loan, your rate is the bank's benchmark plus a spread. If the discount sits inside the spread, it stays with you for the life of the loan. If it's a separate "festive concession" that drops off later, you'll find out at a reset you weren't expecting.
Whatever they tell you, it should show up in two places: the sanction letter and the Key Fact Statement. Every lender has to give you a KFS before you sign. It shows the annual percentage rate (APR), which counts the fees along with the interest.
3. The processing fee is waived. The rest isn't.
A processing fee waiver doesn't touch the legal and valuation fees (₹5,000 to ₹15,000, unless the bank says it'll bear them), CERSAI and small charges, or the stamp duty.
In Karnataka, the stamp duty on the mortgage document (MODT) is 0.5% of the loan amount. That's ₹25,000 on ₹50 lakh, plus around ₹5,000 in registration. It's a government charge. No bank can waive it, festive or not.
So a "zero cost" home loan in Bengaluru doesn't really exist. Plan for at least ₹30,000 even with the best offer. The full list is in our post on balance transfer charges, and most of it applies to a new loan too.
4. Insurance quietly gets added into the loan.
At sanction, a lot of lenders push a home loan protection plan and add the single premium into your loan amount. Say the premium is ₹50,000. Financed at 7.50% over 20 years, you end up paying about ₹96,700 for it, of which about ₹46,700 is interest. In Karnataka you also pay 0.5% stamp duty on that ₹50,000, because it's now part of the loan.
Neither RBI nor IRDAI makes this insurance compulsory. If you need cover, a simple term plan is often cheaper. We've written about how home loan insurance actually works if you want the details.
5. "Lock in a fixed rate before rates rise" costs you more today.
With rates going up, some of you will be shown fixed rate offers. ICICI Bank's fixed rate for the first 24 months is 9.10% to 9.15%, while its floating rate starts at 8.75%. That gap is the price of certainty. Fixed rate loans can also carry switch and foreclosure charges that floating loans don't. Kotak's rate page says this plainly. Read our post on fixed vs floatingbefore you lock anything.
Already have a home loan? This is the offer to look at
Most festive offers are written for people buying a new house. But some of the best ones are for people moving an existing loan from another bank, and nobody advertises that part very loudly.
Here's why it matters. A normal balance transfer of ₹50 lakh in Bengaluru costs roughly ₹53,700 to ₹76,500 once you add up the processing fee, legal and valuation, MODT, registration and the small charges. With a PNB style festive offer, where the processing fee is waived and the bank bears legal and valuation up to ₹15,000, you're left mostly with the stamp duty and registration. That's around ₹31,000 to ₹32,000.
Say you're paying 8.75% today on ₹50 lakh with 20 years left, and a new lender gives you 7.50% (only if your profile actually gets you that rate, don't assume it):
- Your EMI comes down by ₹3,906 a month
- Total interest over the loan falls by about ₹9.37 lakh
- You get the charges back in about 8 months with a festive waiver, versus 14 to 20 months without one
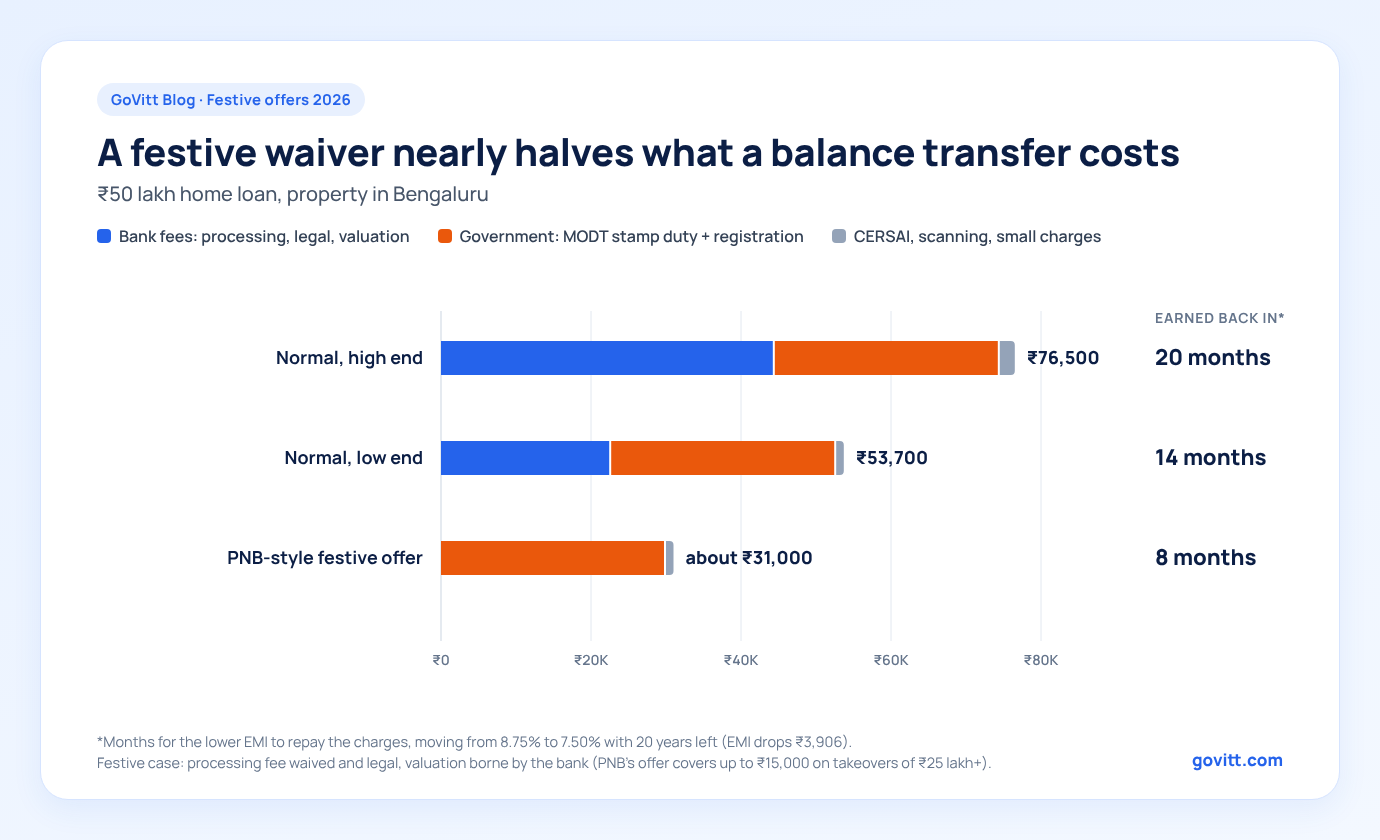
The waiver removes the bank's fees. The stamp duty stays, festive season or not.
That's the festive offer that actually changes your finances. Not the ₹17,700.
If your rate is above 8.75% after this hike, here's the full math with charges. And ask your own bank to match the new-customer rate first. If they say yes, it's cheaper than switching.
Before you sign anything this Diwali
- Check your CIBIL score first, so you know which rate slab you fall in.
- Ask for the rate for your profile, in writing. Not the banner rate.
- Ask what your spread over the benchmark is, and whether the festive concession is part of it.
- Get the Key Fact Statement and look at the APR, not just the interest rate.
- Ask for every charge in writing: processing, legal, valuation, MODT, CERSAI, insurance.
- Say no to bundled insurance unless you actually want it.
- Don't rush because the poster says "till Diwali". PNB's offer runs till 31 December, and banks often extend these.
If you're buying a flat this festive season, also read what I'd check on builder offers in Bengaluru. And if your bank app is flashing a pre-approved personal loan for Diwali shopping, read this first.
Should you wait for rates to come down?
I wouldn't plan around it. In October, RBI changed its stance to "calibrated tightening", which it says takes rate cuts off the table for the near term. The next policy meeting is on 2 to 4 December. SBI Research expects the repo rate to reach 6% by December, though not everyone agrees with that.
If you need a house now, buy when the house and the loan both make sense for you. On a floating rate, your rate moves with the market anyway. What you do control is the spread you start with. That's the number to fight for this festive season.
Want us to check an offer for you?
Got an offer from your bank or a builder's tie-up lender? Send us a screenshot on WhatsApp at +91 70194 17854 and we'll tell you what it really costs over the full loan, and whether a better rate is available to you. GoVitt compares offers from 50+ banks and housing finance companies, and we don't charge you any commission. You can also compare current rates here.
Offers and rates are as reported or published up to 16 October 2026 and can change without notice. Your actual rate depends on your credit score, income, loan amount and property. EMI and interest figures assume a ₹50 lakh loan for 20 years on monthly reducing balance, with the rate unchanged for the full tenure. Please confirm all terms with the lender before signing.
Questions people usually ask
Which banks have festive home loan offers in 2026? As of 16 October 2026, PNB is waiving processing, upfront and documentation charges on home loans till 31 December, with a 0.05% rate concession. Kotak Mahindra Bank and Yes Bank have announced 50% processing fee waivers. HDFC Bank's Festive Treats campaign started on 10 October. Offers change often, so check with the lender before applying.
Is a zero processing fee home loan worth it? Only if the interest rate is also competitive. On a ₹50 lakh loan for 20 years, a processing fee waiver saves ₹17,700 to ₹29,500. A rate just 0.25% higher costs about ₹1.84 lakh more in interest over the same period.
Can I get a festive offer on a home loan balance transfer? Yes, some lenders extend festive offers to takeovers. PNB, for example, waives processing charges and bears legal, valuation and NEC charges up to ₹15,000 (plus GST) on home loan takeovers of ₹25 lakh and above. Stamp duty on the new mortgage still applies.
Do festive rate concessions last for the full loan tenure? Not always. Ask whether the concession is part of your spread over the benchmark, which stays for the life of the loan, or a limited period discount. Check that it appears in the sanction letter and the Key Fact Statement.
What charges can't be waived on a home loan in Karnataka? The stamp duty on the mortgage document (MODT), which is 0.5% of the loan amount, and the registration fee of about 0.1%. These are government charges, so no bank offer can remove them.
Should I take a home loan now or wait for rates to fall? RBI moved to a "calibrated tightening" stance in October 2026, which signals no rate cuts in the near term. If the house and the loan make sense now, waiting for a cut isn't a reliable plan. Focus on getting the lowest spread you can, since a floating rate moves with the market anyway.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.