
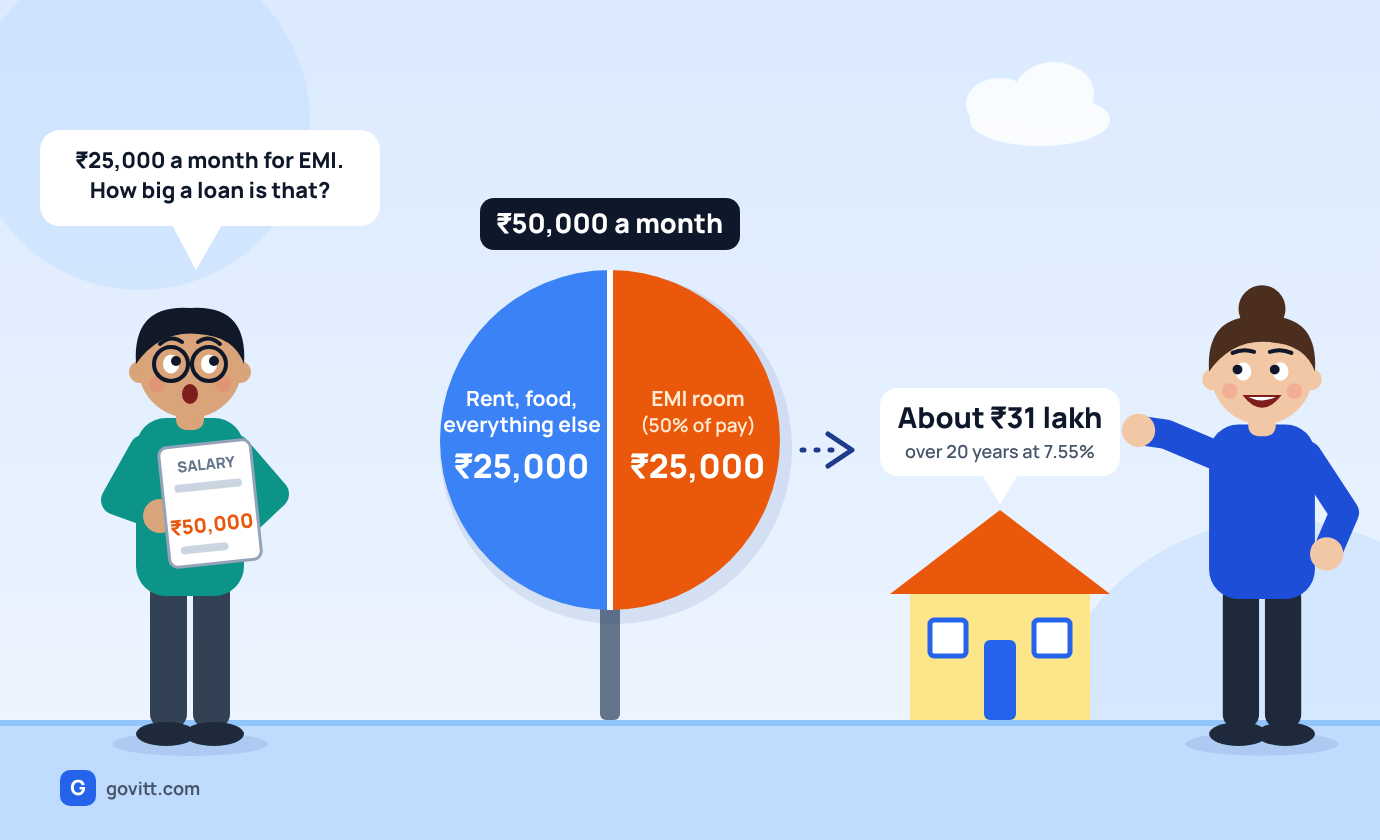
On a ₹50,000 monthly salary, most banks will lend you about ₹25 lakh to ₹36 lakh for a home loan. A rough working figure is ₹31 lakh over 20 years at today's lowest rates, or ₹35 to ₹36 lakh over 30 years. Your existing EMIs, your credit score, and whether you add a co-applicant can move that number a lot.
Why a range? Banks run two tests, and the lower one wins. One looks at how much of your income can go to EMIs. The other, at some banks, is a multiple of your salary. Below, the numbers for each, then what changes them.
For the full basics on how lenders decide, start with home loan eligibility: how banks work it out.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
Home loan on ₹50,000 salary at a glance (checked 24 October 2026)
| Item | What to expect |
|---|---|
| Typical loan, 20 years, no other EMIs | About ₹25 to ₹35 lakh |
| Typical loan, 30 years, no other EMIs | About ₹28 to ₹40 lakh |
| Working figure | About ₹31 lakh (20 years) or ₹35.6 lakh (30 years) at 7.55% |
| EMI affordable | About ₹20,000 to ₹27,500 a month (40% to 55% of salary) |
| Salary multiple at Canara | 72 times gross monthly salary is ₹36 lakh (96 times selectively is ₹48 lakh) |
| Repo rate | 5.50% since 7 October 2026 |
The two tests banks run
Test 1: how much EMI can your income carry? Banks cap your total fixed obligations (all EMIs, including the new home loan) as a share of your income. This is FOIR. Many lenders use about 40% to 55% of income, with lower incomes getting the lower end. Each bank sets its own.
On ₹50,000 that works out to:
| FOIR used | Monthly EMI you can carry |
|---|---|
| 40% | ₹20,000 |
| 50% | ₹25,000 |
| 55% | ₹27,500 |
Test 2: a multiple of your salary. Some banks publish a cap as a multiple. Canara allows up to 72 times last drawn gross monthly salary for salaried borrowers, and selectively up to 96 times. On ₹50,000 gross, that is ₹36 lakh, or up to ₹48 lakh selectively.
Take whichever is lower. Here, the income test usually decides, because ₹31 lakh is below ₹36 lakh.
How much loan does ₹50,000 buy?
The loan below is what the EMI affordable at each FOIR level can repay at 7.55%, the lowest Canara rate for a loan up to ₹50 lakh.
| FOIR used | EMI | Loan over 20 years | Loan over 30 years |
|---|---|---|---|
| 40% | ₹20,000 | ₹24.7 lakh | ₹28.5 lakh |
| 50% | ₹25,000 | ₹30.9 lakh | ₹35.6 lakh |
| 55% | ₹27,500 | ₹34.0 lakh | ₹39.1 lakh |
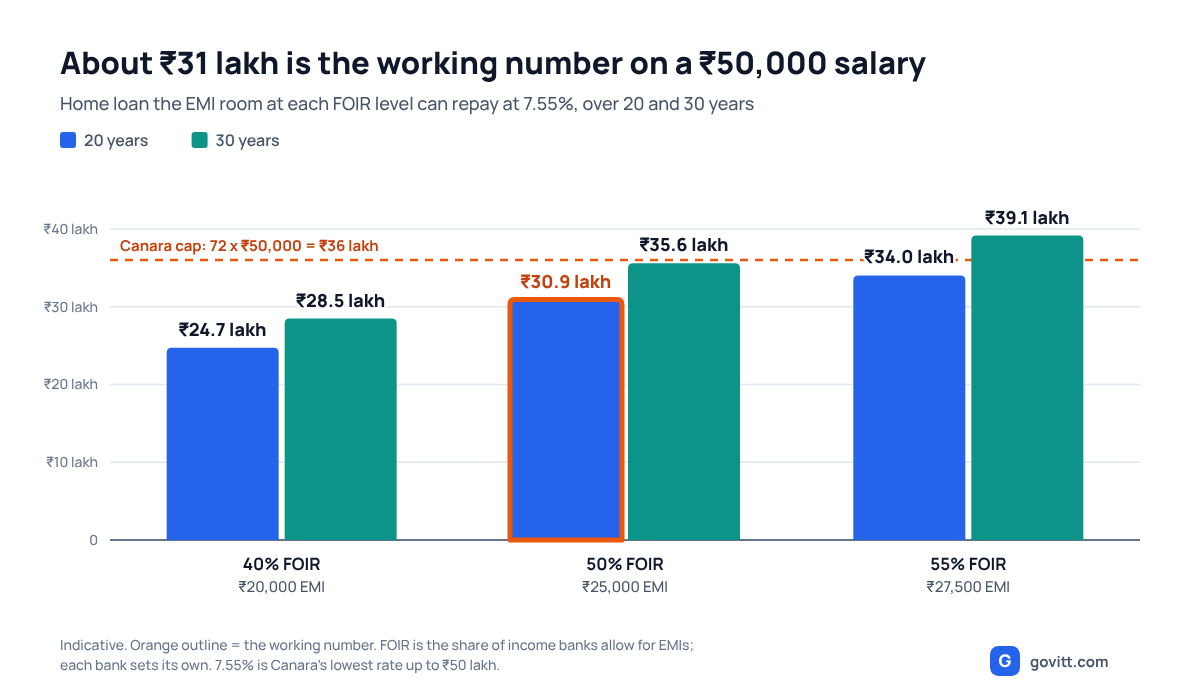
If your bank uses 50%, plan on about ₹31 lakh over 20 years. If it lets you go to 55%, it is about ₹34 lakh. A 30 year tenure adds roughly ₹4.5 to ₹5 lakh, but I'll show you the cost of that below.
Figures are indicative. Your bank's own FOIR and your actual salary definition will decide.
Bank by bank: how the rate changes your loan
Your loan size depends on the rate your bank gives you. At a 50% FOIR (₹25,000 a month):
| Bank and rate | Loan over 20 years | Loan over 30 years |
|---|---|---|
| SBI, lowest published rate 7.50% | ₹31.0 lakh | ₹35.8 lakh |
| Canara, 7.55% (top grade, up to ₹50 lakh) | ₹30.9 lakh | ₹35.6 lakh |
| HDFC Bank, lowest published rate 8.00% | ₹29.9 lakh | ₹34.1 lakh |
| ICICI Bank, table rate 8.75% | ₹28.3 lakh | ₹31.8 lakh |
These are each bank's best published rate. You will only get it with a strong profile. At a weaker grade, the loan shrinks. Canara's CRG 3 rate is 8.75%, for example, which gives ₹28.3 lakh over 20 years on the same salary.
For full rate details, see our posts on SBI, HDFC Bank and ICICI Bank. The difference between the best and a mid-range bank here is about ₹2.7 lakh of loan, so the bank you choose changes what you can afford.
What existing EMIs do to your eligibility
This is the biggest swing. Every rupee of EMI you already pay comes out of your FOIR room.
At 50% FOIR, 7.55%, 20 years:
| Existing EMIs | Left for home loan EMI | Home loan you can get |
|---|---|---|
| None | ₹25,000 | ₹30.9 lakh |
| ₹2,000 | ₹23,000 | ₹28.4 lakh |
| ₹5,000 | ₹20,000 | ₹24.7 lakh |
| ₹8,000 | ₹17,000 | ₹21.0 lakh |
A ₹5,000 car or personal loan EMI cuts your eligible home loan by about ₹6 lakh. Credit card dues and BNPL accounts are checked too, even if you pay them on time.
20 years or 30 years: the real cost
A longer tenure raises your loan amount, but it can cost you far more in interest. Take a ₹30 lakh loan at 7.55%:
| Tenure | EMI | Share of ₹50,000 salary | Total interest |
|---|---|---|---|
| 20 years | ₹24,260 | 48.5% | ₹28.22 lakh |
| 30 years | ₹21,079 | 42.2% | ₹45.89 lakh |
The 30 year loan cuts your EMI by ₹3,181 but costs ₹17.7 lakh more in interest. If your income will grow, take the longer tenure now and prepay when you can. Floating rate home loans to individuals have no prepayment charge.
How to raise your eligibility on ₹50,000
- Add a co-applicant with income. A spouse or parent earning ₹30,000 takes combined income to ₹80,000, and the loan at 50% FOIR to about ₹49.5 lakh over 20 years or ₹56.9 lakh over 30 years. Both incomes and both credit histories are checked.
- Close small loans first. Clearing a ₹5,000 EMI loan before you apply lifts your eligibility by about ₹6 lakh.
- Improve your credit score. A score of 750 or more unlocks the lowest rates. See how a CIBIL score moves your rate.
- Show all your income. Variable pay, incentives and rental income may be counted by some banks if they appear in your bank statements and tax returns.
- Choose a longer tenure if you need the amount, and plan to prepay later.
- Make a bigger down payment. The loan only covers part of the property, so a larger down payment means you can afford a costlier home than the loan figure alone suggests.
What property can you buy?
Banks lend a share of the property value and you pay the rest. At Canara, for example, you put in at least 10% for a property up to ₹30 lakh and at least 20% above that (up to ₹75 lakh). So a loan of ₹31 lakh supports a property of about ₹39 lakh, before registration and other costs.
In Bengaluru that is a small flat, usually outside the core. If your target is higher, the answer is a co-applicant or a bigger down payment, not a longer tenure alone.
Compare before you sign
Two banks can give you very different loan amounts on the same ₹50,000 salary. Before you apply, compare rates from 50+ banks and see what your profile qualifies for. GoVitt charges you 0% commission.
FAQ
How much home loan can I get on a ₹50,000 salary? Usually about ₹25 to ₹36 lakh. At 7.55% with a 50% FOIR and no other EMIs, you can service about ₹30.9 lakh over 20 years or ₹35.6 lakh over 30 years. The exact figure depends on your bank's FOIR, rate and your existing EMIs.
What EMI can I afford on a ₹50,000 salary? Banks usually allow total EMIs of 40% to 55% of income, which is ₹20,000 to ₹27,500 a month on ₹50,000. Keep your own comfort in mind. An EMI at the top of that range leaves little room for emergencies.
Does Canara Bank lend by salary multiple? Yes. Canara allows salaried borrowers up to 72 times gross monthly salary, and selectively up to 96 times. On ₹50,000 that is ₹36 lakh or ₹48 lakh. Your income, EMIs and credit grade can lower it.
Can I get a home loan on a ₹50,000 salary with a personal loan running? Yes, but the loan is smaller. A ₹5,000 monthly EMI reduces the home loan you qualify for by about ₹6 lakh.
Will a co-applicant increase my loan amount? Yes. Banks add the co-applicant's income, so the combined income is used for the EMI test. Both credit scores are checked.
Is it better to take a 20 year or 30 year loan? A 30 year loan lowers the EMI and raises the amount you can borrow, but it costs more interest. On ₹30 lakh at 7.55%, the extra interest is ₹17.7 lakh. If your income will grow, a longer tenure with prepayments gives you flexibility.
Rates as of 24 October 2026: SBI 7.50%, Canara 7.55%, HDFC Bank 8.00% and ICICI Bank 8.75% are each bank's lowest or table rate as published, and apply only to strong profiles. FOIR levels are indicative. Banks set their own limits, so your result will differ. EMIs use the standard monthly reducing balance method. We will update this page after the 4 December 2026 MPC decision.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.