
The ICICI home loan interest rate today is 8.75% to 10.05% on floating rate loans, going by ICICI Bank's own rate table. The bank's headline says "from 7.80%". That rate is real, but it's only for customers with a pre-approved offer who apply through ICICI's digital journey.
That gap matters. On a ₹50 lakh loan over 20 years, 7.80% and 8.75% are ₹2,984 a month apart. That's ₹7.16 lakh over the loan.
ICICI's rates are linked to the repo rate, which RBI raised to 5.50% on 7 October. ICICI shows the new repo rate as effective from 8 October, and marks its current rates valid till 31 October 2026.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
Below: what ICICI will actually charge you, every fee, and when to switch to or away from it.
ICICI home loan rates at a glance (checked 21 October 2026)
| Item | What ICICI Bank shows |
|---|---|
| Floating rate, salaried | 8.75% to 9.90% |
| Floating rate, self-employed | 8.75% to 10.05% |
| Pre-approved, digital journey | From 7.80%, subject to credit score |
| Fixed rate, 3 or 5 years | 8.90% to 9.15% |
| Fixed for the full term | 10.90% to 11.20% |
| Benchmark | Repo rate, 5.50% from 8 October 2026 |
| Processing fee | 0.50% of the loan amount, plus taxes |
Your ICICI rate by CIBIL score
Unlike most private banks, ICICI publishes a small credit score grid. Here it is, with the EMI on a ₹50 lakh loan over 20 years:
| Your profile | ICICI rate | EMI on ₹50 lakh, 20 years |
|---|---|---|
| Pre-approved, applying digitally | From 7.80% | ₹41,202 |
| Credit score 800, salaried or self-employed | 8.75% | ₹44,186 |
| Credit score 750 to 800, salaried | 8.75% | ₹44,186 |
| Credit score 750 to 800, self-employed | 8.85% | ₹44,505 |
| Below 750 | Standard rates, up to 9.80% for a ₹35 to ₹75 lakh loan (salaried) | Up to ₹47,590 |
Two things stand out. For salaried borrowers, a score of 800 gets the same 8.75% as a score of 750. And self-employed borrowers pay the same as salaried ones at 800, and only 0.10% more between 750 and 800.
If your score is below 750, fix that before you apply. I showed how much a score band can move your rate in RBI moved your home loan rate by 0.25%. Your CIBIL score can move it by 1.80%.
Standard rates by loan amount
| Loan amount | Salaried | Self-employed |
|---|---|---|
| Up to ₹35 lakh | 8.75% to 9.65% | 8.75% to 9.80% |
| ₹35 lakh to ₹75 lakh | 8.75% to 9.80% | 8.75% to 9.95% |
| Above ₹75 lakh | 8.75% to 9.90% | 8.75% to 10.05% |
How ICICI compares
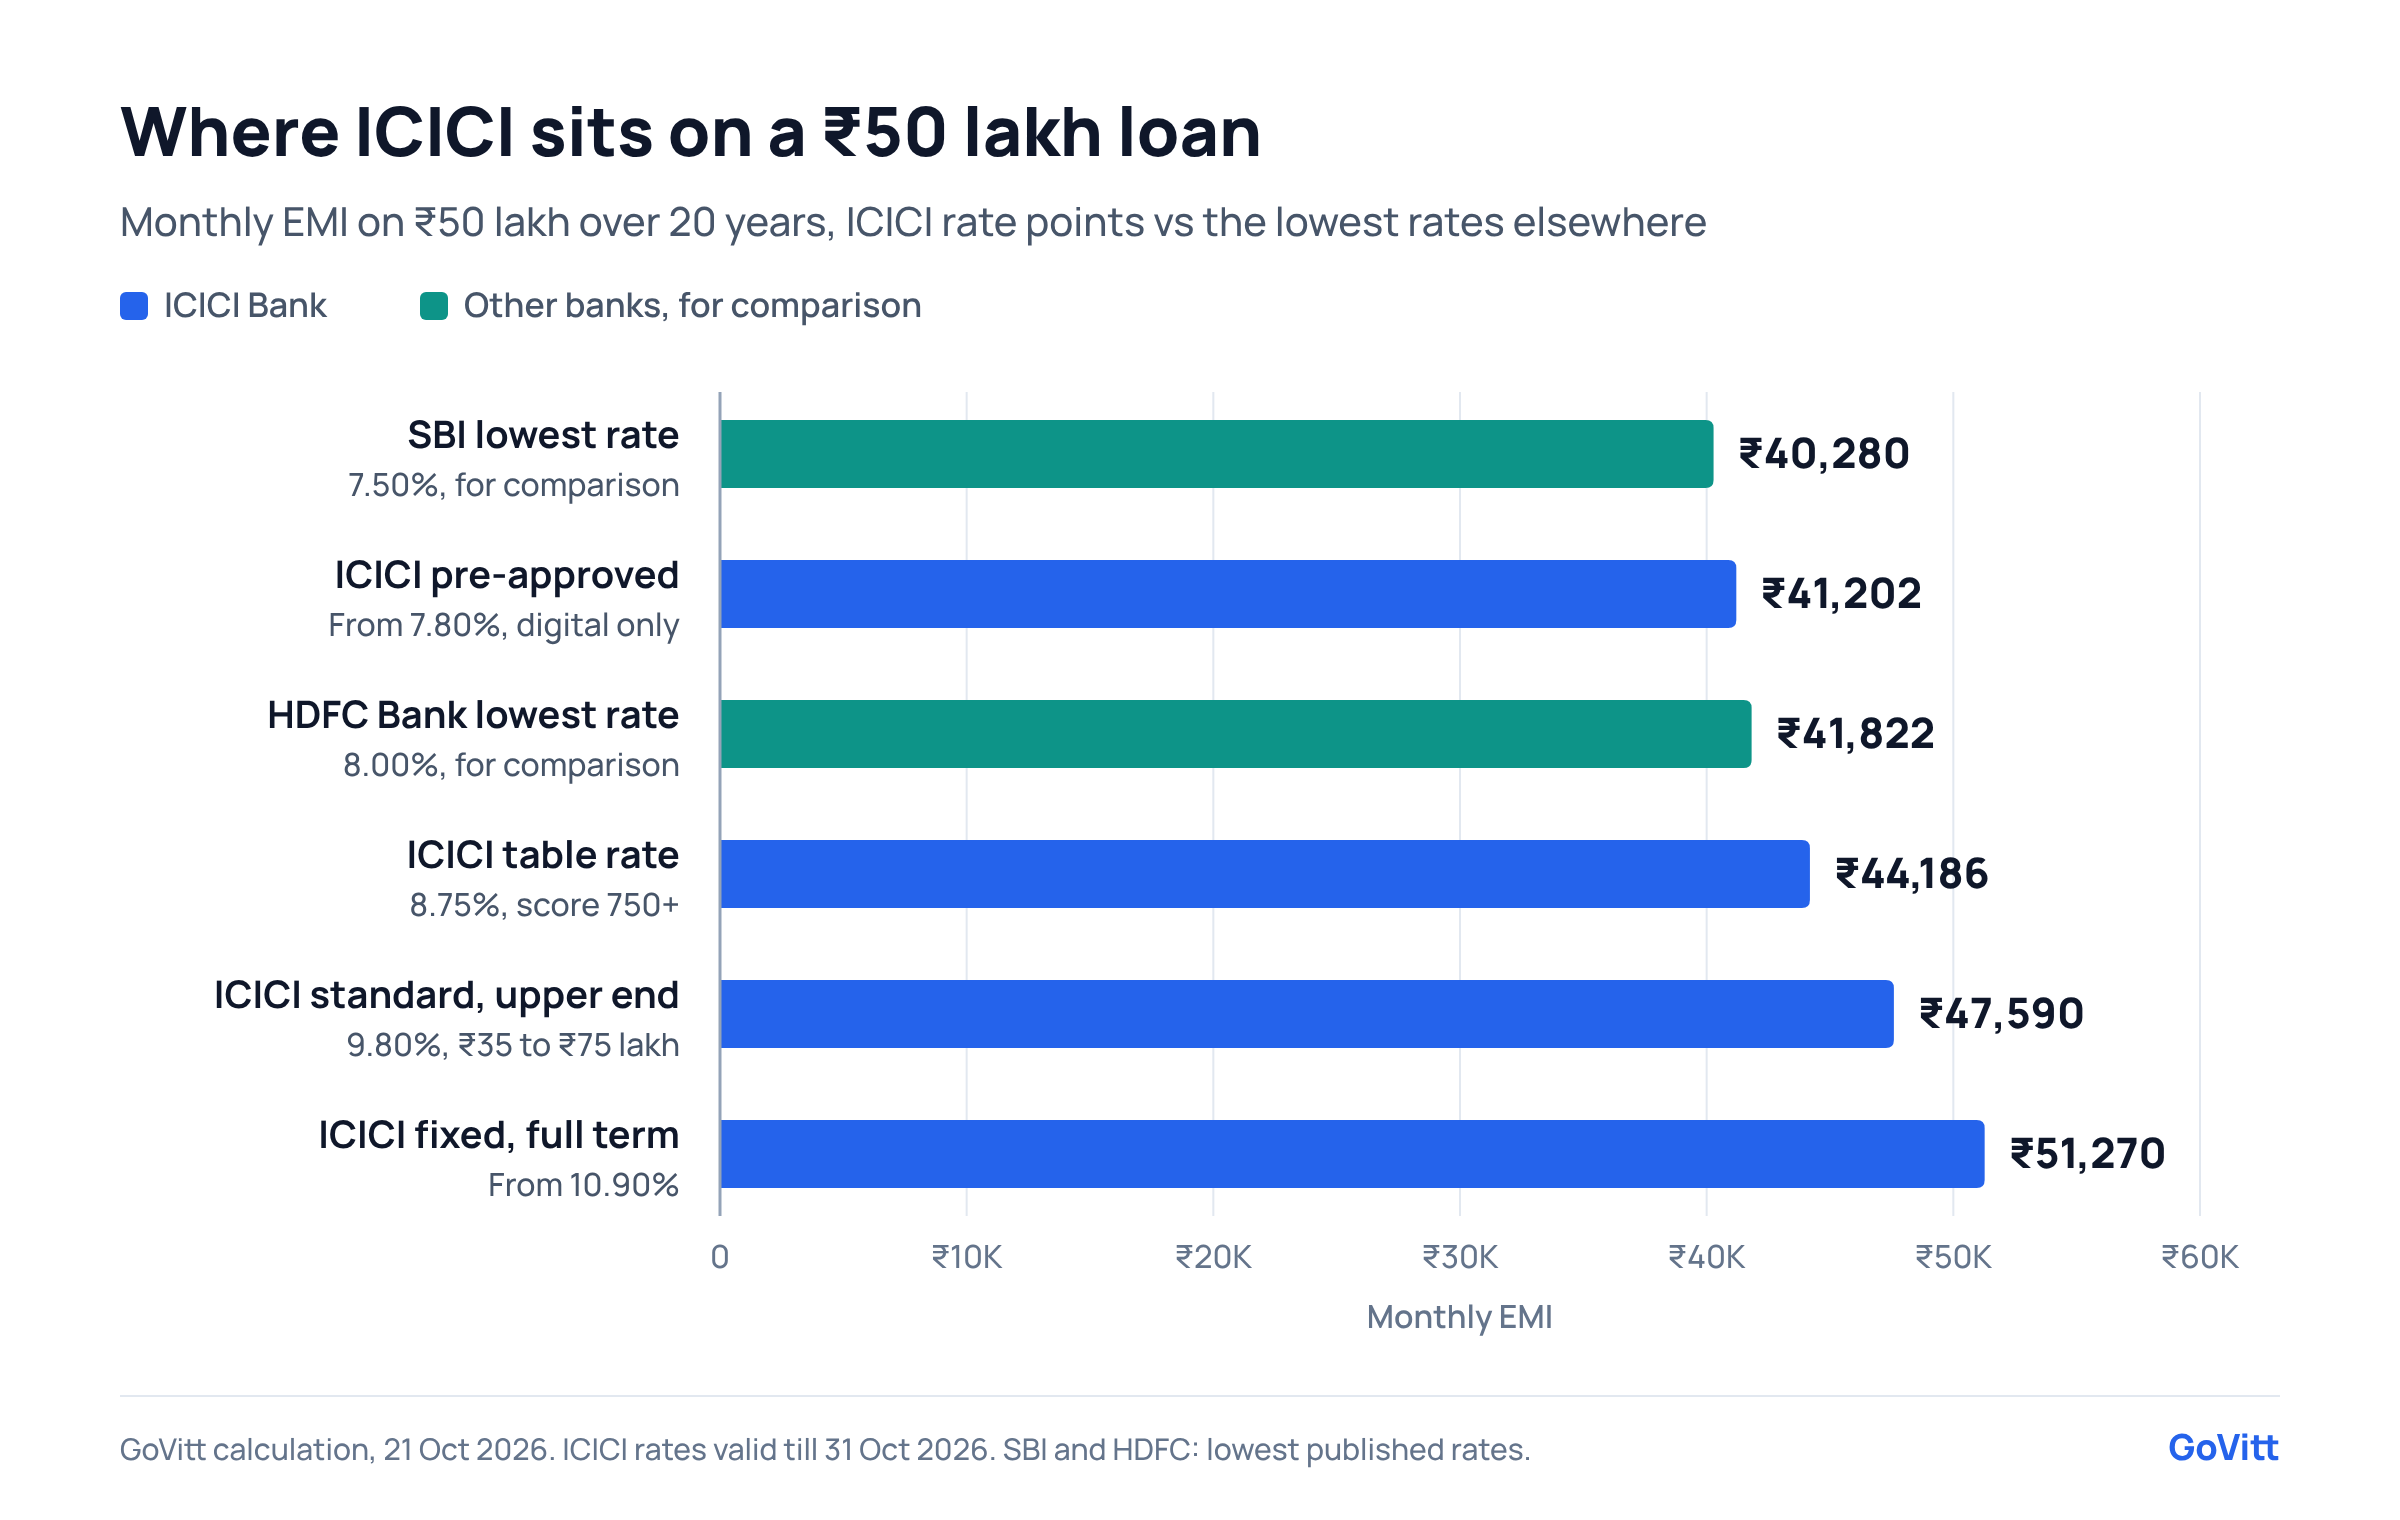
ICICI's table rate of 8.75% sits well above the lowest published rates at SBI (7.50%) and HDFC Bank (8.00%). On ₹50 lakh over 20 years, 8.75% costs ₹3,906 a month more than SBI's lowest rate, and ₹2,364 more than HDFC's.
The digital pre-approved rate of 7.80% changes that picture. If you have one, it's competitive. If you don't, ICICI is one of the pricier big banks right now. See today's rates across 50+ lenders on our rate comparison page.
The fixed rate option
ICICI publishes a full menu of fixed rate home loans:
| Fixed for | Rate | 24 months |
|---|---|---|
| 9.10% to 9.15% | 37 months | 8.90% to 9.15% |
| 60 months | 8.90% to 9.15% | 120 months |
| 10.75% to 10.85% | Full term | 10.90% to 11.20% |
With RBI now in "calibrated tightening" mode, a 3 or 5 year fixed rate at 8.90% can look tempting. It's only about ₹480 a month more than 8.75% floating on ₹50 lakh. But read the fine print first:
- Prepaying a fixed rate loan costs 2% of the amount prepaid, for loans sanctioned on or after 1 January 2026. Floating rate loans have no prepayment charge.
- Moving from fixed to floating costs 2% of the outstanding principal. On ₹50 lakh that's ₹1.18 lakh with GST.
So a fixed rate makes sense only if you're sure you won't prepay or switch during the fixed period.
ICICI home loan fees and charges
| Fee | Amount | On ₹50 lakh |
|---|---|---|
| Processing fee | 0.50% of the loan amount, plus taxes | ₹29,500 with GST |
| Administrative charge | 0.25% or ₹5,000, whichever is lower, plus taxes | ₹5,900 with GST |
| Conversion to a lower floating rate (existing borrowers) | ₹3,000, plus taxes | ₹3,540 with GST |
| Fixed to floating | 2% of principal outstanding | ₹1,18,000 with GST |
| Prepayment, floating rate | Nil | ₹0 |
| Prepayment, fixed rate | 2% of the amount prepaid | Depends on the amount |
| Late payment | 5% a year on the overdue amount | Depends on the delay |
ICICI's ₹3,000 conversion fee is one of the cheapest among big banks. That's good news if you're already an ICICI borrower.
Balance transfer to ICICI, and top-up
- Eligibility: ICICI asks for a CIBIL score of 700 or above for a balance transfer, along with a good repayment record.
- Rate: ICICI doesn't publish a separate balance transfer rate. Expect the same rate table as a new loan.
- Top-up: up to 100% of your original sanctioned amount, for up to 20 years, subject to the property's value and your income. ICICI doesn't publish the top-up rate, so get it in writing.
Before you add a top-up to any transfer, check what a long tenure does to its real cost. A top-up stretched over 15 years can cost more than a personal loan.
Who ICICI suits, and who should look elsewhere
ICICI can make sense if you:
- Have a pre-approved digital offer near 7.80%
- Are self-employed with a strong score. ICICI's self-employed rates are close to its salaried ones
- Want a 3 or 5 year fixed rate and are sure you won't prepay in that time
- Bank with ICICI already and value one relationship for salary, cards and loan
Look elsewhere first if you:
- Are salaried with a CIBIL score of 750 or more and no pre-approved offer. SBI starts at 7.50% and HDFC Bank at 8.00%
- Plan to prepay aggressively and were thinking about a fixed rate
Already with ICICI? Whether to switch
Here's a worked example. Say you have:
- ₹50 lakh outstanding
- 18 years (216 EMIs) left
- A current rate of 9.25%, so an EMI of ₹47,606
| Option | Cost | Monthly saving | Net saving over 18 years | Cost paid back in |
|---|---|---|---|---|
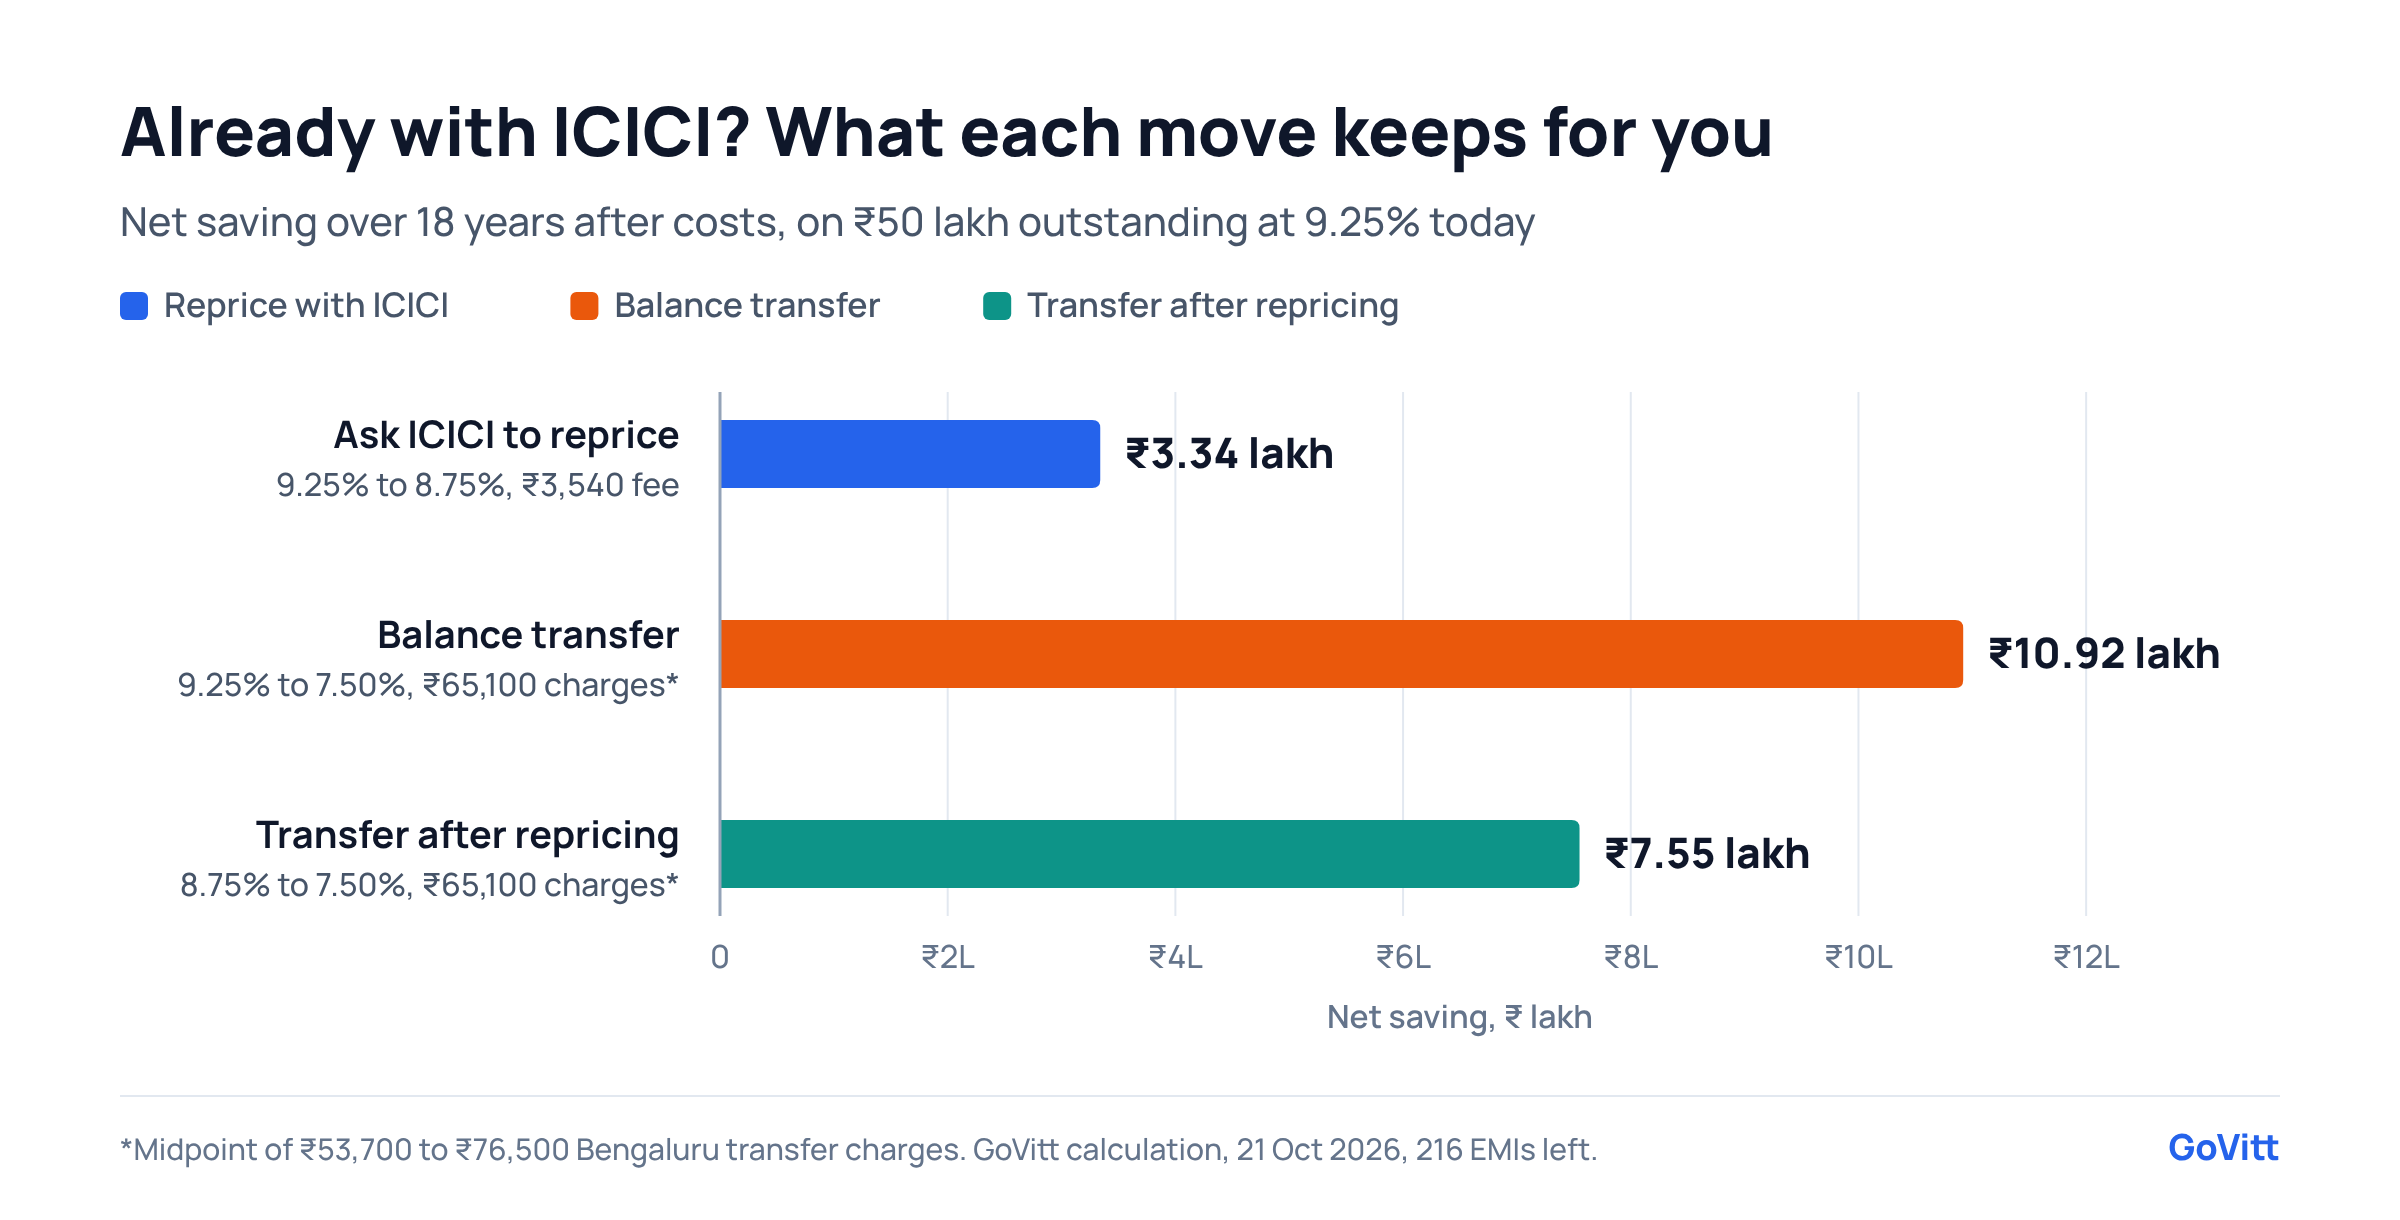
| Ask ICICI to move you to 8.75% | ₹3,540 | ₹1,561 | ₹3.34 lakh | About 2 months |
| Transfer to a lender at 7.50% | ₹53,700 to ₹76,500 | ₹5,357 | ₹10.81 lakh to ₹11.03 lakh | 10 to 14 months |
| Transfer after ICICI cuts you to 8.75% | ₹65,100 (midpoint) | ₹3,796 | ₹7.55 lakh | About 17 months |
What this tells you:
- Ask ICICI first. At ₹3,540, the conversion pays for itself in about two months. Put the request in writing, with the rate you've seen for your credit score.
- Then compare. ICICI's table rate is 1.25% above SBI's lowest. If you can get 7.50% elsewhere with many years left, a transfer still wins even after ICICI cuts your rate. Every transfer charge is broken down in home loan balance transfer charges.
- On a fixed rate? Check the 2% switch and prepayment charges before you do anything.
The full process for moving your loan is on our home loan balance transfer page.
Compare before you sign
ICICI's best rate depends on whether you're pre-approved. Before you accept any offer, compare rates from 50+ banksand see what your profile qualifies for. GoVitt charges you 0% commission.
FAQ
What is the ICICI home loan interest rate today? As of 21 October 2026, ICICI Bank's floating home loan rates are 8.75% to 9.90% for salaried borrowers and 8.75% to 10.05% for self-employed borrowers. Pre-approved customers applying digitally can get rates from 7.80%. ICICI marks these rates valid till 31 October 2026.
What is ICICI's home loan rate for a CIBIL score of 750 or 800? 8.75% for salaried borrowers with a score of 750 or above, and for self-employed borrowers with a score of 800. Self-employed borrowers with a score between 750 and 800 pay 8.85%.
Why is ICICI's advertised rate lower than its rate table? The "from 7.80%" headline applies only to pre-approved home loans taken through ICICI's digital journey, subject to your credit score. Its published rate table for other borrowers starts at 8.75%.
What is ICICI's home loan processing fee? ICICI's rate page shows 0.50% of the loan amount plus taxes. There's also an administrative charge of 0.25% or ₹5,000, whichever is lower, plus taxes, at disbursement.
Can I lower my ICICI home loan rate without switching banks? Yes. ICICI charges ₹3,000 plus taxes to convert a floating rate loan to a lower floating rate. Moving from a fixed rate to floating costs 2% of the outstanding principal.
Rates and fees as of 21 October 2026, from ICICI Bank's home loan interest rates and service charges pages. EMIs use the standard monthly reducing balance method. Rates change after
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.