Every year around June and July, I get some version of this message: "I have two home loans now, so that's 2 lakh on each, right?"
No. And people usually ask me twice, because the first answer isn't the one they wanted.
The confusing part is that the answer isn't a flat no either. You can claim on both loans. It's just that how much you get depends almost entirely on one thing, and it isn't the number of loans. It's what you do with the second house.
See your real payoff date in 60 seconds
Banks calculate remaining EMIs by simple subtraction. See your actual payoff date and discover how much interest a balance transfer can save.
The law asks one question
Not "how many loans do you have." It asks what each house is being used for. Everything follows from that.
A house is self-occupied if you or your family live in it. That also covers a flat lying empty because you haven't been able to move in yet, and a flat where your parents stay rent free, as long as you're not already claiming another house as your own residence.
A house is let out if somebody pays you rent for it.
And then there's the category people forget, deemed let out. You own it, nobody's paying you rent, but it doesn't qualify as self-occupied either. Think of a third flat sitting locked. The department taxes you on a notional rent for it anyway, based on what it could reasonably fetch. You earn nothing and you still pay tax on it.
Since FY 2019-20 you're allowed to call two houses self-occupied. Before that it was one, and the second one automatically got the notional rent treatment, which people hated for good reason. So if you have exactly two houses, you're inside the limit and neither gets taxed on imaginary rent. From the third onwards, it's a problem.
Which two you declare as self-occupied is your choice at filing time, and that choice is worth thinking about rather than ticking whatever the software suggests.
If both houses are self-occupied
Two loans. One limit.
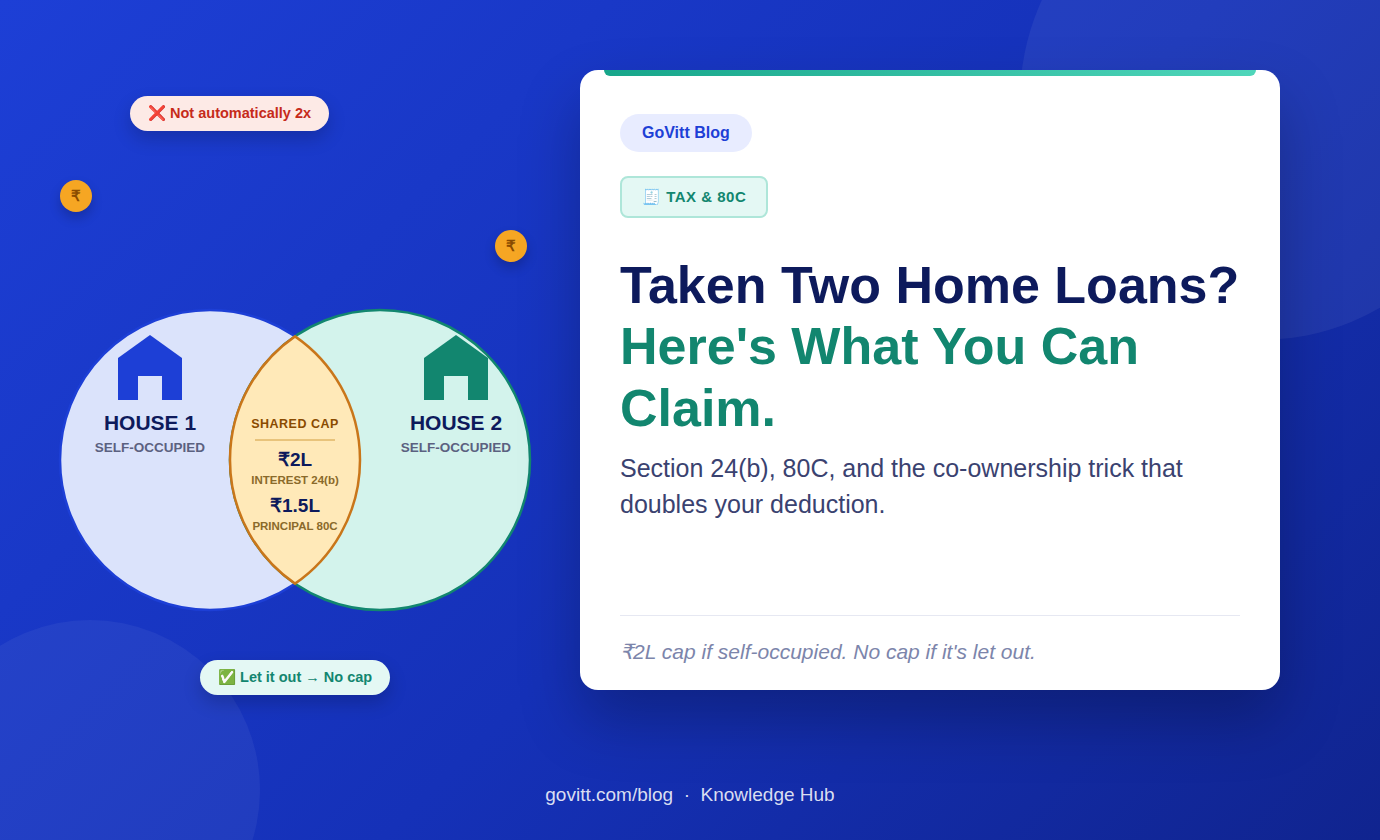
Section 24(b) caps your interest deduction at ₹2 lakh a year, and that ₹2 lakh is for you as a person, across every house you've called self-occupied. Not per house. Not per loan.
So if you paid ₹1,64,000 interest on the first loan and ₹2,90,000 on the second, your claim is ₹2 lakh. Not ₹4.54 lakh. The second loan bought you ₹36,000 of extra deduction, the gap between your first loan's interest and the ceiling, and nothing more.
Section 80C works the same way on the principal side. ₹1.5 lakh, combined across both loans, and it's the same ₹1.5 lakh you're already filling up with PF, life insurance premium, ELSS and your kids' tuition fees. For most salaried people the PF alone eats a good chunk of it. So the second loan's principal often adds up to exactly zero in tax terms, even though real money is leaving your account every month.
That's the honest version. If both your houses are self-occupied and your first loan was already a decent size, the second loan is not a tax play. Buy it because you want the house.
If the second one is rented out
Here it gets more interesting, and this is where most of the money people miss actually sits.
There's no cap on interest for a let-out property. None. Pay ₹6 lakh of interest in a year on a rented flat and all ₹6 lakh is deductible against that property's income. The ₹2 lakh ceiling you keep reading about simply doesn't apply to this bucket.
The calculation runs like this. Take the rent you received for the year. Knock off 30% as a standard deduction, which you get whether or not you spent anything on repairs. Then subtract the full interest. On a reasonably new loan, that number almost always lands in the negative, and a negative number under house property is a loss.
Now the catch, and it's a real one. The interest deduction has no ceiling, but the loss you can set off against your salary in the same year is capped at ₹2 lakh, and that ₹2 lakh is across all your properties put together, not per property.
Whatever's left over is not gone. It carries forward for eight assessment years. But in those future years it can only be adjusted against house property income, not against your salary. So it sits there waiting for a year when your rental income is higher or your interest has come down.
In my experience this carried-forward loss is the single most commonly abandoned deduction in the whole return. People file, they see ₹2 lakh got adjusted, they assume the rest lapsed, and they never claim it. It doesn't lapse. It just has to actually be recorded in the return, every year, to stay alive.
What that looks like with numbers
Say you're in Bangalore with a flat you live in, and a flat back home that's rented.
| Flat you live in | Flat you've rented out | |
|---|---|---|
| Interest paid this year | ₹2,80,000 | ₹3,50,000 |
| Interest you can actually claim | ₹2,00,000 | ₹3,50,000 |
| Rent received | Nil | ₹1,80,000 |
| Less 30% standard deduction | Nil | ₹54,000 |
| Net annual value | Nil | ₹1,26,000 |
| Loss from this property | ₹2,00,000 | ₹2,24,000 |
Combined loss for the year, ₹4,24,000. Of that, ₹2 lakh comes off your salary this year. The other ₹2,24,000 goes into carry forward and waits.
Principal was ₹1,30,000 on the first loan and ₹1,20,000 on the second, so ₹2.5 lakh went out. You can claim ₹1.5 lakh of it under 80C, and that's before your PF is counted. Realistically, if your PF and insurance already cross ₹1.5 lakh, the home loan principal contributes nothing at all here.
Total actually claimed this year: ₹5.5 lakh of interest and ₹1.5 lakh of principal, with ₹2.24 lakh banked for later.
The one people leave on the table
If a house is jointly owned and both owners are on the loan and both are genuinely paying the EMI, each of you claims separately in your own return, in proportion to your share. The caps are per person, not per property.
Take one house with ₹4 lakh of interest and ₹2 lakh of principal for the year, owned half and half by a couple who are both borrowers.
Claimed by one person, it's ₹2 lakh of interest and ₹1.5 lakh of principal. Total ₹3.5 lakh.
Split properly, each of them claims ₹2 lakh of interest, because each one's share of the interest is ₹2 lakh and that's exactly at their individual ceiling, plus ₹1 lakh each of principal. Total ₹6 lakh.
Same loan. Same house. Same money paid. ₹2.5 lakh more claimed, purely because both returns reflect reality instead of one person carrying the whole thing.
Two conditions, though, and both matter if it's ever questioned. You have to be a co-owner, not just a co-borrower added for eligibility. And the repayment should visibly come from both of you. If the full EMI leaves one person's account every month and the other one claims half anyway, that's a weak position to be in.
The filing bits nobody writes about
This is where two-loan returns actually go wrong, more often than the sections themselves.
Your employer computes TDS on your salary. Under Section 192(2B) you can report loss from house property to them, usually through Form 12BB along with the loan interest certificate, and they'll factor it into your monthly TDS. Most people do this for their self-occupied house and stop there. If you also have a rented property running a loss, that can go in too, up to the same ₹2 lakh. Skip it and you're just handing the government an interest-free loan until your refund arrives the following year.
Second, get the interest certificate from both lenders. Not the account statement, the provisional or final interest certificate, which splits principal and interest for the year. Banks put it in netbanking now, usually under a "home loan" or "tax certificate" tab, and if you're with a housing finance company you may have to ask for it.
Third, something that changed this year. For AY 2026-27, ITR-1 has been widened to cover up to two house properties, where earlier more than one house pushed you into ITR-2. So a straightforward two-property, two-loan salaried case may now fit in ITR-1, assuming you meet all the other ITR-1 conditions. But if you have a loss to carry forward, check the form carefully before you commit to it, because ITR-1 has never really been built to record carried-forward losses. Getting that wrong costs you the carry forward, which is exactly the thing worth protecting.
One more, slightly technical. Missing the filing deadline generally kills your right to carry losses forward, but house property loss is treated differently from business and capital losses on this point, and is usually still allowed even in a belated return. I would not rely on that as a plan. File on time.
If you've moved to the new regime
Then most of this doesn't apply to you.
No Section 24(b) on a self-occupied house. No 80C at all. The two houses you live in give you nothing.
Rented property is the exception. You can still set the interest off against the rent from that property, so the property's own income gets computed the same way. What you lose is everything after that. A loss can't come off your salary, and it can't be carried forward. It just reduces that property's income to nil and stops.
So for someone with two loans and serious interest going out, the regime choice isn't obvious and shouldn't be made on the basis that the new one has fewer forms. Run it both ways once. It takes an hour and it's the same answer for the next several years.
About 80EE and 80EEA
They come up in every search on this topic, so, briefly: both were tied to loan sanction windows that have closed. 80EE needed a sanction in roughly FY 2016-17 or FY 2017-18, on a loan under ₹35 lakh for a property under ₹50 lakh. 80EEA needed a sanction between April 2019 and March 2022 on a first home under ₹45 lakh.
If your loan was sanctioned recently, neither of these is available to you, whatever the article you read last week said. You're working with 24(b) and 80C.
Before you file
Pull both interest certificates. For each property write down interest for the year, principal for the year, whether it's self-occupied or rented, and the rent if there is any. Note whether each loan is single or joint, and whether the EMI actually debits from both accounts.
That's the whole input list. Ten minutes of work, and it's the difference between a return that's correct and one that quietly costs you a lakh or two over a few years.
If you're weighing up a second home loan right now, or wondering whether the rate on your existing one is still competitive before you add another EMI to it, that's what we do. WhatsApp us on +91 70194 17854, or run your numbers through our free Payoff & Transfer Calculator. GoVitt works with 50+ banks and housing finance companies, and we don't take a commission from you.
General information, not advice on your specific return. Tax treatment depends on your full income picture and these rules change with almost every Budget. Run it past a CA before you file.
Questions people usually ask
Can I claim tax benefits on two home loans at the same time? Yes, on both loans. But the ₹2 lakh interest limit for self-occupied houses and the ₹1.5 lakh limit under 80C apply to you as a person across both loans together, not separately for each one.
Is the ₹2 lakh home loan interest deduction per property or per person? Per person, combined across every house you've declared as self-occupied. Two self-occupied houses still share one ₹2 lakh limit.
What if my second house is rented out? Then there's no limit on the interest you can claim against that property. If it works out to a loss, ₹2 lakh of it can be set off against your salary this year and the balance carries forward for eight assessment years, usable only against house property income.
Can my spouse and I both claim on the same home loan? Yes, if you're both co-owners and co-borrowers and both actually repaying. Each of you claims your share, up to ₹2 lakh of interest and your share of principal under 80C. On a large loan this can nearly double the household claim.
Do any of these deductions work under the new tax regime? Mostly not. No 24(b) on self-occupied property and no 80C. Interest on a rented property can still be set against that property's rent, but a resulting loss can't touch your salary and can't be carried forward.
What about a home loan on an under-construction flat? Nothing is claimable while it's under construction. The interest you pay in that period gets added up and claimed in five equal instalments from the year you take possession, on top of that year's normal interest, within the same overall limits.
Which ITR form do I use with two house properties? For AY 2026-27 ITR-1 was expanded to allow up to two house properties, so many simple salaried cases now fit there. Three or more properties means ITR-2. If you're carrying a house property loss forward, check the form can record it before choosing.
Ready to take the next step?
Find out your loan options and check your eligibility with GoVitt today.